Foreign-currency non-resident deposits are set to keep a lid on Indian bank deposit rates, even as loan growth stays elevated and banks try to protect margins.
Indian banks to benefit from FCNR(B) funding buffer
The key takeaway from Reserve Bank of India Governor Sanjay Malhotra’s comments is that the $133 billion banks have raised through the FCNR(B) scheme gives lenders a sizable, lower-cost funding buffer at a time when credit growth is running at 18%, well above the 10% pace a year earlier. That combination reduces the immediate need for banks to aggressively bid up domestic deposit rates, even as lending yields on floating-rate loans reprice upward with policy changes and benchmark movements.
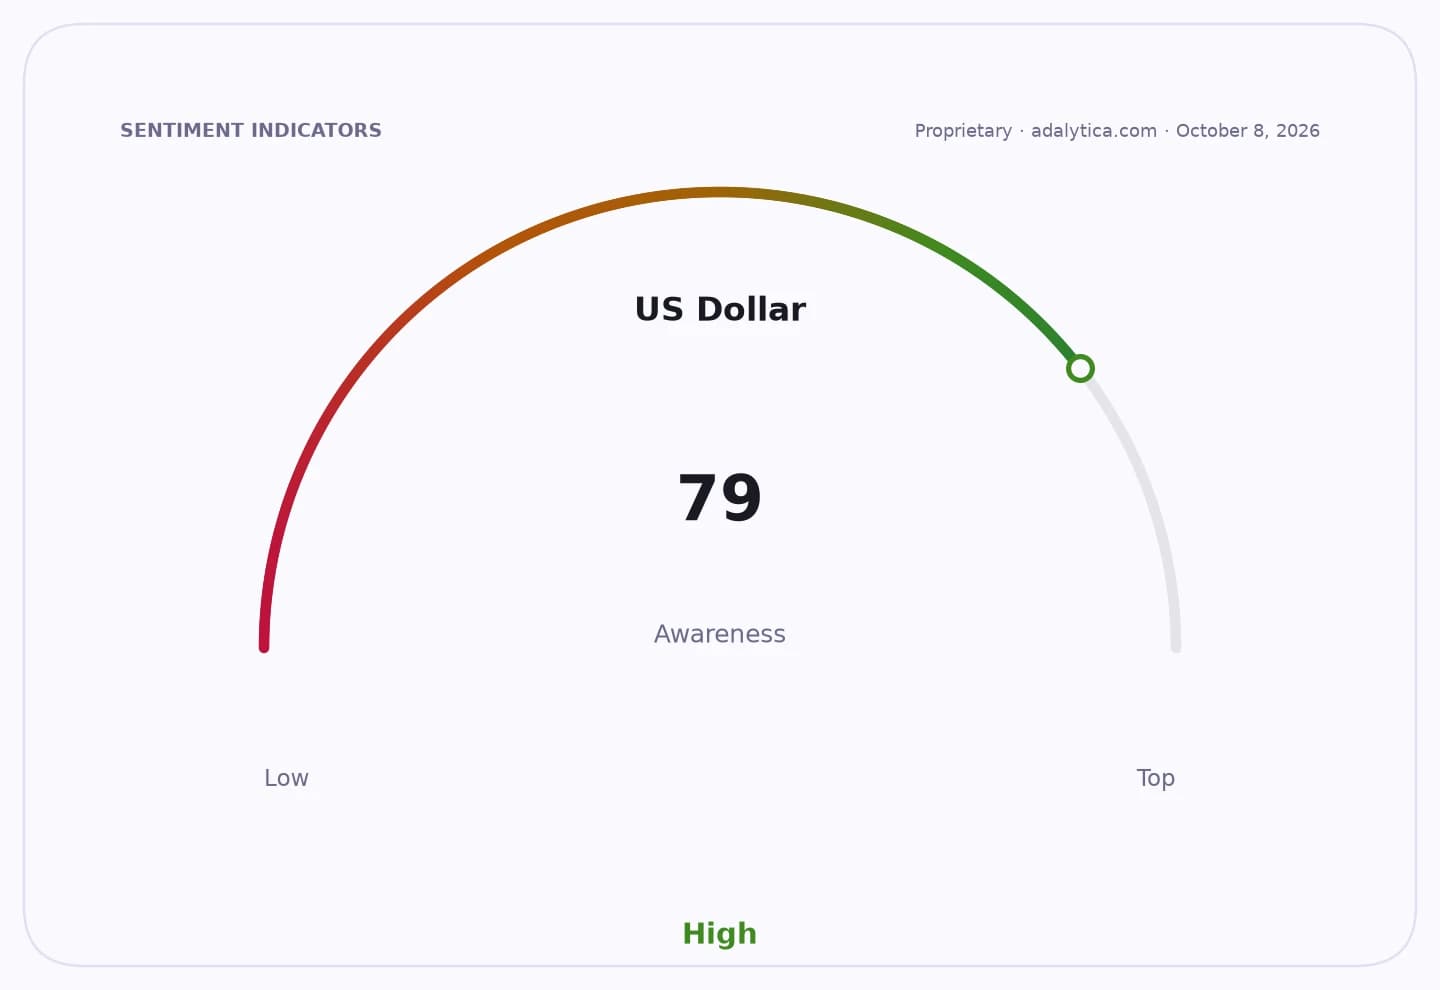
Sentiment IndicatorsⓘProprietary · adalytica.com · October 8, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, that matters because it points to a near-term margin tailwind for lenders, particularly those with large books of repo-linked floating-rate assets. Macquarie Securities said 54% of floating-rate loans at public-sector banks and 91% at private-sector banks are tied to the repo rate, meaning asset yields can reset faster than funding costs if deposit pricing stays restrained. That supports net interest margins, especially for banks with stronger retail loan franchises and limited reliance on wholesale funding.
Malhotra also signaled that the RBI does not want banks to rush the FCNR(B) money into lending without due diligence, underscoring that policy makers are treating the inflows as a liquidity-management tool rather than a signal to loosen credit conditions. He said the surplus liquidity is likely temporary, citing currency leakage and reserve requirements, and did not rule out further action, including a higher cash reserve ratio, though he called it one of the least preferred options.
The broader economic narrative is that the RBI is still comfortable allowing banks to enjoy some margin relief while it manages system liquidity carefully. For the economy, FCNR(B) inflows can help keep credit flowing without forcing banks to lift deposit rates as sharply, which reduces funding stress for borrowers and preserves transmission of monetary easing. The risk is that if liquidity drains faster than expected, banks may still need to reprice liabilities, especially if credit demand remains strong.
For shareholders, the immediate beneficiaries are banks with large floating-rate loan books and a strong FCNR(B) inflow base; the losers are depositors and rate-sensitive lenders that must compete harder for funds if the liquidity cushion fades. The next test will be whether FCNR(B)-supported funding lasts long enough to keep deposit costs subdued through the current credit cycle.
| Entity | Gains | Losses |
|---|---|---|
| Indian banks | ▲Lower deposit costs, wider margins | ▼Higher competition for deposits later |
| Borrowers | ▲Easier credit transmission, steadier loan supply | ▼Less leverage from falling funding costs |
| Depositors | ▲— | ▼Slower rise in savings and term rates |
| RBI | ▲Better liquidity control | ▼Pressure if surplus drains faster than expected |