Indonesia’s financial regulator is probing 15 entities suspected of operating as unlicensed insurance and reinsurance brokers, a crackdown that underscores rising pressure on a sector OJK is trying to harden against fraud, weak capital and reporting risks.
Indonesia OJK probes 15 unlicensed insurance brokers
Four of the entities have already been handed to OJK investigators and entered the formal investigative stage, OJK said, while the broader probe may expand as new information comes in. The move matters because unlicensed brokers can leave policyholders exposed to mis-sold coverage, payment disputes and opaque risk placement, while also undercutting compliant insurers and intermediaries.
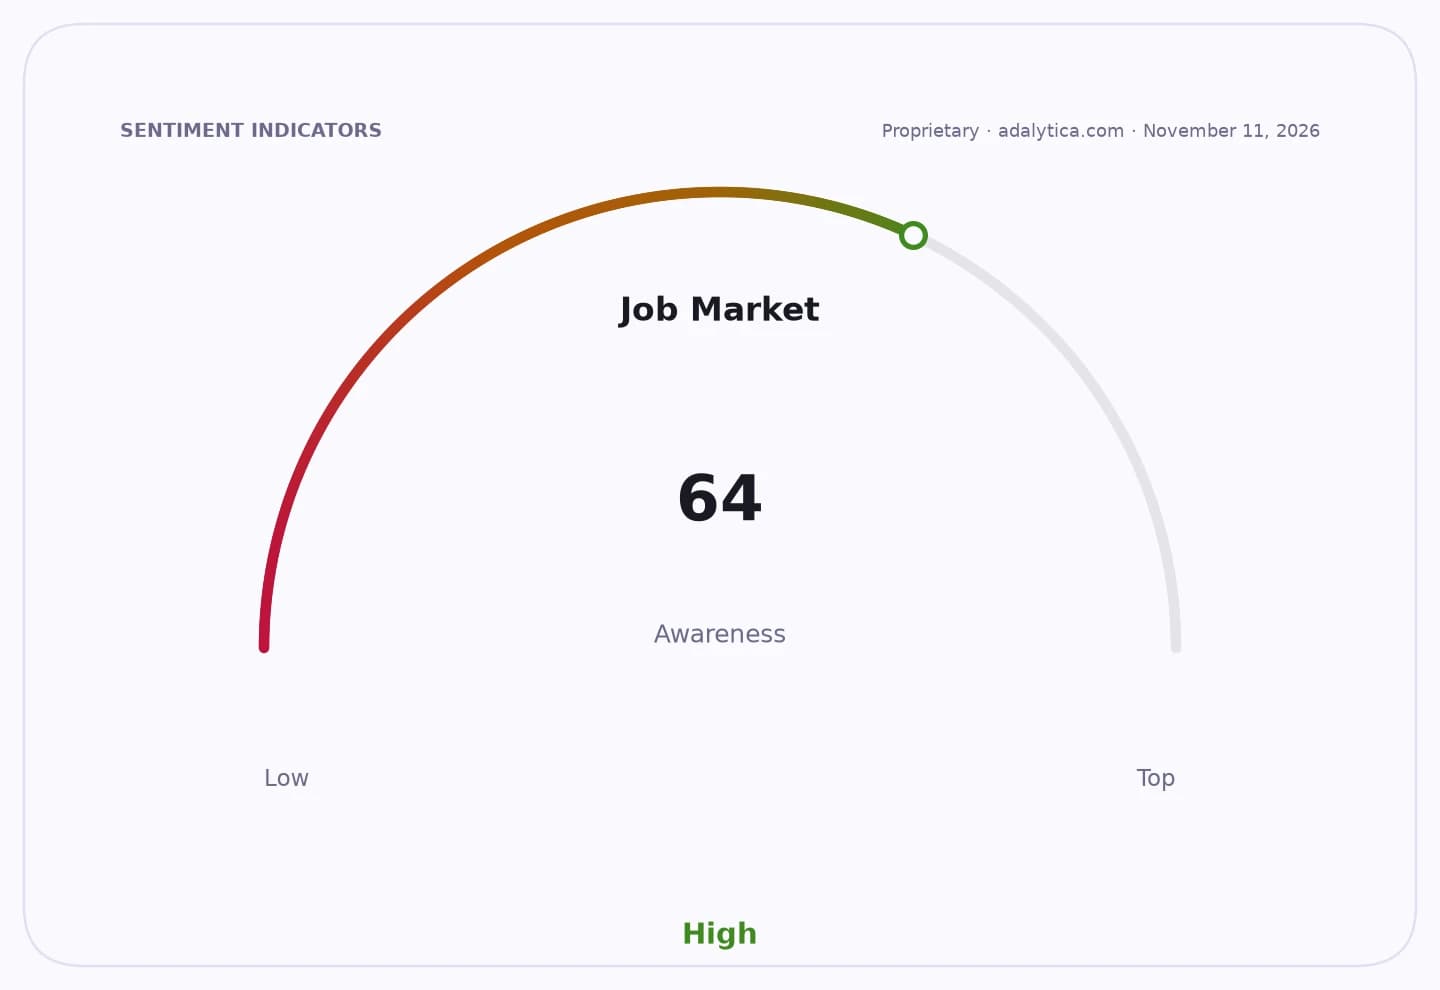
Sentiment Indicators
OJK said the enforcement push is part of a wider effort to strengthen supervision of Indonesia’s insurance industry. That effort is not limited to illegal brokers: the watchdog is also pushing insurers and reinsurers to meet minimum equity requirements and has rolled out two new rules, one on solvency calculations and another on the integrity of financial reporting across insurance, guarantee and pension sectors.
The regulator said 83.45% of insurance and reinsurance companies have met the first phase of minimum equity requirements, while compliance among guarantee firms stands at 79.17%. Industry assets reached Rp1,192.84 trillion as of September 2026, up 0.98% from a year earlier, and commercial insurance premiums grew 2.61% to Rp252.80 trillion.
For investors, the message is twofold: regulatory cleanup can support long-term confidence in Indonesian insurers, but it can also raise compliance costs and expose weaker players that rely on loose controls. The new solvency and reporting rules suggest OJK is moving beyond isolated enforcement cases toward a broader tightening of capital discipline and disclosure standards.
The next test is whether the investigations expand, and whether the new rules accelerate consolidation among smaller insurers, brokers and guarantee companies that struggle to meet capital thresholds.
| Entity | Gains | Losses |
|---|---|---|
| OJK | ▲Stronger supervisory credibility | ▼More enforcement burden |
| Licensed insurers and brokers | ▲Cleaner market, better trust | ▼Higher compliance costs |
| Illegal brokers | ▲None | ▼Investigations, shutdown risk |
| Policyholders | ▲Better protection | ▼Short-term disruption in broker channels |