IREN shares climbed after Northland Securities initiated coverage with a Buy rating and a $99 price target, reviving the bull case that AI infrastructure providers can capture a far larger share of the AI buildout than the market currently discounts.
IREN Rises on Northland Buy Rating and $99 Target
The move matters because it reframes IREN less as a single stock story and more as a proxy for the economics of the neocloud trade: companies building and renting AI compute, data-center capacity and related services. Northland’s Nehal Chokshi argued the addressable AI-as-a-service market could eventually reach about $4 trillion, far above today’s spending levels and well beyond what is likely to be in place by the end of 2027. That gap implies years of demand growth, but also a prolonged capital race before supply catches up.
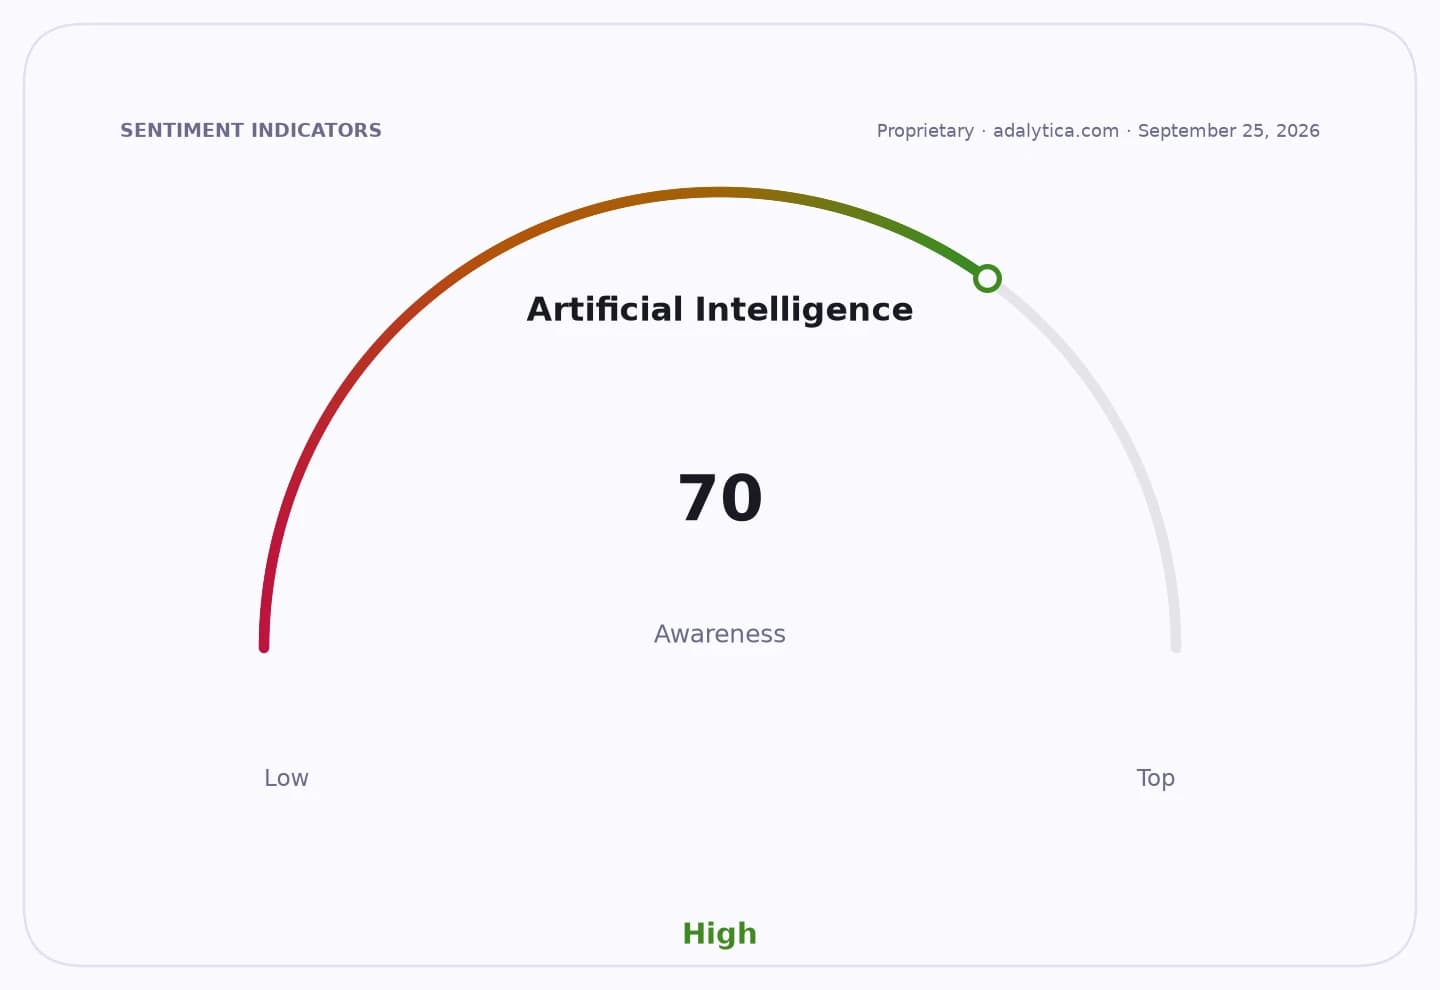
Sentiment IndicatorsⓘProprietary · adalytica.com · September 20, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
IREN rose about 3% to around $45 in Friday afternoon trading, still below Northland’s target and under the analyst’s estimate of 123% upside. The stock has been volatile, which is typical for early-stage AI infrastructure names whose valuations are tied less to current earnings and more to expectations for contracted capacity, financing access and utilization. IREN’s own filing underscores that it will need to raise capital to fund new sites, equipment and AI cloud expansion, a reminder that growth in this part of the market is capital intensive even when demand is strong.
Northland’s broader call on four neocloud names — IREN, Boost Run, ChronoScale and SharonAI — reflects a wider thesis that the group remains relatively cheap versus long-term growth potential. But the firm also drew a line between commodity compute providers and the eventual winners: the companies that differentiate with software features and higher-value services, not just raw processing power. That distinction matters for investors because it points to margin dispersion. In a market where capacity can be copied, software and workflow integration are likely to determine who earns returns above the cost of capital.
The research comes as AI infrastructure spending remains a central theme across the sector. Nvidia, AMD and Amazon are all tied to the buildout through chips, cloud infrastructure and data-center investment, while Amazon’s filing shows continued heavy spending on technology and infrastructure to support scale. AMD’s recent share strength and Amazon’s willingness to keep investing reinforce the same macro trade: AI demand is still pulling capital through the ecosystem, even as the market debates how quickly that spending can translate into durable profits.
For investors, the key question is whether IREN and peers can convert hype into contracted, cash-generating capacity before competition compresses returns. A 5-star analyst’s Buy rating and a $99 target can help sentiment, but the stock’s ultimate path will depend on financing, execution and whether AI customers keep paying up for scarce capacity. If Northland’s long-range market view proves even directionally right, the upside for leaders could be substantial; if oversupply arrives faster than expected, the same companies could face valuation pressure as investors reassess how much of that future really belongs to them.
| Entity | Gains | Losses |
|---|---|---|
| IREN | ▲Higher valuation support | ▼Skeptics of capital-heavy growth |
| Northland / bullish analysts | ▲Early call credibility | ▼Bears on neocloud valuations |
| Neocloud peers | ▲Sector re-rating potential | ▼Firms lacking software differentiation |
| AI chip/cloud suppliers such as AMD and AMZN | ▲More infrastructure demand | ▼Investors expecting slower AI capex |