Iron Mountain is pressing deeper into IT services and data centers just as investors reprice the business as a higher-growth infrastructure play, with the stock swinging sharply around its latest quarterly filing and the broader data center sector still drawing capital despite recent market volatility.
Iron Mountain expands into IT services and data centers
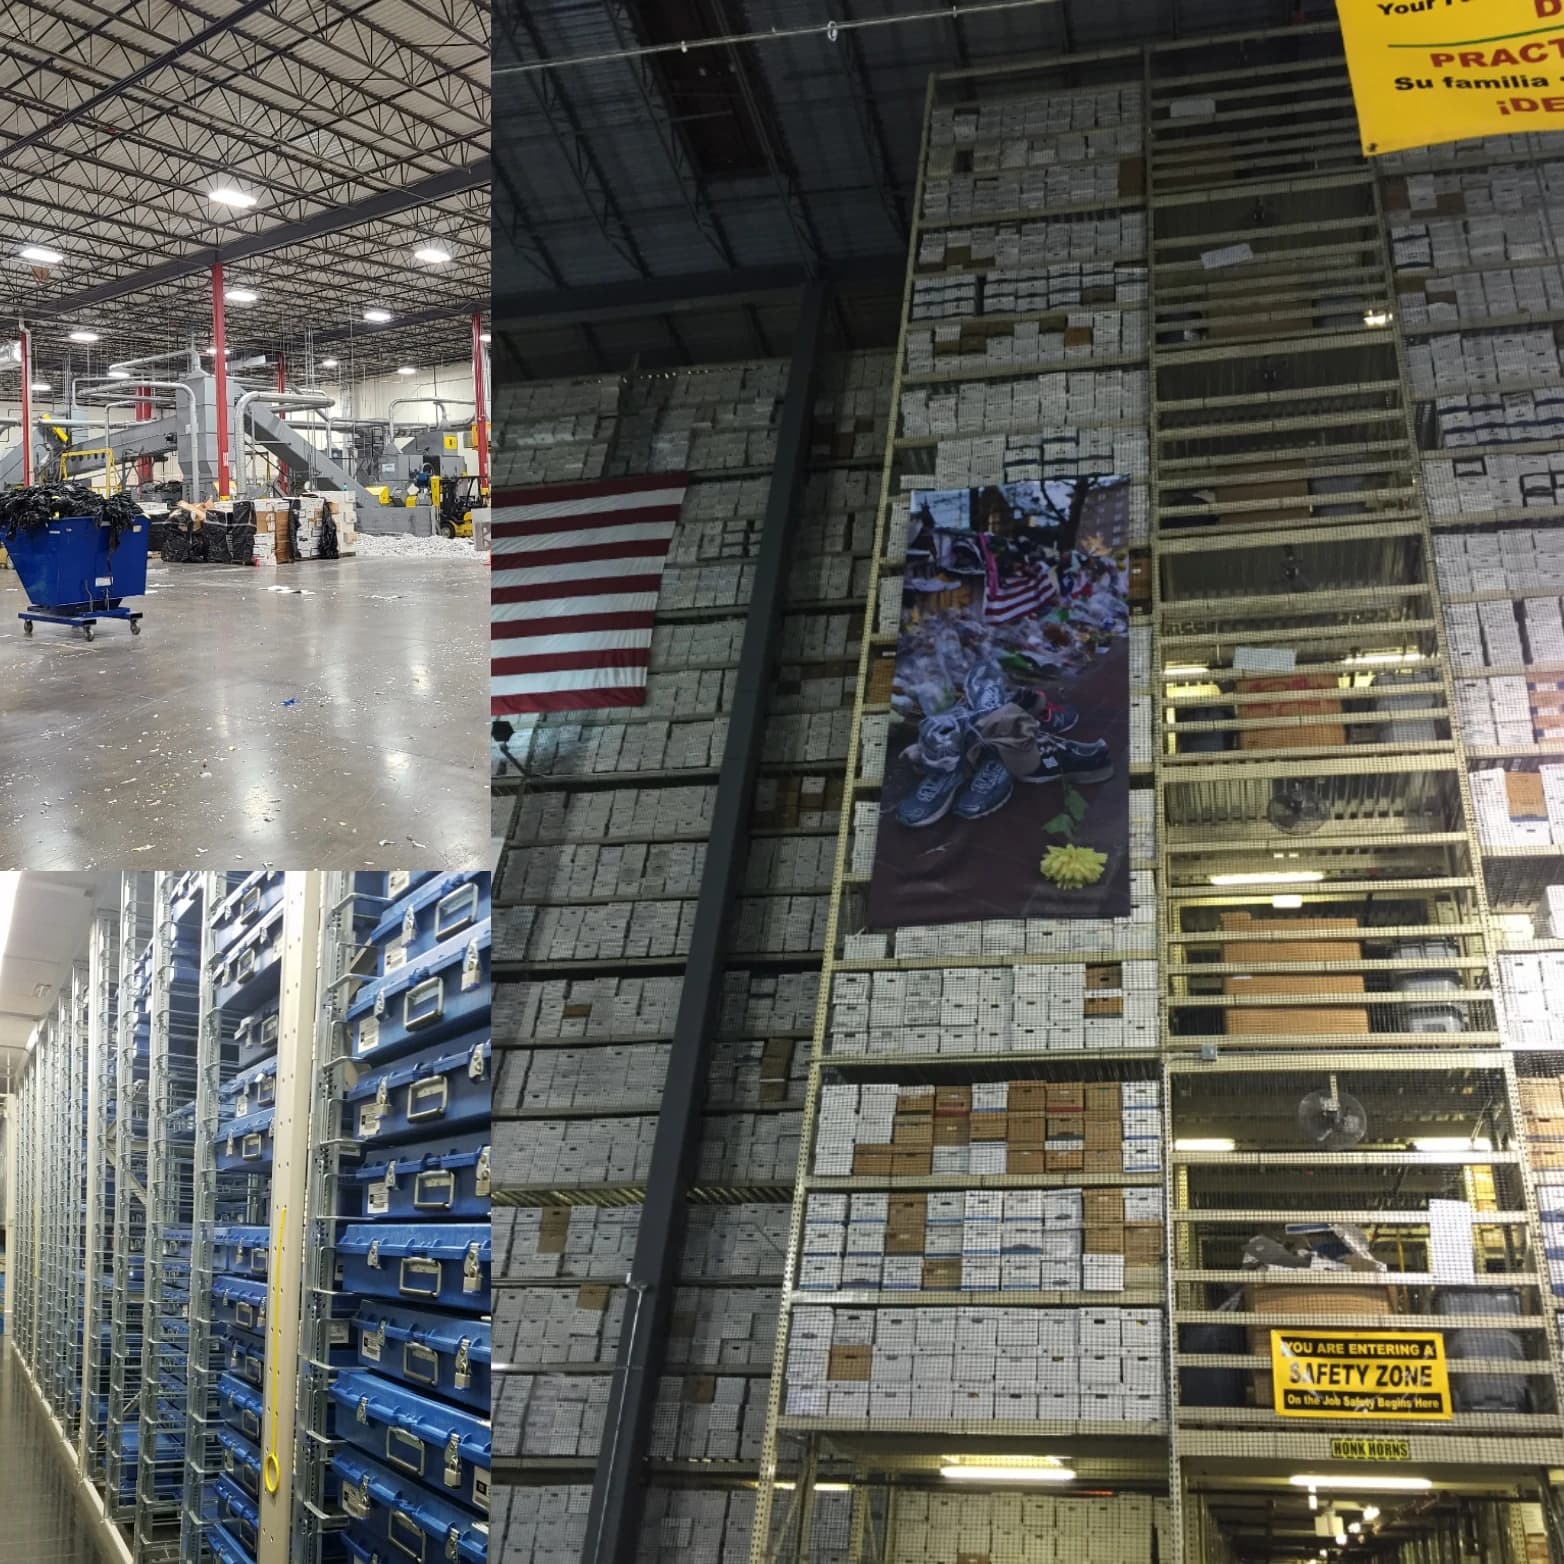
The key takeaway for investors is that Iron Mountain is no longer being valued purely as a records-storage company. Its newer technology and data-center businesses are increasingly central to the equity story, and the latest 10-Q underscores why: management continues to highlight organic revenue growth that reflects both storage and service expansion, including the impact of customer-relationship acquisitions.
Sentiment Indicators
That shift matters because it changes the company’s earnings mix and multiple. A larger contribution from IT services and data centers can support faster revenue growth and a richer valuation if margins hold up, especially at a time when demand for digital infrastructure remains resilient across the sector.
The stock has been unusually volatile. Iron Mountain fell as low as $105.50 on Nov. 5 before rebounding to $112.56 on Nov. 9, after hitting $118.66 just a day before. The move came alongside heavy trading and a reset in technical momentum, with the shares slipping back toward their 50-day moving average and the 200-day line after a strong run earlier in the year.
By contrast, peers tied to digital infrastructure have remained firmer. Equinix and Digital Realty have both been buoyed by persistent demand for data-center capacity, even as their own filings point to pricing pressure, supply-chain constraints and regulatory friction around power and land. That backdrop helps explain why Iron Mountain’s expansion into IT services is being watched closely: it is competing for a slice of the same capital-spending cycle that is rewarding scale, capacity and customer stickiness.
For investors, the question is whether Iron Mountain can keep converting that growth into durable cash flow without overextending leverage or diluting returns through acquisitions. The next catalyst is likely to be management’s follow-through on post-earnings guidance and evidence that the IT services push is accretive rather than merely additive.
| Entity | Gains | Losses |
|---|---|---|
| Iron Mountain | ▲Higher-growth mix | ▼Storage-only valuation |
| Data center investors | ▲More infrastructure exposure | ▼Less scarcity premium if supply expands |
| Equinix | ▲Sector demand backdrop | ▼New competition for enterprise spend |
| Digital Realty | ▲Industry tailwind | ▼Competitive pricing pressure |