Italy’s borrowing premium over Germany narrowed only marginally on the day, but the more important message for markets is that the Btp-Bund spread is holding near a level that suggests investors are not yet demanding a fresh risk penalty for Rome.
Italy 10-Year Btp-Bund Spread Holds Near 106 bps
The 10-year Btp-Bund spread closed at 106 basis points, down by about 1 point, while the Italian 10-year yield was essentially unchanged at 4.48%. That matters because sovereign yields are the price of money for a government: when they stay elevated, refinancing debt gets more expensive, fiscal room narrows and banks, insurers and domestic asset values feel the strain. When they stop rising, as they did here, it gives Italy a little breathing space without changing the larger debt arithmetic.
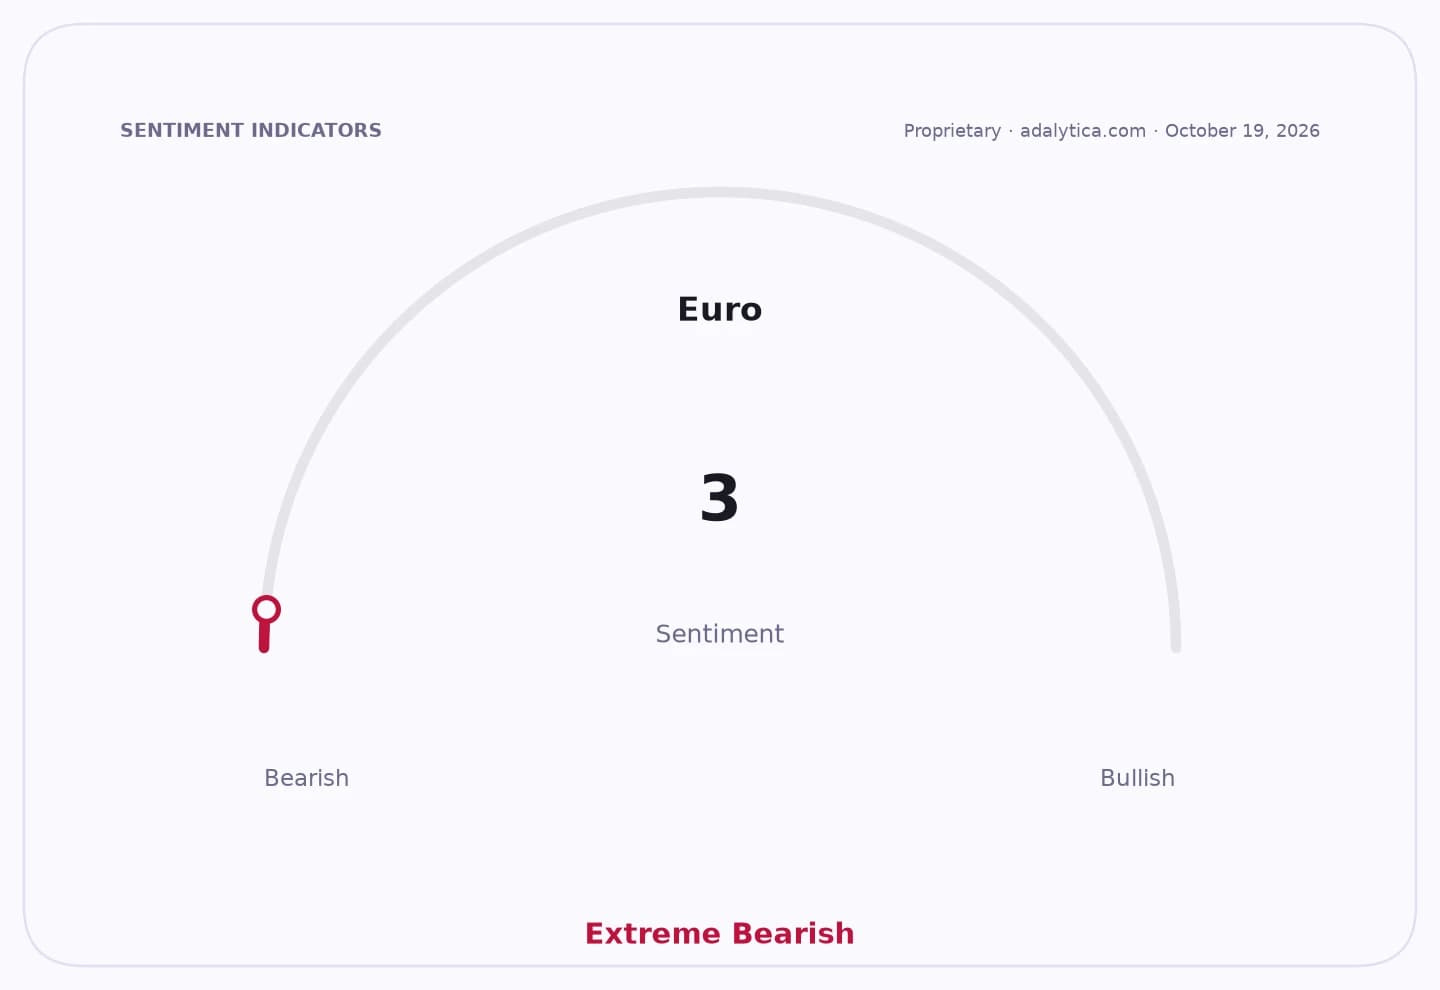
Sentiment IndicatorsⓘProprietary · adalytica.com · October 19, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, the real story is not the tiny move itself but the stability behind it. A spread around 106 basis points says Italy is neither in stress mode nor in a decisive repricing. That keeps domestic bondholders from facing an immediate loss of confidence trade, but it also leaves the market sensitive to any shift in politics, growth or ECB expectations. With Italy carrying one of the euro zone’s heaviest debt loads, even a modest move in yields can quickly translate into meaningfully higher funding costs at auction and over the refinancing cycle.
The backdrop also matters across Europe. Bond markets have been prone to bouts of nervousness as political uncertainty and fiscal concerns surface in the region, and Italian debt is one of the clearest pressure points. A flat close on the Btp does not remove that risk; it simply shows that traders were unwilling to press the trade harder in this session.
There is a broader investment implication here. If sovereign spreads remain contained, Italian banks, utilities and domestic cyclicals get a valuation tailwind because funding fears ease. If the spread starts widening again, those same names typically underperform first. For now, the market is signaling balance rather than alarm.
The takeaway is straightforward: Italy has avoided a fresh selloff, but at 106 basis points the market is still pricing a meaningful premium over Germany. Investors should treat that stability as a pause, not a verdict.
| Entity | Gains | Losses |
|---|---|---|
| Italian government | ▲Lower immediate funding pressure | ▼Still pays a risk premium |
| Btp holders | ▲Stable prices, no fresh shock | ▼Limited upside from yields |
| German Bunds | ▲Safe-haven status preserved | ▼Less relative yield pickup |
| Italian banks and domestic cyclicals | ▲Easier financing conditions | ▼Vulnerable if spreads widen |