Italy’s BTP-Bund spread remains in flight, with the 10-year BTP yield climbing to 4.7% and the premium over German debt widening to as much as 131 basis points as investors reassess Italy’s financing outlook against a backdrop of firmer rate expectations and energy-driven volatility.
Italy BTP-Bund Spread Widens to 131 Basis Points
The move matters because the spread is the market’s clearest real-time measure of Italy’s sovereign risk. A wider gap increases the state’s borrowing cost, feeds through to corporates and banks, and makes it harder for Rome to finance public investment without crowding out other spending. It also raises the odds that Italian debt will underperform broader euro-area benchmarks if global rates stay higher for longer.
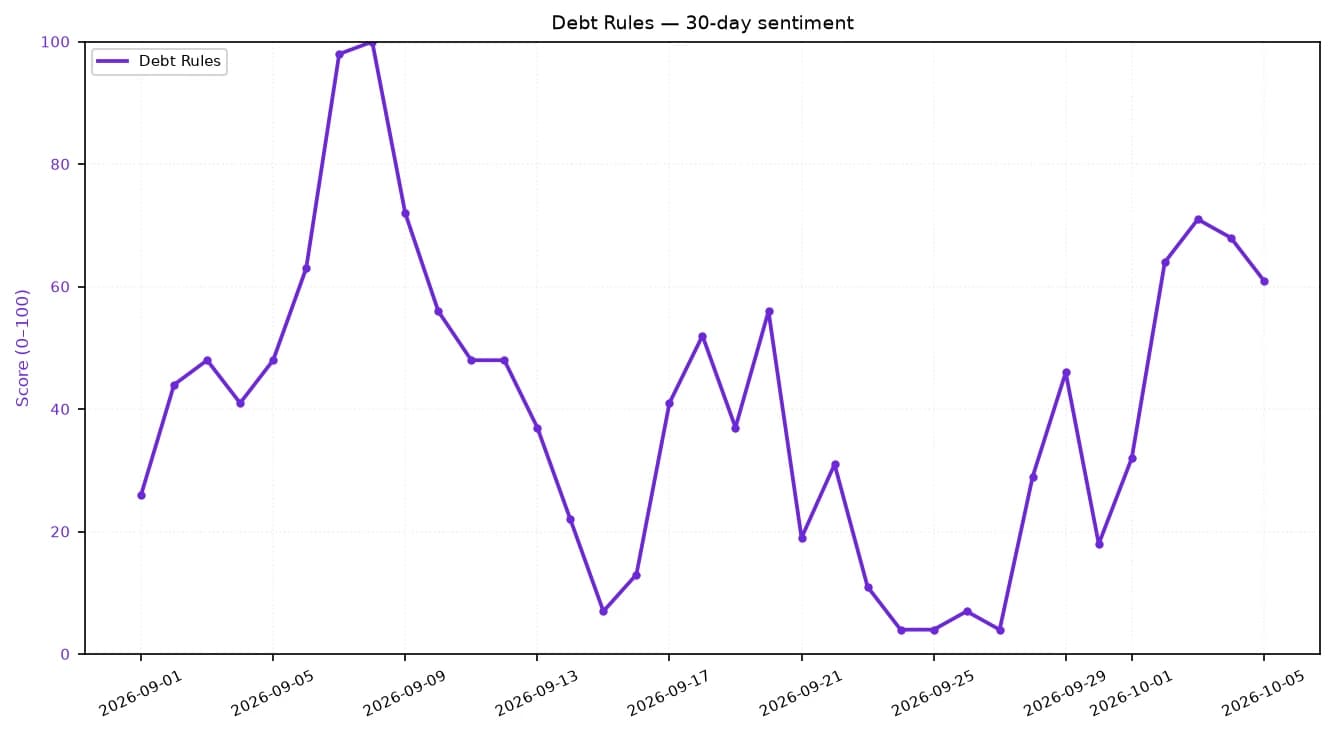
Sentiment IndicatorsⓘProprietary · adalytica.com · October 5, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The latest pressure appears tied to a mix of geopolitical and macro forces rather than a single domestic shock. Rising tensions around energy supply routes, including the Strait of Hormuz, have lifted oil-price sensitivity across European fixed income and reinforced expectations that central banks may keep policy restrictive for longer. For Italy, which carries one of the euro zone’s heaviest debt loads, even modest moves in funding costs can quickly become material.
Market participants have also been watching the Treasury’s response. Italy has repurchased about €5 billion of BTPs in an effort to steady trading and ease disorderly moves, a reminder that authorities are trying to keep spreads from becoming self-reinforcing. But the intervention has not yet brought a durable calm, with the spread still oscillating in a 100-to-131 basis-point range.
The economic stakes are straightforward. A persistent widening would hit fiscal flexibility just as the government faces pressure from higher interest expenses and a weaker household backdrop. Istat reported a second-quarter fiscal deficit equal to 2.0% of GDP, a slightly better reading than a year earlier, and a primary surplus of 3.0%, but the same data showed household purchasing power falling 0.9% from the prior quarter and the savings rate sliding to 6.7%. That mix suggests the domestic economy is not strong enough to absorb a prolonged jump in financing costs without strain.
For investors, the trade-off is between carry and risk. Italian bonds still offer pickup over core euro debt, which keeps them attractive to yield-seeking buyers, but the recent move shows how quickly that premium can be eroded when energy shocks or ECB expectations shift. Bank balance sheets, domestic lenders and rate-sensitive Italian equities are the most exposed if the spread remains near the top of its recent range.
The near-term catalyst will be the next move in energy markets and any signal from the ECB that policy will stay tight. If those forces ease, the spread could retrace some of the move. If not, investors are likely to keep demanding a larger risk premium for holding Italy’s debt.
| Entity | Gains | Losses |
|---|---|---|
| German Bunds | ▲Safe-haven demand | ▼Relative yield appeal |
| Italian government debt | ▲Higher carry buyers | ▼Price performance |
| Italy’s Treasury | ▲Temporary market support from buybacks | ▼Higher funding costs |
| Italian banks and equities | ▲Stable spreads | ▼Mark-to-market pressure |