Italy’s Treasury sold 3 billion euros of a new 10-year Btp at a yield of 4.58%, underscoring how elevated government funding costs remain even as demand for eurozone debt holds up.
Italy sells 10-year Btp at 4.58% yield
The auction matters because the sovereign is still refinancing itself at rates that are materially above the levels that prevailed before the global rate shock, keeping pressure on Italy’s debt dynamics and on all borrowers that price off benchmark government paper. The 4.58% yield was well above the 4.1% achieved at the previous 10-year sale in August, even though the bid-to-cover ratio of 1.56 showed the market absorbed the supply without signs of outright strain.
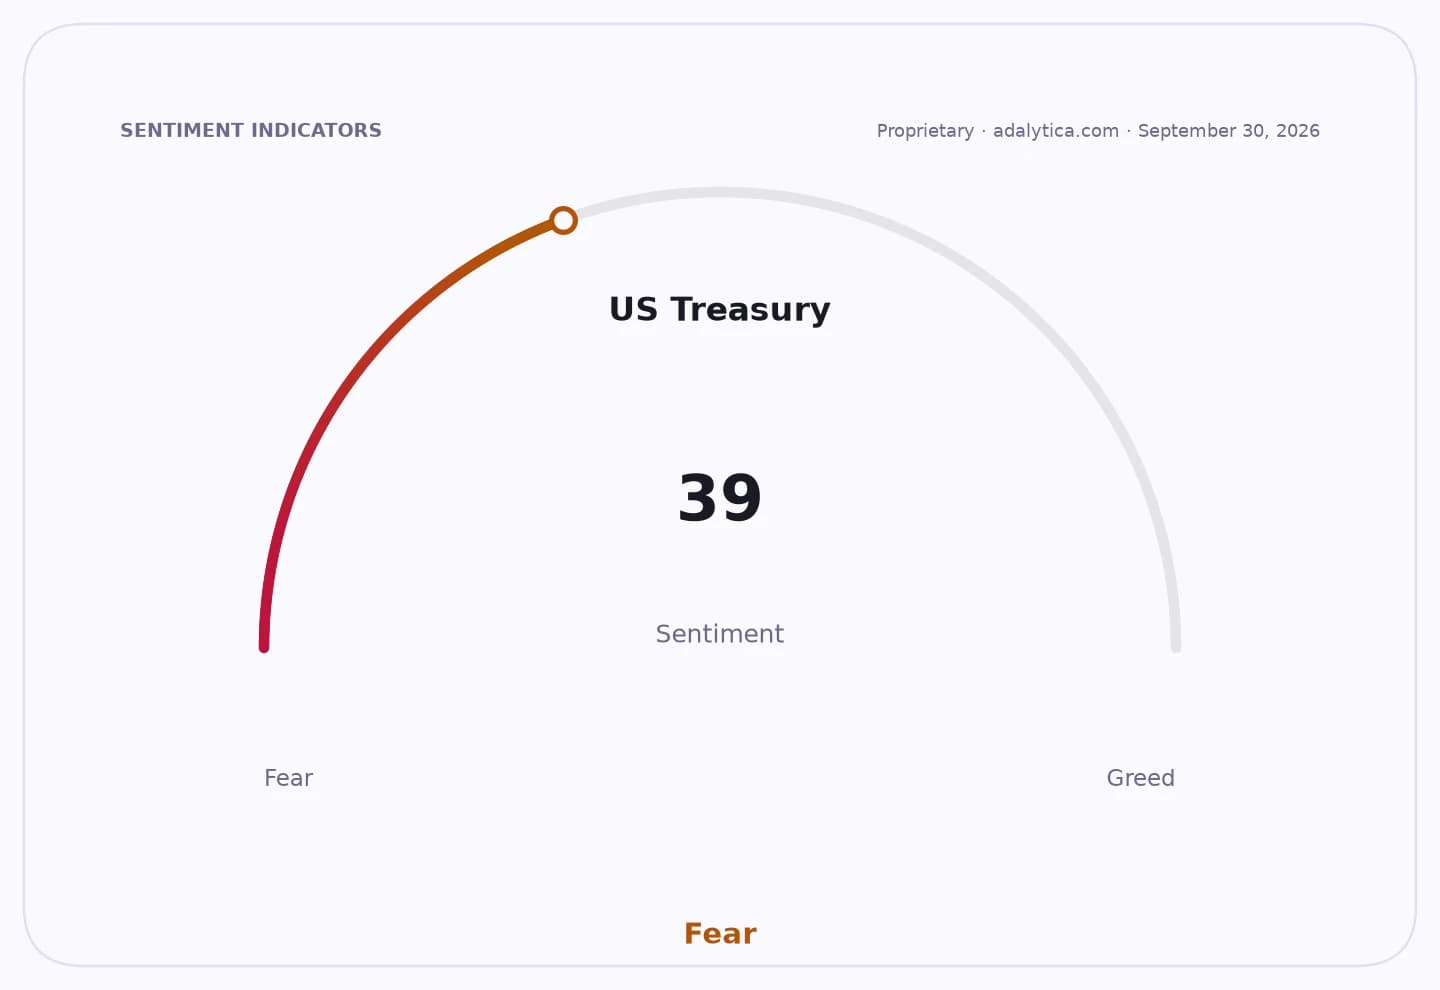
Sentiment IndicatorsⓘProprietary · adalytica.com · October 6, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Investors are watching the auction as a read-through on how much compensation buyers now demand for long-dated Italian risk in a higher-for-longer rates environment. The new October 2036 bond, with a 4% annual coupon, was priced at 95.76 versus a 95.54 close the day before, implying only limited concession to clear the sale. Net yield, according to Assiom Forex calculations, came in at 4.051%, but the gross level still leaves Italy financing itself at a cost that keeps debt-service metrics tight.
The result also fits a broader pattern in sovereign markets where large borrowers are contending with structurally higher yields after years of ultra-low rates. With $10-year U.S. Treasury yields hovering above 5% in recent sessions and European debt markets adjusting to sticky inflation and heavy issuance, investors are differentiating more aggressively between issuers. That tends to benefit buyers who can lock in high coupons, but it penalizes governments and rate-sensitive sectors that must roll debt at today’s levels.
For Italy, the key question is not whether auctions can clear — they can — but how long the Treasury can keep funding at these rates without eroding fiscal flexibility. Strong enough demand at this sale suggests no immediate financing stress, yet the persistent premium over earlier auctions signals that the market is still demanding compensation for Italy’s debt load and slower growth prospects. Future auctions will show whether the 4.6% area becomes a new norm or whether improving rate expectations allow yields to ease.
| Entity | Gains | Losses |
|---|---|---|
| Btp buyers | ▲Higher coupon income | ▼Mark-to-market risk |
| Italian Treasury | ▲Successful funding access | ▼Higher debt-service costs |
| Existing Btp holders | ▲Limited auction concession | ▼Pressure from higher yields |
| Rate-sensitive borrowers | ▲— | ▼Higher refinancing costs |