Japan's shrinking dependence on bank deposits is changing how monetary policy reaches households and companies, Bank of Japan board member Hajime Takata said, a shift that could make asset prices, foreign exchange and market funding more important channels for the economy.
Japan deposits fall as BOJ policy channels shift
In a Nov. 16 speech, Takata said cash and deposits made up 47% of Japanese households' financial assets at the end of June, down from 53% in 2022, as funds move toward risk assets and foreign currencies. Household financial assets rose to 2,500 trillion yen from 2,000 trillion yen in 2021, underscoring how much money is sitting in the system even as its composition changes.
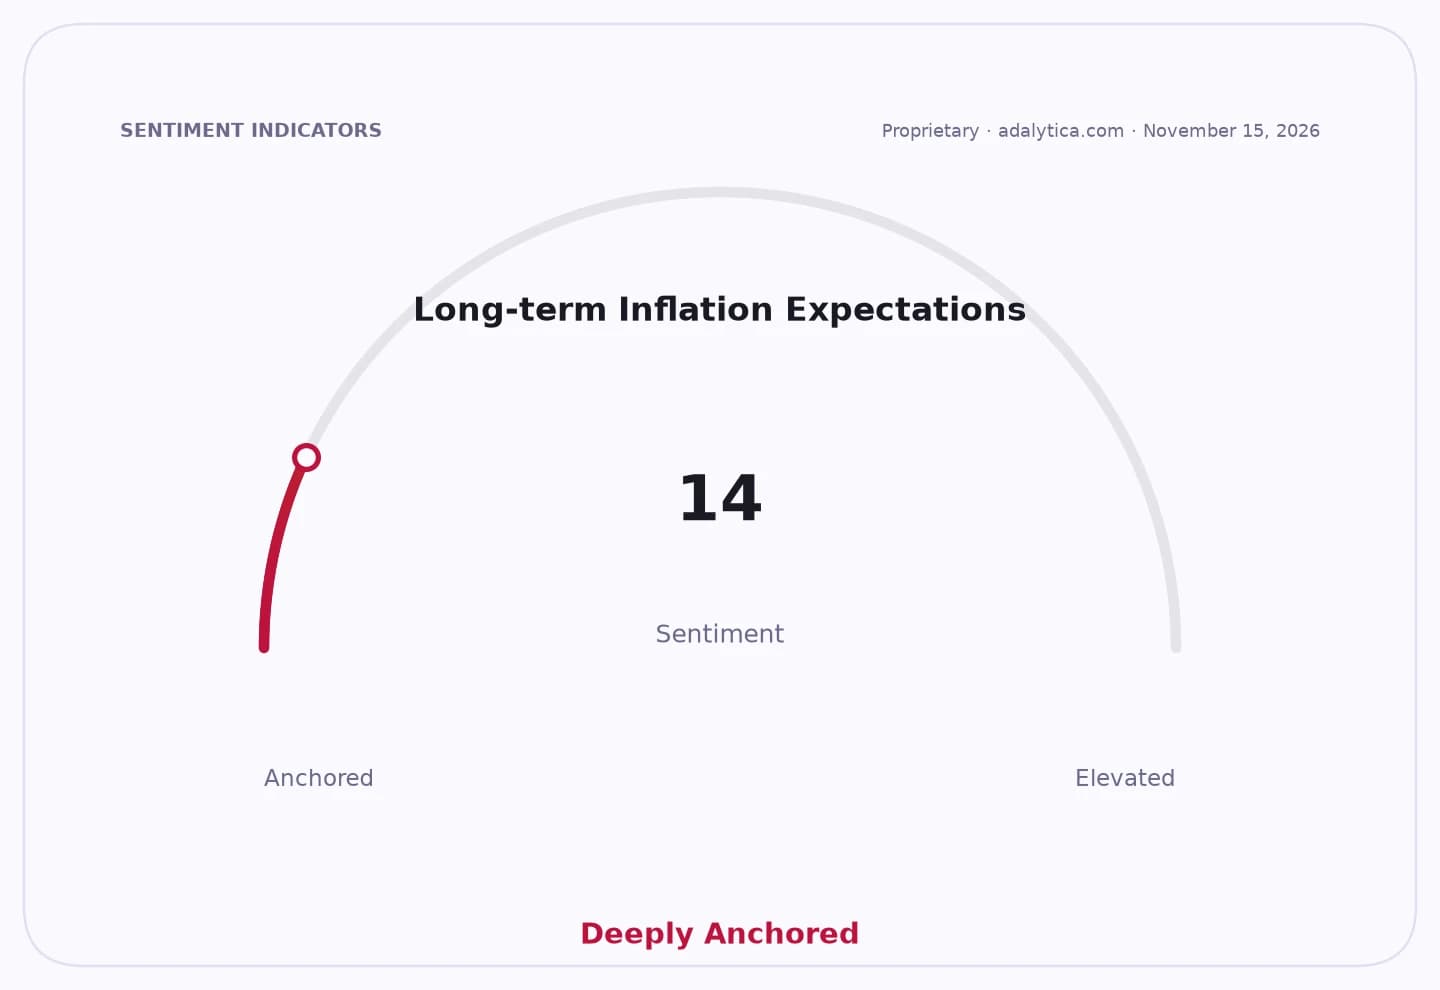
Sentiment Indicators
The structural shift matters because it changes the BOJ's policy leverage. If more savings flow into stocks, funds and overseas assets rather than deposits, interest-rate changes work less directly through banks and more through share prices, exchange rates and market borrowing costs.
Takata linked the trend to younger investors using the new Nippon Individual Savings Account, or NISA, and to older savers gradually moving out of cash with government support. He also said pension and invested assets have grown more than fivefold over two decades, while bank-loan growth has lagged.
That matters for Japan's financial system and for lenders. Companies increasingly need market-based funding for artificial intelligence investment and mergers and acquisitions, while deposit growth has been sluggish, raising pressure on banks to protect liquidity, improve return on equity and use balance sheets more efficiently.
Takata said Japan's syndicated-loan market has expanded and that a domestic private-credit market could emerge, even as nonbank finance still lags the U.S. and Europe. He added that the BOJ should keep making data-dependent rate decisions in 2026, rather than following a preset pace, as policy responses increasingly have to account for domestic conditions and overseas developments.
Investors are watching the shift because it supports a broader re-rating of Japanese financial assets: banks could face tighter deposit competition, while equity and fixed-income markets may gain from larger household participation and more active corporate fundraising.
| Entity | Gains | Losses |
|---|---|---|
| Japanese households | ▲More access to market returns | ▼Less reliance on deposit income |
| Banks | ▲Potential fee and lending opportunities | ▼Slower deposit growth |
| Equity and bond markets | ▲More retail inflows | ▼Higher funding competition for deposits |
| BOJ | ▲Broader policy transmission channels | ▼Less direct control through bank lending |