Japan’s biggest banks are set to extend a rare earnings upswing as the Bank of Japan’s higher policy rate pushes lending margins up and turns a long-feared tightening cycle into a profit tailwind.
Japan Banks Lift Profit Targets on Higher BoJ Rates
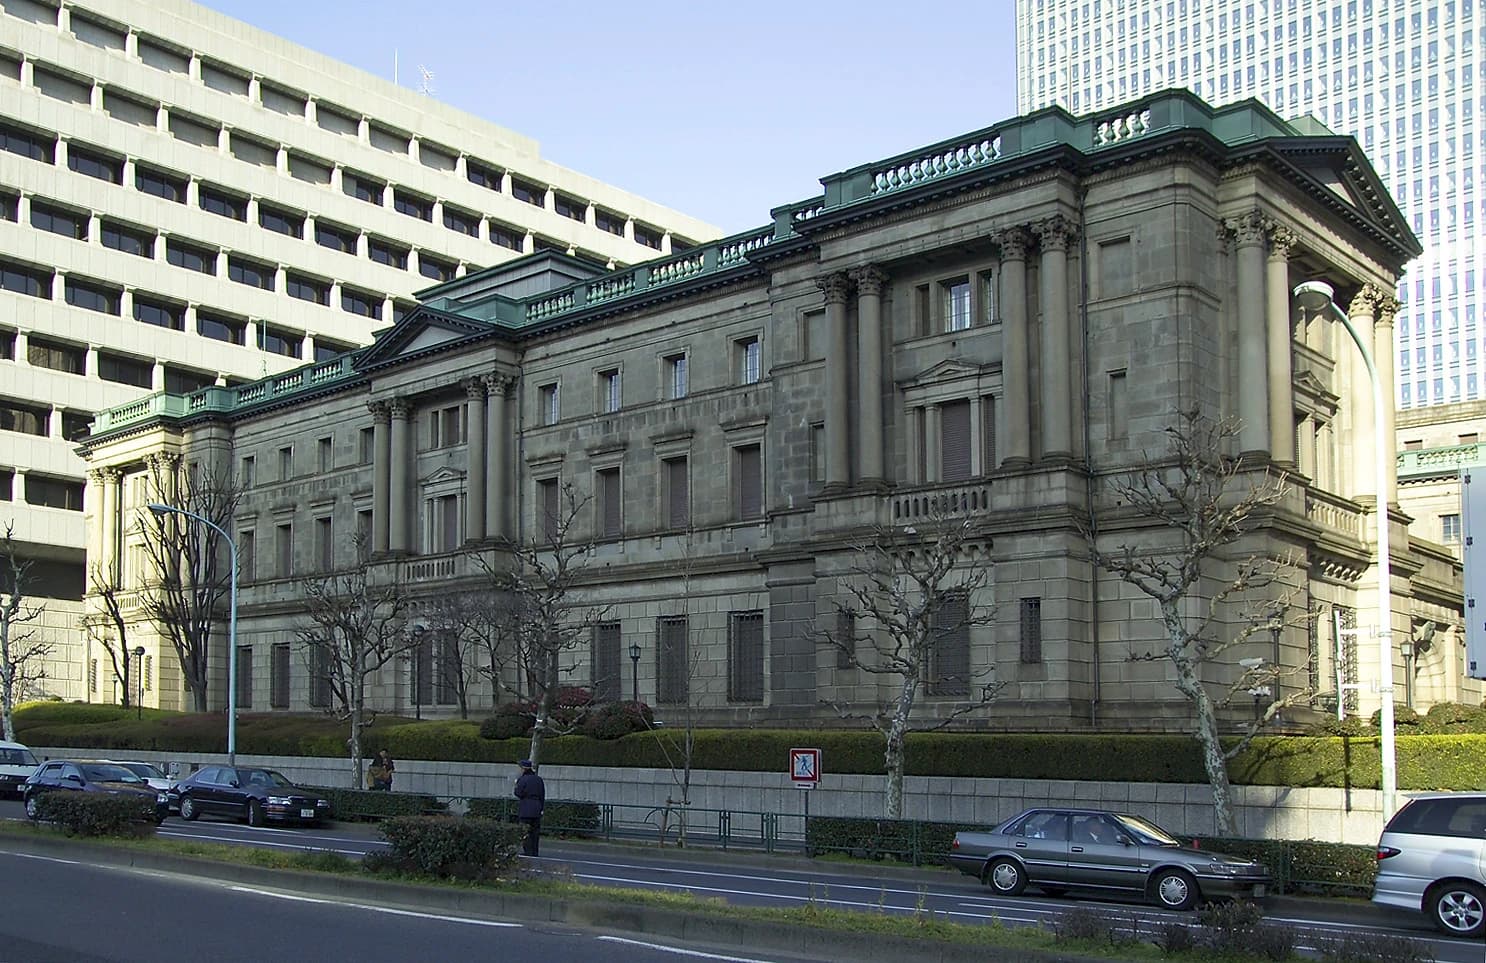
The central bank’s move away from ultra-low rates is beginning to show up in the real economy where it matters most for financial stocks: net interest income. Japan’s five largest banks have lifted profit targets and unveiled share buybacks after combined earnings moved close to 4 trillion yen, a notable reversal from years in which compressed margins left lenders struggling to grow.
Sentiment Indicators
For investors, the significance is twofold. First, higher rates in Japan now support a domestic banking model that had been structurally penalized by decades of near-zero borrowing costs. Second, the shift improves capital generation, giving banks more room to return cash rather than hoard balance-sheet strength. That makes Japanese lenders one of the clearest beneficiaries of policy normalization at a time when many global banks are grappling with slower loan demand and fading rate-cut expectations.
The backdrop is important. The Bank of Japan raised rates in September by 25 basis points to 1.25% as inflation risks persisted, reinforcing expectations that policy normalization is still in its early stages. That matters because the impact on banks is cumulative: even modest rate increases can meaningfully widen lending spreads when starting from such a low base. The latest profit upgrades suggest management teams are increasingly confident that the earnings benefit is durable rather than a one-off boost.
Market reaction has reflected that shift in leadership. The Invesco CurrencyShares Japanese Yen Trust, or FXY, has been trading below its 50-day moving average and its recent momentum indicators have weakened, even as the yen’s broader fundamental case has improved with tighter BoJ policy. By contrast, Japanese equities have already priced some of the banking upside, with the EWJ Japan ETF still holding above its 200-day moving average despite a recent pullback. That leaves the next leg of the trade dependent on whether earnings delivery and capital returns keep improving.
The macro implications go beyond banks. A stronger banking sector can support credit supply, household savers and corporate investment, while also giving the BoJ more latitude to continue gradual normalization without destabilizing the financial system. But there is a risk case: if rates rise faster than loan growth or if the yen strengthens too sharply, export earnings and equity sentiment could come under pressure.
For now, the market’s read is clear: Japan’s rate normalization is no longer just a policy story. It is starting to reshape bank profitability, shareholder returns and the investment case for Japanese financials.
| Entity | Gains | Losses |
|---|---|---|
| Japan's major banks | ▲Wider lending margins, buybacks | ▼Pressure to keep raising targets |
| Bank of Japan | ▲Policy credibility, gradual normalization | ▼Risk of slowing the economy |
| Bank shareholders | ▲Higher dividends and buybacks | ▼Less upside if rates stall |
| Yen exporters | ▲Stronger policy backdrop, better domestic demand | ▼Potential yen appreciation |