Floating mortgage rates in Japan were unchanged in August at an average 2.73%, underscoring how households are being forced to absorb a higher-rate regime even as short-term pricing pauses for now.
Japan mortgage rates unchanged in August
The flat reading matters because it suggests banks have not yet passed through the full impact of tighter funding conditions to variable-rate borrowers, but the broader direction remains up. Average mortgage rates overall have continued to climb, with the weighted average mortgage loan rate reaching 4.66% in August, the highest since November 2022, according to the data context. Credit loan rates have also moved above 6%, pointing to a broader tightening in household borrowing costs.
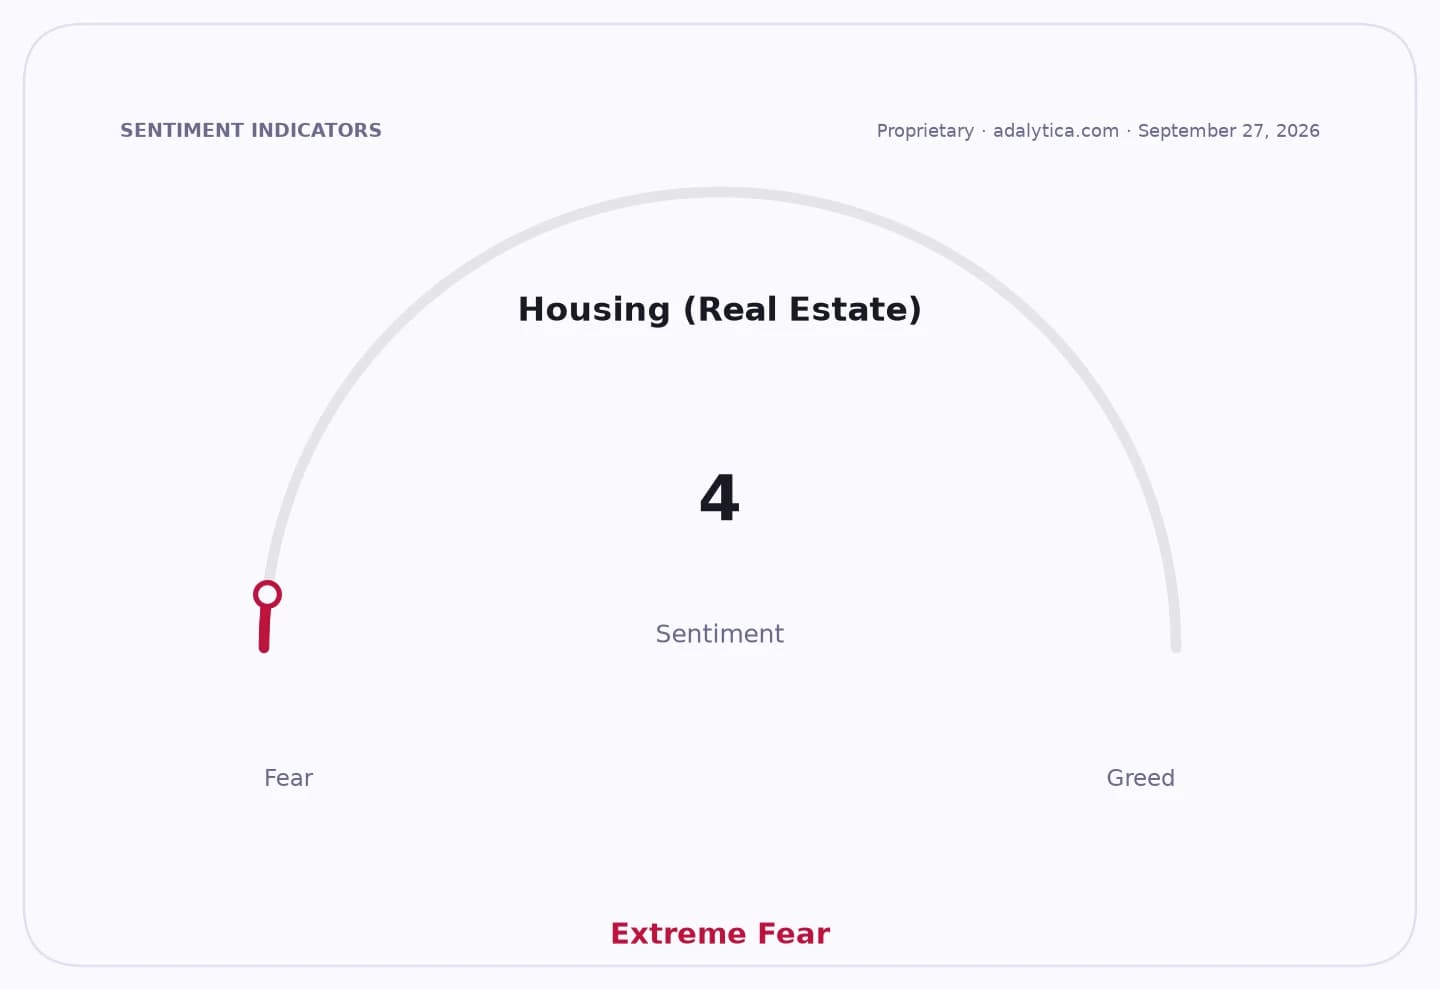
Sentiment IndicatorsⓘProprietary · adalytica.com · October 2, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For homeowners, the immediate message is one of temporary relief rather than a reversal. Variable-rate borrowers saw no change in August, but that stability came alongside a rise in longer fixed rates: three-year fixed mortgages were steady at 3.32%, while five-year fixed rates increased 0.11 percentage point to 3.56%. The widening gap between lenders on fixed loans also indicates that banks are competing more aggressively for longer-term business even as funding costs rise.
That dynamic matters economically because mortgages are one of the clearest channels through which central bank tightening hits consumption. In Japan, where many borrowers still favor floating-rate loans, even modest increases can erode disposable income and weigh on housing demand, renovation spending and broader consumer sentiment. The pressure is likely to be felt most acutely by households near refinancing points or those with thinner cash buffers.
Investors should also read the rate data as a signal for bank margins. Lenders typically benefit when loan yields rise faster than deposit costs, but a lag in repricing can compress returns in the near term. The fact that major banks, including Mizuho Bank, are set to raise fixed and variable mortgage rates further from October suggests the pressure is not easing. That keeps rate sensitivity in focus for Japanese lenders and for sectors tied to housing activity.
Market indicators point in the same direction. Long-duration U.S. Treasury bond ETF TLT has fallen sharply and is trading well below its 50-day and 200-day moving averages, reflecting persistent pressure on bond prices as yields stay elevated. The U.S. dollar has also shown signs of stress in the data snapshot, while housing and rent inflation sentiment remains cautious, reinforcing the idea that borrowing costs are still a drag rather than a tailwind.
The key narrative is that Japan’s mortgage market is moving from a period of stability to one of gradual repricing. August’s unchanged floating rate offered borrowers a pause, but the combination of higher overall borrowing costs and planned bank increases from October points to more strain ahead. For investors, that means watching not just the policy rate path, but how quickly lenders transmit higher rates into mortgages, credit demand and housing-related activity.
| Entity | Gains | Losses |
|---|---|---|
| Japanese banks | ▲Wider loan yields over time | ▼Near-term repricing lag |
| Floating-rate borrowers | ▲August payment stability | ▼Future rate increases |
| Fixed-rate borrowers | ▲Rate lock-in option | ▼Higher refinancing costs |
| Housing market | ▲Short-term transaction support | ▼Demand slowdown risk |