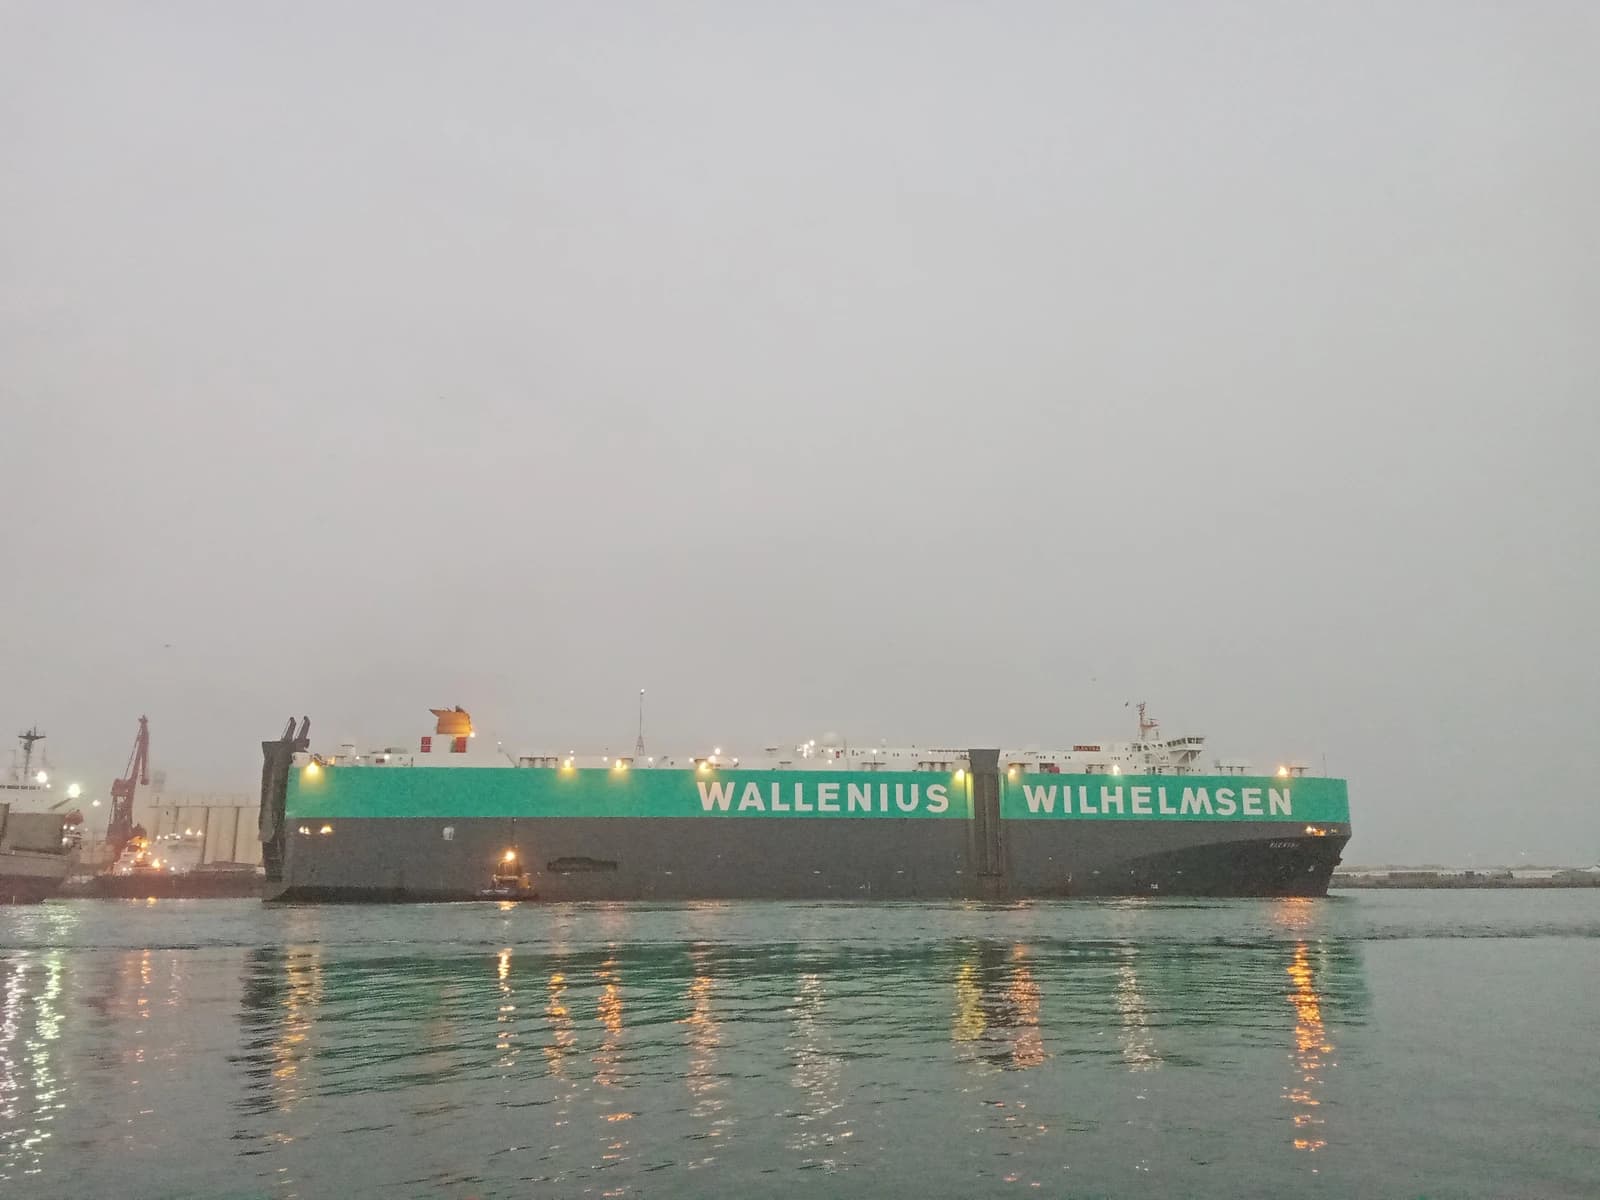
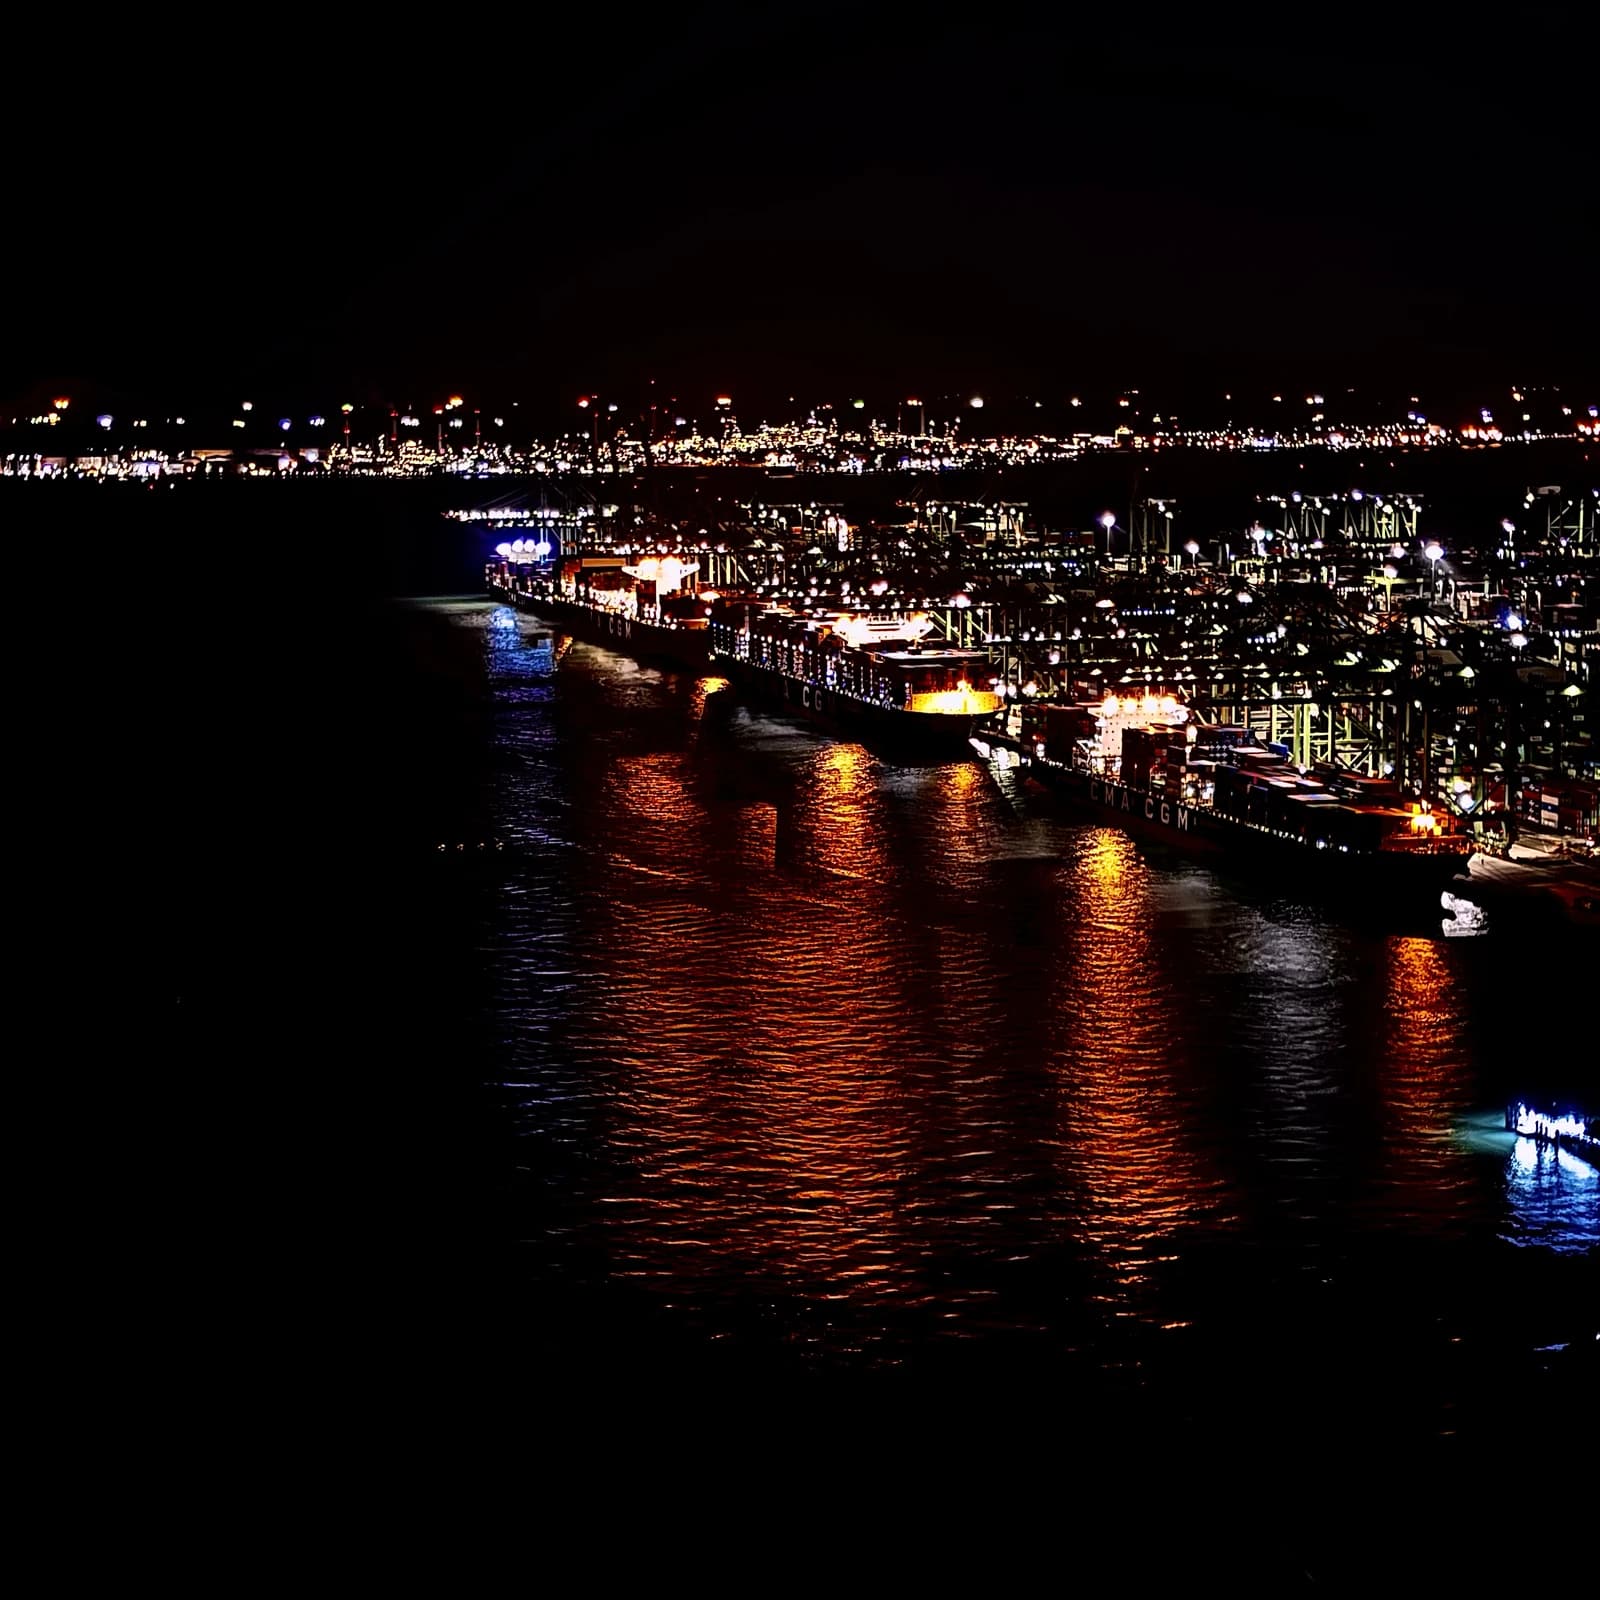
Kawasaki Kisen Kaisha, better known as K Line, is making a clear bet that the next phase of shipping will be won not just by moving boxes and tankers, but by turning logistics, data and energy services into a broader, higher-return industrial platform.
K Line Sets FY2031 ROE and Capital Targets
That matters because the Japanese carrier is trying to reshape a cyclical, capital-intensive business into one with steadier profits and better capital efficiency. K Line’s new medium-term plan through FY2031 calls for return on equity of at least 15%, net income of 120 billion yen or more, and a companywide ROIC of 7.5% or higher. For investors, that is a meaningful signal: management is no longer talking only about freight rates and fleet utilization, but about how to compound value across the shipping cycle.
Sentiment Indicators
The plan’s economic logic is straightforward. Global shipping remains vulnerable to swings in demand, fuel costs, vessel supply and geopolitical disruptions, from the Black Sea to the Strait of Hormuz and other chokepoints that can quickly alter freight flows. A carrier that can bundle marine transport with logistics, energy and adjacent supply-chain services has more ways to protect margins when spot rates cool. K Line is explicitly saying it wants to leverage its “integrated capability” to expand beyond core marine transportation and improve profitability by combining businesses and functions.
The capital plan is just as important as the operating targets. Over the five-year period, K Line expects operating cash flow of 1.0 trillion to 1.1 trillion yen and has outlined 700 billion to 800 billion yen in shareholder returns, including a planned dividend of 120 yen per share and possible additional returns through buybacks or special payouts. That combination suggests management wants to fund growth while still keeping a disciplined grip on capital allocation, a critical issue for shipping companies that have often over-earned in boom times and then overinvested.
K Line is also trying to bring technology into the center of the story. Its newly released AI and digital strategy is aimed at using data and AI to deepen what it calls integrated operational capability, which in plain terms means safer, more efficient shipping and better coordination across the network. That is not just corporate branding. In an industry where small efficiency gains can meaningfully move returns, better routing, predictive maintenance and cargo management can become real competitive advantages over time.
The environmental piece matters too. K Line revised its Environmental Vision for the first time since 2021 and set a target of net zero greenhouse gas emissions across Scope 1, 2 and 3 by 2050. It also wants to improve Scope 1 CO2 emission efficiency by 40% from 2024 levels by 2035. For investors, that speaks to the long game: shipping is under pressure to decarbonize, and carriers that can adapt early may face lower regulatory risk and better access to customers that increasingly want lower-emission transport.
The stock market, meanwhile, appears to be pricing a harsher near-term reality. K Line’s U.S.-listed shares have fallen sharply in recent sessions and now trade well below their 50-day and 200-day moving averages, with RSI readings in deeply oversold territory. That kind of technical weakness often reflects fears of weaker earnings momentum or a softer freight backdrop. But long-term investors should be careful not to confuse short-term price action with long-term value creation.
The bigger narrative here is that K Line is trying to evolve from a traditional shipping operator into a more diversified maritime and supply-chain platform with technology and decarbonization embedded in the model. If management can execute, the rewards could be substantial: higher returns on capital, more durable earnings and stronger shareholder payouts. For investors willing to think in years rather than quarters, the plan is worth watching closely.
| Entity | Gains | Losses |
|---|---|---|
| K Line | ▲Higher ROE potential | ▼Legacy low-margin model |
| Long-term shareholders | ▲Larger returns and better capital discipline | ▼Short-term rate volatility |
| Customers | ▲More integrated shipping services | ▼Less reliance on pure spot pricing |
| Traditional rivals | ▲Pressure to match strategy | ▼Relative competitiveness if they lag |