First Resources and Keppel Reit are set to draw investor attention in Singapore after two very different developments that speak to one simple theme: cash flows matter more when scrutiny and interest rates are high.
Keppel Reit Buys 51% Stake in Keppel South Central
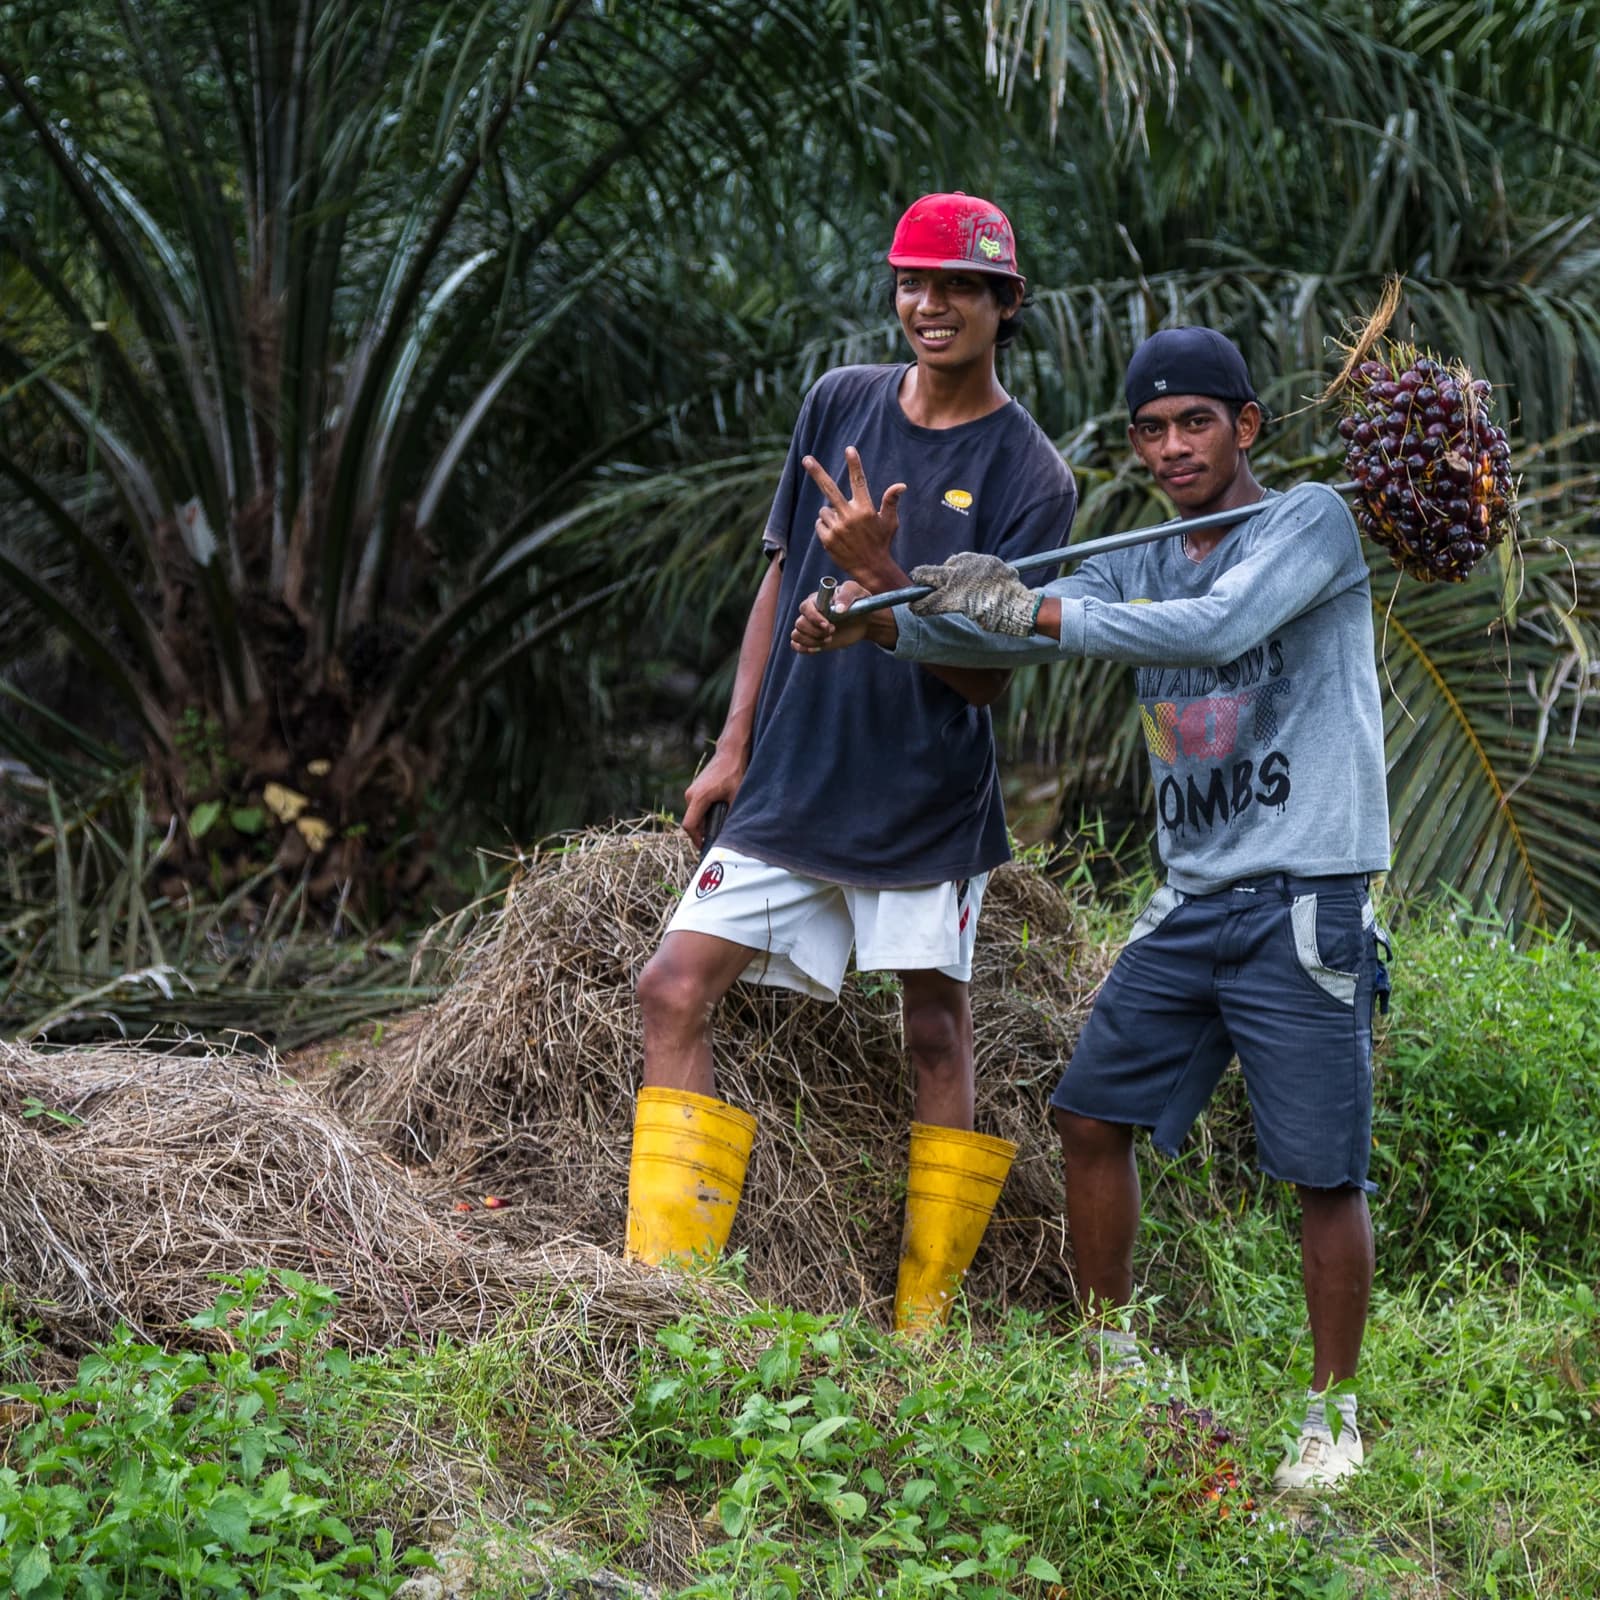
For First Resources, the market will focus on whether the palm oil producer can keep the haze issue from becoming a lasting overhang. The company said it is confident an objective review will show it does not engage in land clearing by fire, and reiterated that it enforces a zero-burning policy across its operations. That matters because environmental allegations can quickly affect a plantation company’s license to operate, access to buyers and, ultimately, valuation. First Resources shares had already been moving higher, closing 3.4% up at S$3.93 on Monday, suggesting investors were willing to give the stock the benefit of the doubt.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 24, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The bigger immediate capital-markets story, though, is Keppel Reit’s acquisition of a 51% stake in Keppel South Central for S$610.9 million. In a market where commercial property owners are still navigating financing costs and weaker risk appetite, the deal gives the trust more exposure to Singapore’s prime office market and comes with a pro forma distribution per unit accretion of 2.01%. A headline initial yield of 4.3% also helps explain why the manager is moving now. Keppel Reit units ended flat at S$0.825 on Monday, but income-focused investors will likely see the transaction as a bid to shore up medium-term distributions.
The broader backdrop is not especially forgiving. Oil prices remain volatile, benchmark U.S. Treasury yields are elevated, and commercial real estate sentiment has been uneven. In that environment, stocks with clearer operating discipline and visible income growth tend to stand out. That is why First Resources’ insistence on a zero-burning policy matters beyond today’s headlines, and why Keppel Reit’s ability to buy a yield-accretive asset from its sponsor will be watched closely.
For investors, the key question is not whether these names will move on Tuesday, but whether they can compound steadily over the next several years. First Resources needs to protect its social and environmental reputation, while Keppel Reit needs to prove it can keep growing distributions without stretching its balance sheet. Both are worth watching, especially for long-term portfolios that prize resilient cash generation over excitement.
| Entity | Gains | Losses |
|---|---|---|
| First Resources | ▲Relief from haze scrutiny | ▼Reputational risk |
| Keppel Reit | ▲Higher income potential | ▼Capital deployment risk |
| Investors | ▲Clearer earnings visibility | ▼Short-term uncertainty |
| Competitors | ▲N/A | ▼Relative attention shift |