Seoul’s market snapped back hard on Wednesday, with the Kospi jumping 3.3% as investors piled back into semiconductor stocks and other Asia tech names after the latest selloff, even as Chinese shares slipped and Hong Kong stayed under pressure.
Kospi rebounds as Asia semis rally on AI demand
The move matters because it shows how quickly the market is refocusing on the AI infrastructure trade. Traders were encouraged by upbeat guidance from Super Micro Computer and stronger revenue from SpaceX, both of which reinforced the idea that demand for AI computing capacity is still running hot. That helped ease a key fear hanging over the sector: that valuations and the massive capital spending needed for data centers may be outrunning returns.
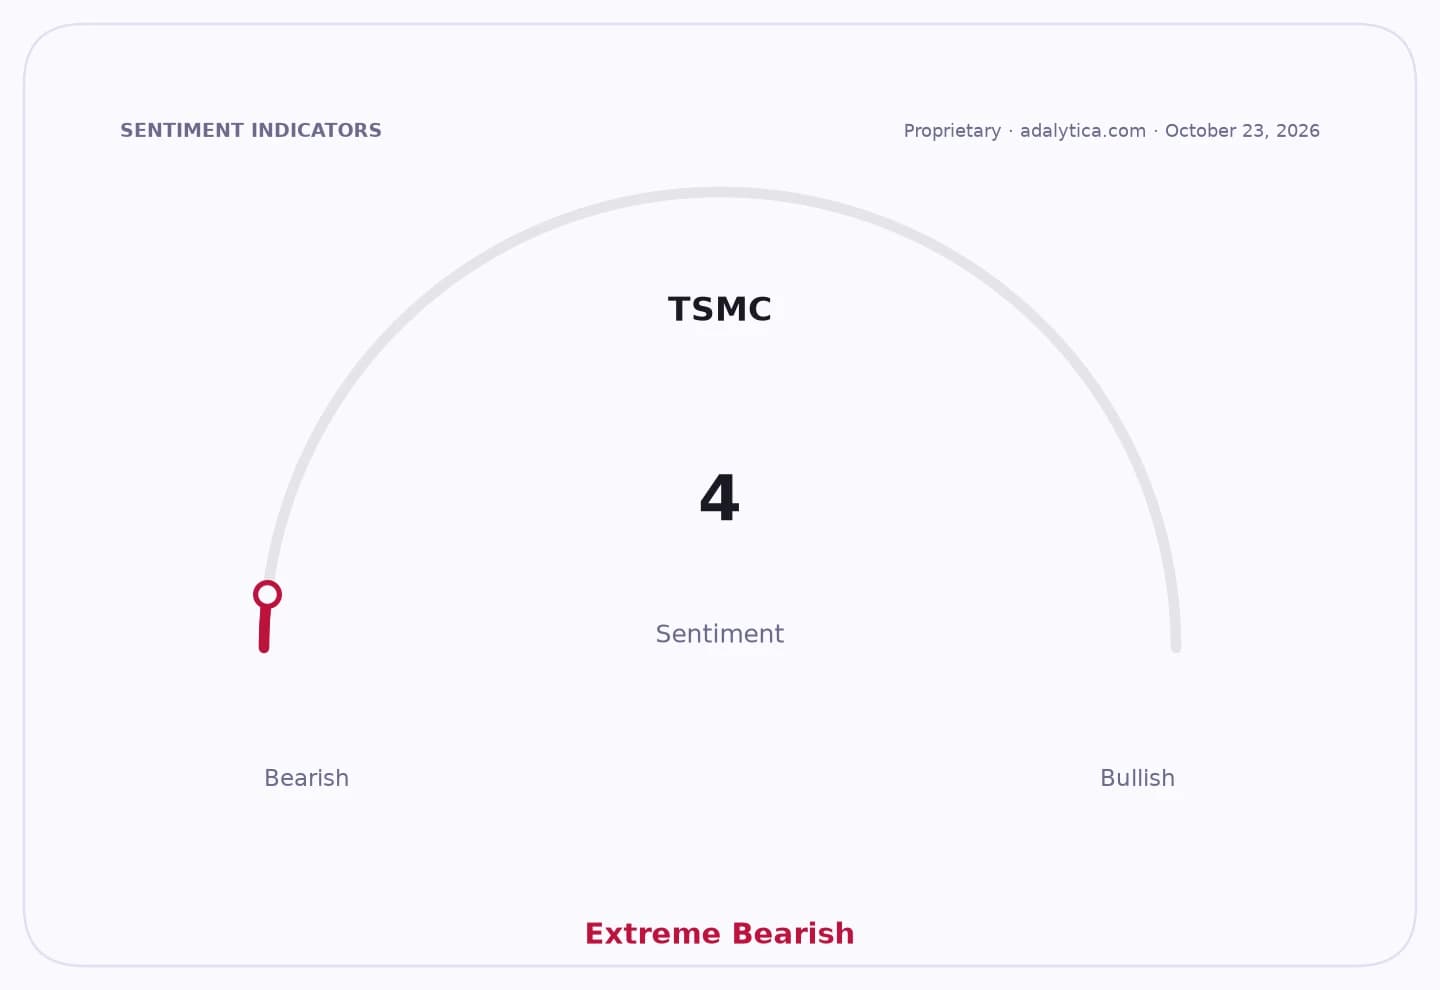
Sentiment IndicatorsⓘProprietary · adalytica.com · October 26, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, the day’s action was a classic rotation within Asia rather than a broad risk-on move. Samsung Electronics surged 5.7% and SK Hynix 5.8% in Seoul, while Advantest and Renesas rose in Tokyo and TSMC edged higher in Taipei. The rebound suggests money is flowing back into the picks-and-shovels names tied to AI buildout, especially after recent pressure had pushed sentiment into oversold territory. In Korea, the 50-day moving average on the broad EWY ETF remains well above spot levels, while the relative strength index has sunk deep into oversold readings, underscoring how sharply the market had corrected before this bounce.
China, by contrast, is still struggling to attract the same enthusiasm. The Shanghai Composite fell 0.6% and the Hang Seng dropped 0.7%, with Tencent down more than 3% and CATL tumbling over 11% after weaker-than-expected results and slower profit growth. That divergence matters: investors are rewarding businesses linked to global AI capex while punishing names exposed to softer domestic growth and a more uncertain earnings backdrop.
There were also pockets of market stress that helped shape the tape. Sydney-based NextDC plunged about 42% after cutting guidance on delays to a Melbourne data center power upgrade, a reminder that AI infrastructure spending only pays off if grids, permits and execution keep pace. Brent crude rose 1.4% to $110.35 a barrel on reports that ships in the Strait of Hormuz had struck mines, adding another layer of geopolitical risk for global markets already sensitive to inflation and energy supply shocks.
The message for investors is straightforward: the AI infrastructure cycle is not over, and the market is still underpricing the second-order winners and losers. Semiconductor makers, equipment suppliers and advanced foundry names remain the clearest beneficiaries if data-center demand keeps accelerating. But Chinese tech and battery names may stay under pressure until growth, margins and policy support improve enough to compete for capital again.
| Entity | Gains | Losses |
|---|---|---|
| Korea semis (Samsung, SK Hynix) | ▲AI demand rebound | ▼Recent sellers |
| Japan/Taiwan chip names | ▲Oversold relief rally | ▼Short-term bears |
| China tech (Tencent, CATL) | ▲— | ▼Earnings and sentiment pressure |
| Data-center plays (NextDC) | ▲— | ▼Execution delays, guidance cuts |