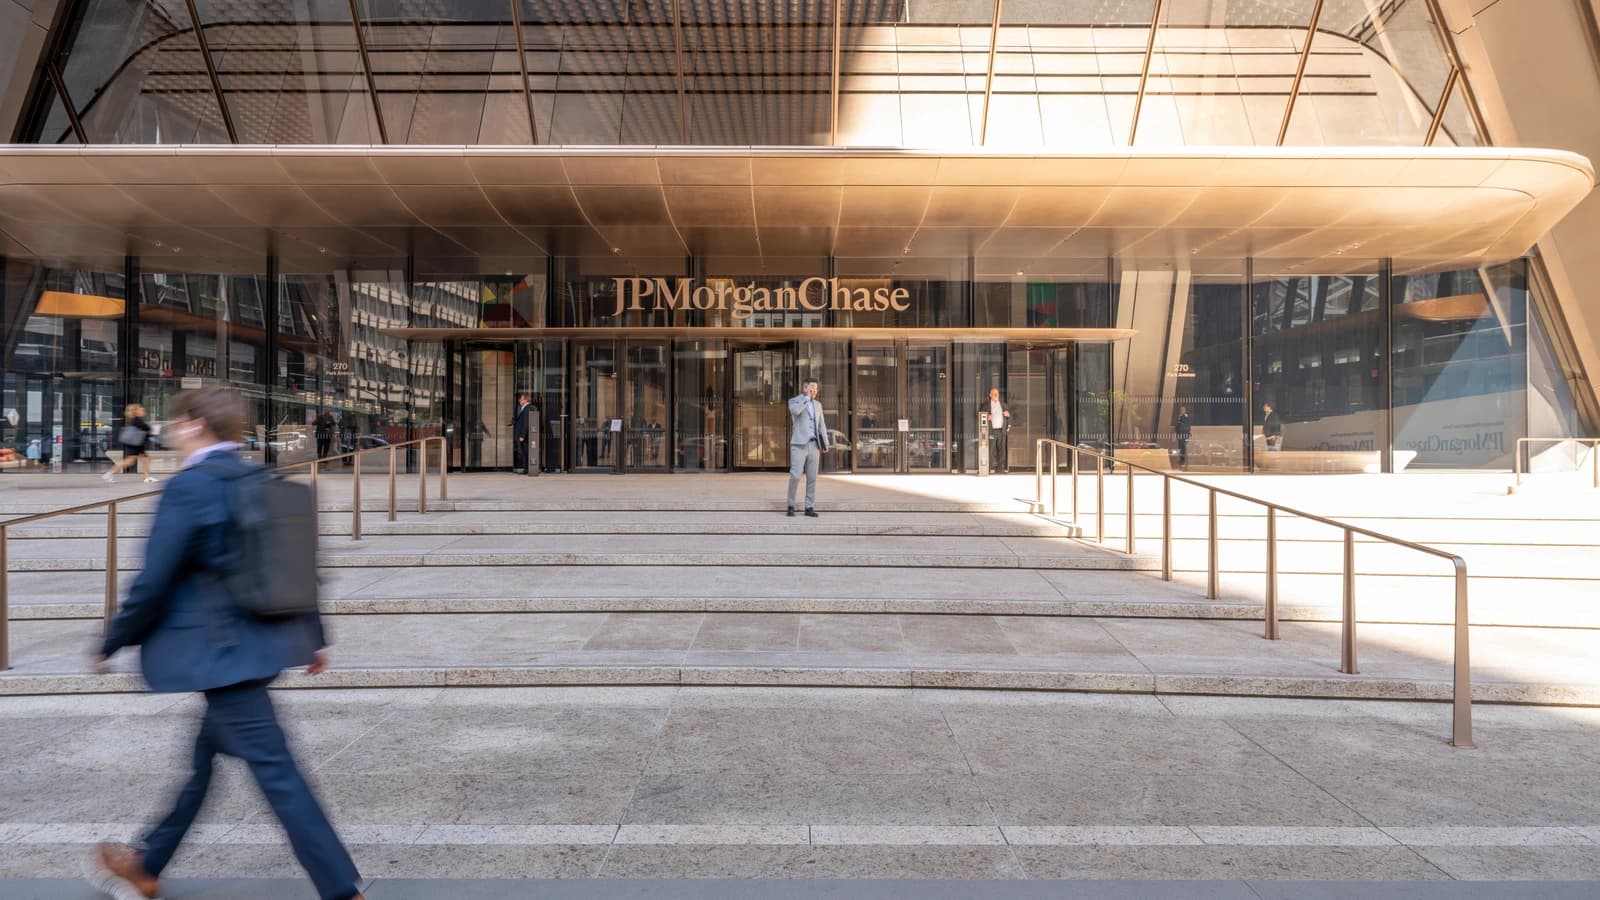
JPMorgan is leading a $4.25 billion financing package for Lantheus Holdings’ acquisition, with Jefferies joining the bank syndicate in a deal that underscores the continued willingness of lenders to fund large leveraged transactions even as broader market sentiment turns cautious.
Lantheus acquisition financing led by JPMorgan
The financing matters because it puts one of the healthcare sector’s more visible specialty-diagnostics companies at the center of a sizeable private-equity-backed transaction, while also testing demand for acquisition debt at a time when credit markets have been uneven. For lenders, the deal is a fee-generating mandate in a market where underwriting and advisory work remains a key profit pool. For investors, it is another sign that financing is still available for strategic takeouts, but only with major banks willing to absorb execution risk and price the debt appropriately.
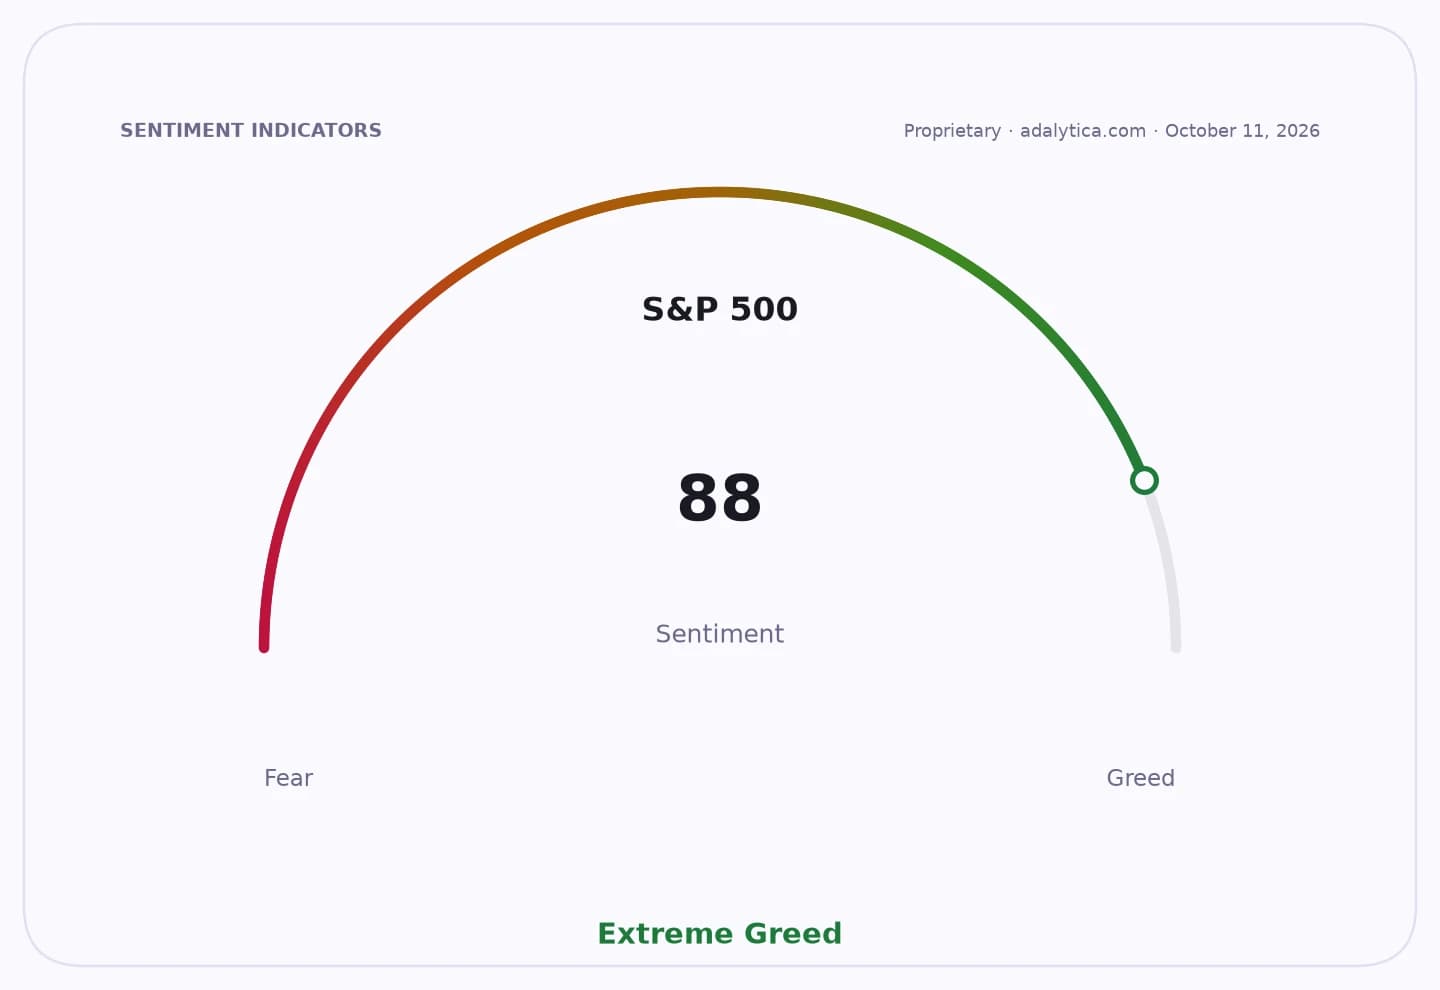
Sentiment IndicatorsⓘProprietary · adalytica.com · October 19, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Lantheus has been one of the better-performing names in the health-care diagnostics space, with the stock rising sharply over the past year and trading around $100 in mid-October, up from the low- to mid-$40s earlier in the year. The move suggests the market had already been anticipating corporate action or some form of balance-sheet event. Technical readings also show the shares near their 50-day moving average and well above the 200-day average, though recent momentum has cooled from overbought levels.
For JPMorgan, the financing highlights the bank’s role as a preferred arranger for large-cap deals, particularly when borrowers need both underwriting capacity and distribution muscle. Jefferies’ participation adds a second-tier capital markets franchise with a growing appetite for advisory and debt work, helping spread the risk and widen the syndication base. Jefferies’ latest filing showed debt underwriting has been softer than equity underwriting, making marquee leveraged-finance assignments especially valuable.
The broader significance is that deal financing is still open for quality assets, even as the S&P 500 backdrop has turned more defensive. Adalytica’s S&P 500 trade signals currently show fear, while the dollar remains in a risk-off posture, conditions that usually make lenders and bond buyers more selective. That makes the Lantheus package notable not just as a company-specific event, but as evidence that top-tier banks can still clear billion-dollar financing when the sponsor and asset profile are strong enough.
Investors will be watching whether the financing prices tightly enough to attract broad demand and whether the transaction closes without pushing leverage into uncomfortable territory. If execution holds, it would reinforce the view that the U.S. leveraged-finance market remains open for large strategic deals. If it struggles, it would be another sign that credit investors are becoming more discriminating even as bankers continue to chase fee-rich mandates.
| Entity | Gains | Losses |
|---|---|---|
| JPMorgan | ▲Fees and league-table credit | ▼Execution and underwriting risk |
| Jefferies | ▲Advisory/financing revenue | ▼Balance-sheet and syndication risk |
| Lantheus shareholders | ▲Takeout premium potential | ▼Loss of future upside if sold |
| Debt investors | ▲Yield on large-cap loan exposure | ▼Credit risk if leverage is heavy |