MARA Holdings is turning to the debt market to fund its push into AI infrastructure, even after using a $1.1 billion Bitcoin sale to shrink leverage and free up collateral. That tension — deleveraging one day, adding new fixed obligations the next — is the most important takeaway for investors because it shows how capital-intensive the race to build data-center and high-performance-computing capacity has become.
MARA Holdings issues $185M notes for AI push
The Bitcoin miner priced $185 million of secured notes at 8.75% that mature in 2032, according to a Tuesday filing with the U.S. Securities and Exchange Commission. The notes are being issued through a U.S. subsidiary tied to MARA’s $1.5 billion acquisition of Long Ridge Energy & Power, an Ohio gas-fired power plant with land MARA says could support more than 1 gigawatt of data-center capacity.
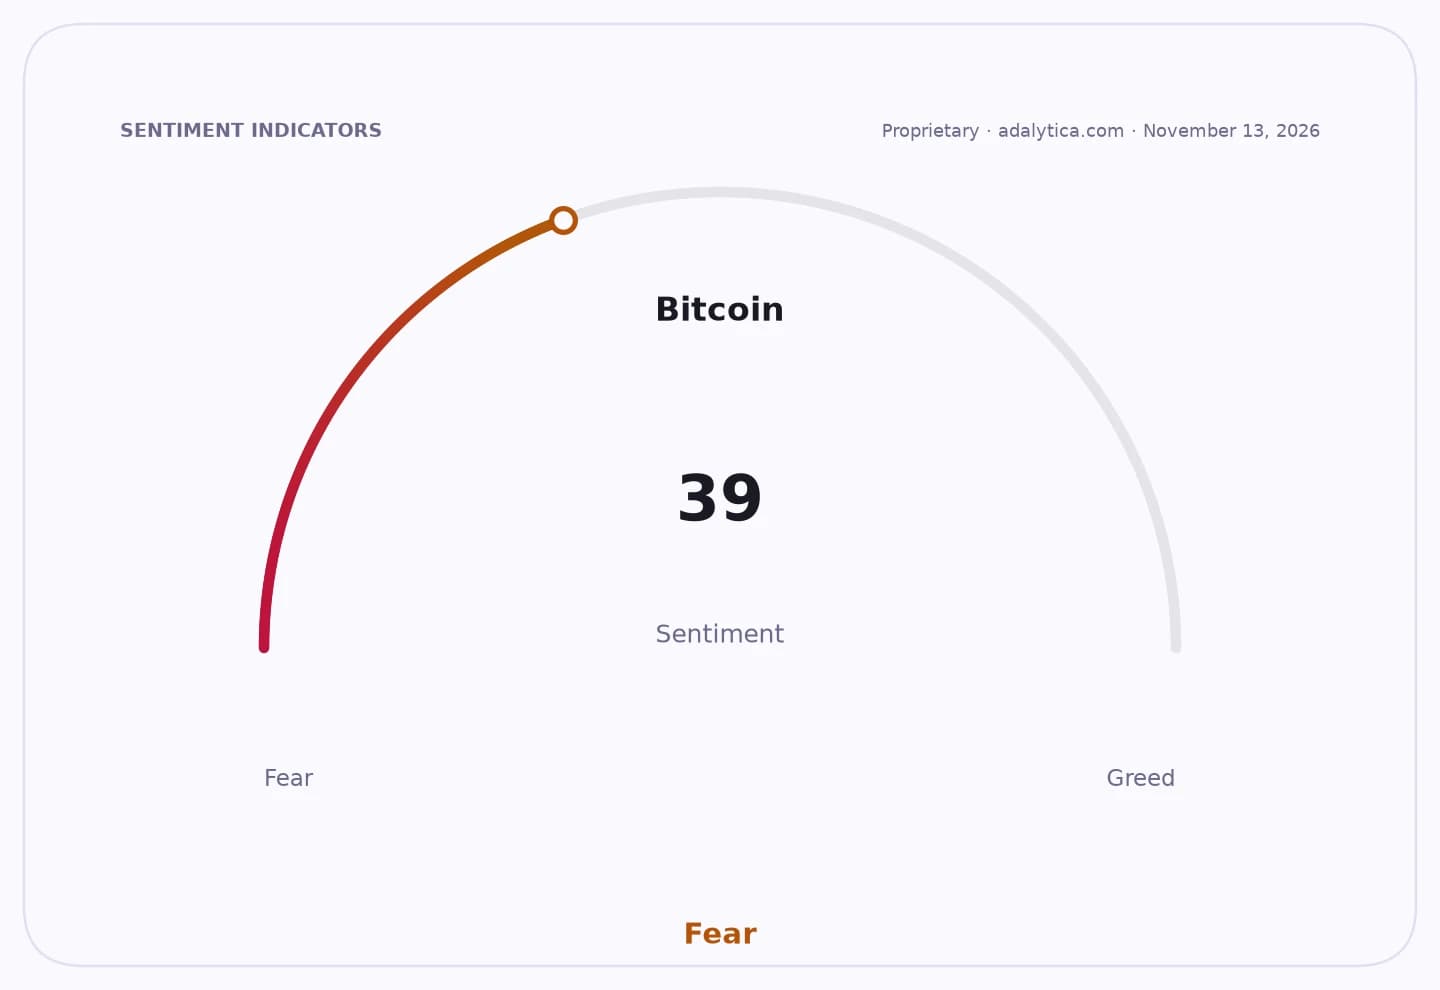
Sentiment Indicators
That acquisition is strategically significant. Bitcoin miners have been trying to reinvent themselves as infrastructure owners that can monetize cheap power, land and grid access for AI workloads. In MARA’s case, the opportunity is real, but so is the cost. The new notes will sit alongside $600 million of existing Long Ridge debt at the same coupon, lifting combined principal to $785 million and annual interest expense to about $68.7 million. MARA said Long Ridge generated about $144 million in annualized adjusted EBITDA in the second half of 2025, which means interest alone could consume nearly half that figure before maintenance, corporate overhead and development spending.
Investors should read that math carefully. A data-center platform with no major AI tenant announced yet is not the same as a fully leased, cash-generating digital infrastructure asset. MARA is effectively buying optionality: a large power site with expansion potential, but one that still needs a customer base and meaningful capital spending to turn promise into durable earnings. That makes execution as important as the headline asset purchase.
The financing comes shortly after MARA disclosed it sold 13,597 Bitcoin after quarter-end for about $1.1 billion, using $750 million of the proceeds to repay Bitcoin-backed loans and release 17,477 pledged coins. Earlier this year, it sold another 15,133 BTC for roughly $1.1 billion and used the cash to help retire convertible debt at a discount. In its latest shareholder letter, MARA said it had cut debt by about $1.4 billion, or 37%, since the start of the year.
That deleveraging matters because it gives MARA more flexibility in a volatile Bitcoin market. Bitcoin prices have fallen sharply in recent weeks, and market sentiment remains weak, with Adalytica’s Bitcoin Fear & Greed Index showing “Extreme Fear.” For miners, weaker coin prices can pressure revenue just as financing needs rise. Selling Bitcoin to pay down debt is a rational move when leverage is high and collateral is expensive. But it also means MARA is replacing crypto exposure with balance-sheet risk tied to real assets and long-dated debt.
The broader industry trend is clear: Bitcoin miners are increasingly behaving like hybrid energy and infrastructure companies. Riot Platforms has also sold Bitcoin to fund data-center expansion, underscoring that this is becoming a sector-wide financing model. The difference is that the winners will be the operators that can convert cheap power and land into contracted AI revenue quickly enough to justify the borrowing.
For long-term investors, MARA’s latest move is neither a simple red flag nor a clean growth story. It is a bet that the value of power infrastructure and AI compute demand will outrun the cost of capital. If MARA secures a strong tenant and keeps leverage under control, the Long Ridge deal could become a meaningful new earnings engine. If not, the company could end up carrying a large debt load for an asset that remains underutilized. Either way, this is a stock worth watching closely rather than chasing blindly.
| Entity | Gains | Losses |
|---|---|---|
| MARA Holdings | ▲AI infrastructure upside | ▼Higher interest burden |
| Long Ridge asset | ▲Funding and development path | ▼No tenant risk |
| Bitcoin holders at MARA | ▲Debt reduction support | ▼Fewer coins on balance sheet |
| Creditors/lenders | ▲Secured 8.75% yield | ▼Exposure to execution risk |