The Mexican peso is coming under renewed pressure just as the dollar’s yield advantage over Mexico starts to fade, a shift that matters because it weakens one of the currency’s strongest supports and leaves the peso more exposed to geopolitical shocks.
Mexican peso falls as U.S.-Mexico rate gap narrows
The dollar was trading around 18.65 pesos on Friday, near its weakest peso level in almost a year, after the Mexican currency slid roughly 1.3% as investors moved toward safer assets amid Middle East tensions and firmer crude prices. That move is important not because it is dramatic in isolation, but because it comes with the policy cushion shrinking: the U.S. 10-year Treasury yield is hovering around 5%, while the federal funds rate has been pushed up to 3.75% in recent months, narrowing the relative carry trade that had helped keep money parked in Mexico.
For investors, that is the key change. The peso has been one of emerging markets’ favorite high-yield trades because Mexico’s rates offered a juicy premium over the U.S. With that spread under pressure, the currency becomes more sensitive to risk aversion, and the recent move shows how quickly that can bite. The dollar’s latest advance has also pushed USDMXN above both its 50-day and 200-day moving averages, a technical sign that momentum has turned against the peso after months of relative stability.
The message for markets is broader than one FX pair. When geopolitical stress rises, investors typically unwind carry trades first, and the peso has become a classic barometer of that behavior. Higher oil prices can help Mexico’s external accounts in the long run, but in the short run they can also amplify global inflation worries and keep U.S. rates elevated for longer, which is a poor combination for a currency whose appeal rests on yield. Banxico’s next moves now matter more: if Mexico cuts too quickly, the peso loses another pillar of support; if it holds rates higher for longer, growth gets squeezed.
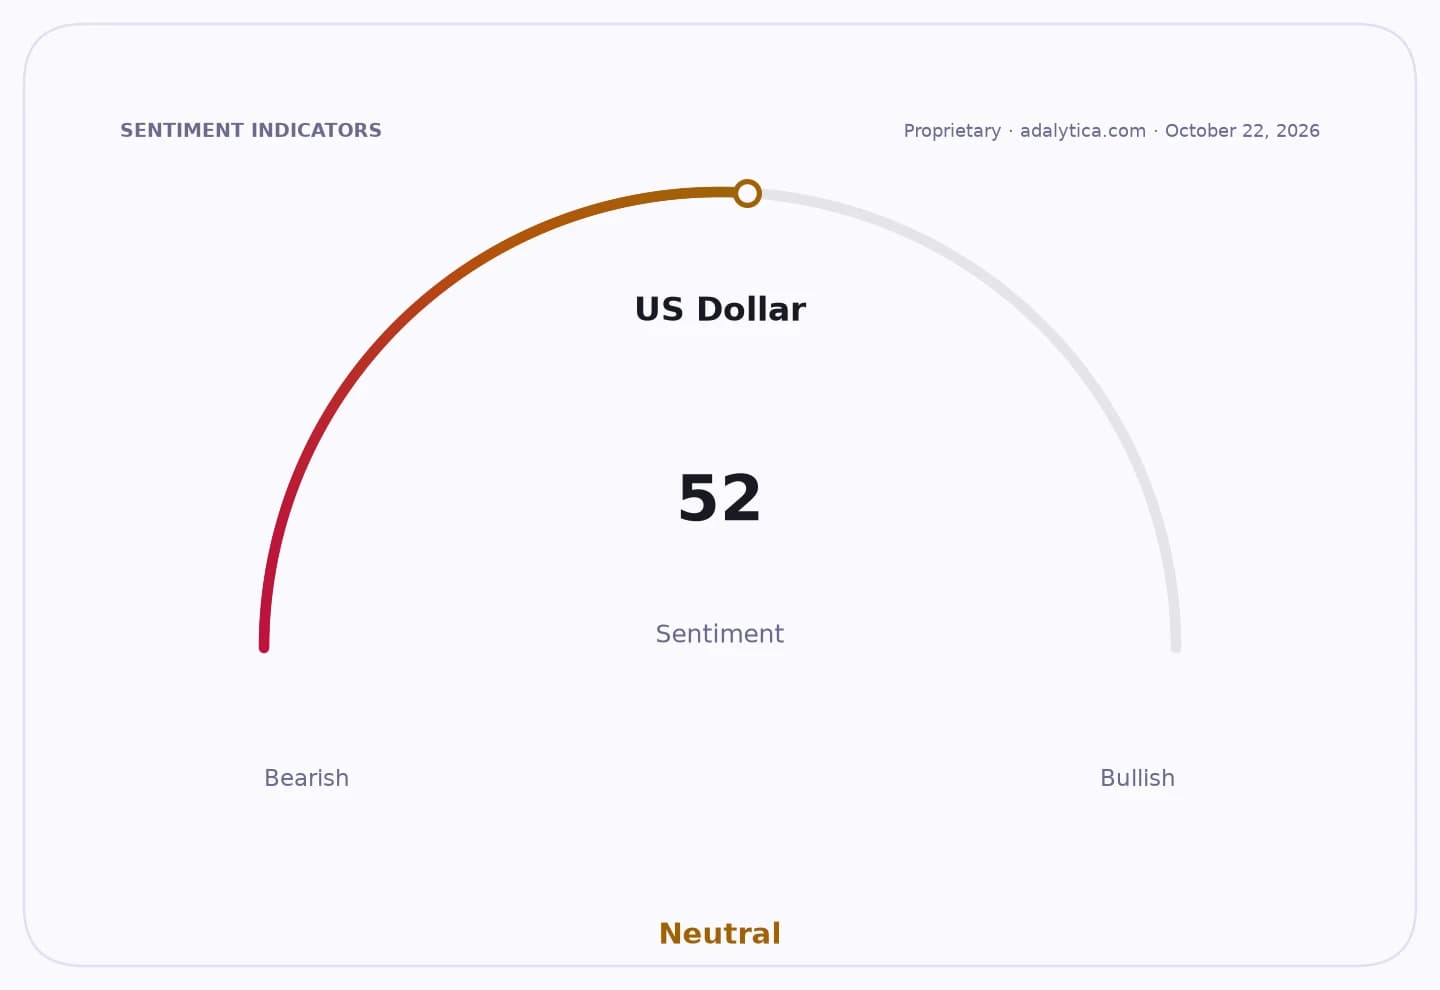
Our view is that the market is underestimating how fragile this setup has become. The peso’s rally story was built on a wide rate advantage and calm global conditions. One of those supports is eroding, and the other is being tested. That leaves room for more upside in the dollar against the peso, especially if risk sentiment stays shaky and U.S. yields remain anchored near 5%.
For investors, the play is straightforward: stay alert to a continued repricing higher in USDMXN and watch Banxico closely, because the next leg in this trade will be driven less by Mexico’s domestic story than by whether the global market keeps rewarding safety over carry.
| Entity | Gains | Losses |
|---|---|---|
| U.S. dollar | ▲Safe-haven demand | ▼None in this move |
| Mexican peso | ▲Lower rates only if growth stabilizes | ▼Carry trade inflows |
| Mexican importers | ▲None | ▼Higher dollar costs |
| Exporters in Mexico | ▲More peso revenue | ▼Imported inflation pressure |