The Mexican peso finished firmer against the dollar on Friday after a weaker-than-expected US jobs report reduced bets on another Federal Reserve rate hike this month, but the currency still logged its steepest weekly loss since March as investors wrestled with inflation and interest-rate uncertainty.
Mexican peso rises after weak US jobs report
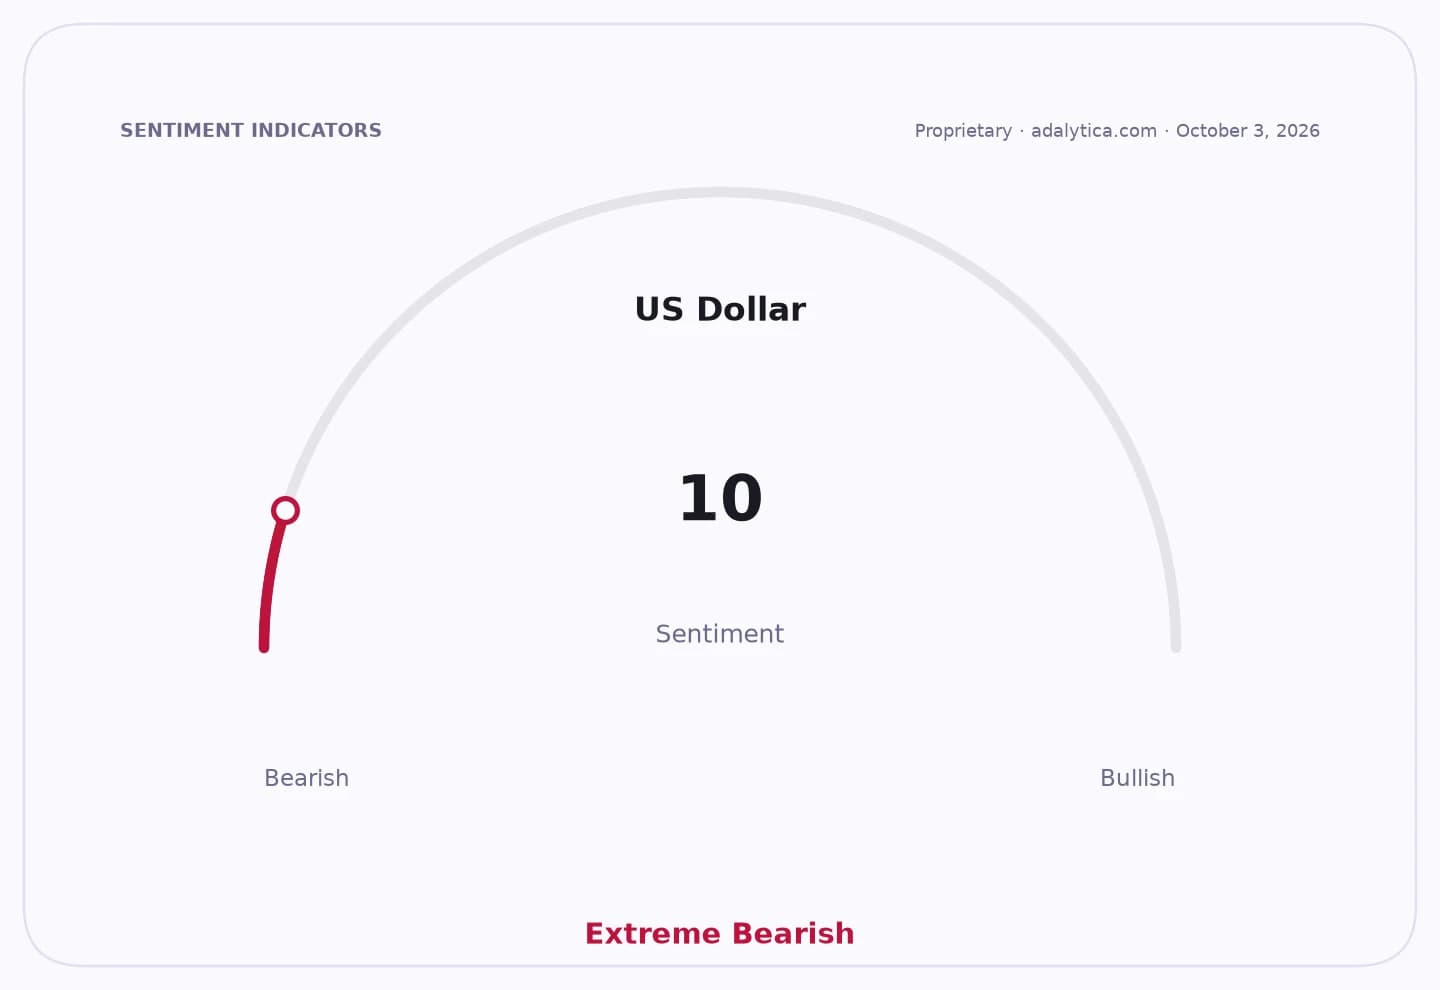
The peso closed at 18.1637 per dollar, strengthening 0.71% from Thursday’s 18.2928, according to Banco de México. It traded between 18.3509 and 18.1103 during the session, while the dollar index slipped 0.21% to 101.89. For the week, however, the peso fell 2.58%, or 45.65 centavos, from 17.7072, underscoring how quickly risk sentiment can reverse even when a single US data point offers relief.
The driver was the US labor market. Nonfarm payrolls rose by just 29,000 in the latest report, far below the 89,000 expected by analysts, while the unemployment rate increased to 4.2% from 4.1%. The figures weakened the case for a second consecutive quarter-point Fed hike, with CME FedWatch pricing only a 20.5% probability of such a move. That pullback in rate expectations eased immediate pressure on the peso, which has been highly sensitive to the US-Mexico yield spread and to shifts in dollar demand.
But the weekly loss shows the bigger force at work remains the dollar’s broad resilience and concern over sticky inflation. A stronger dollar tends to tighten financial conditions for emerging markets, raise the local-currency cost of dollar liabilities and weigh on carry trades that had benefited from Mexico’s relatively high rates. The peso’s decline this week also arrived despite Mexico’s own supportive carry backdrop, highlighting that domestic yield advantages can be overwhelmed when US rates move higher or when investors rush into cash and Treasuries.
For investors, the message is that the peso remains exposed to every turn in the Fed narrative. If incoming US data keep weakening, the dollar could stay under pressure and give the Mexican currency room to recover. But if inflation proves stubborn or policymakers revive talk of further tightening, the peso’s yield advantage may not be enough to prevent renewed selling. That leaves the next batch of Mexican indicators and the market’s interpretation of US growth and inflation data as the key catalysts for direction.
| Entity | Gains | Losses |
|---|---|---|
| Mexican peso | ▲Friday rebound | ▼Weekly performance |
| Dollar bears | ▲Softer payrolls data | ▼Fed-hike bets |
| Dollar bulls | ▲Risk-off week earlier | ▼Near-term rate repricing |
| Mexican exporters | ▲More competitive currency | ▼ |