Analysts in Mexico have lifted their growth forecast for this year for a fourth straight month, but the improvement still comes with a warning: the economy is expected to expand only modestly while inflation remains above Banxico’s 3% target well into the next decade.
Mexico GDP Forecast Raised, Inflation Stays Above Target
The central bank’s latest private-sector survey showed economists now see Mexico’s GDP rising 1.61% in 2026, up from 1.07% pencilled in June and the highest reading since March. For 2027, the forecast was nudged up to 1.86% from 1.77% in the prior survey. The revisions suggest the economy is proving more resilient than many feared, even as businesses remain cautious and domestic demand is not strong enough to generate a faster rebound.
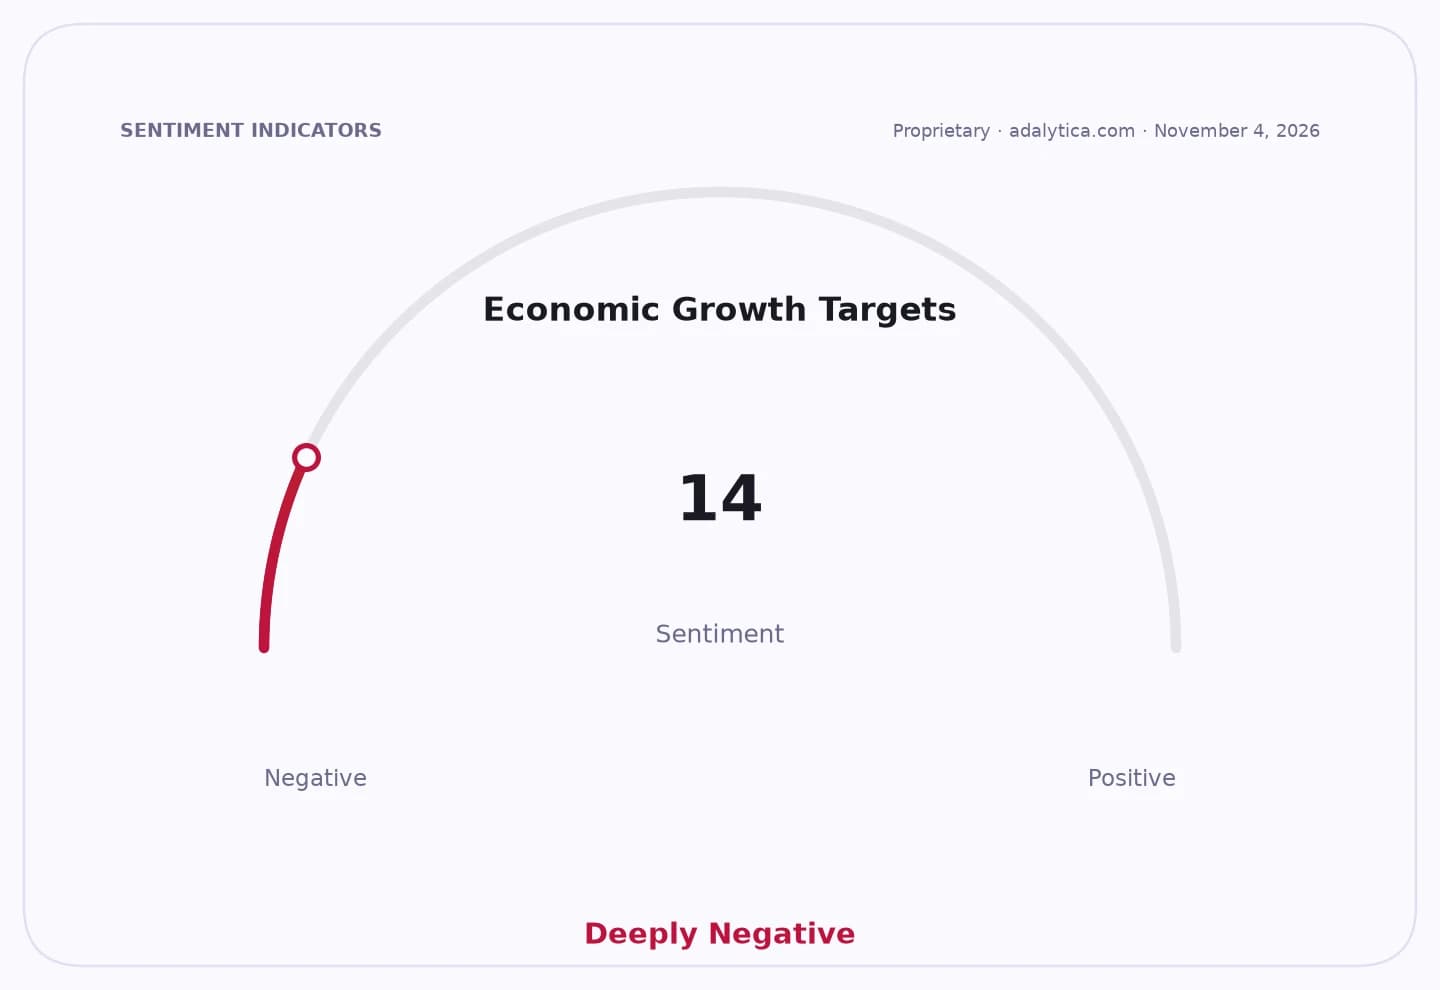
Sentiment Indicators
That matters because Mexico is still growing at a pace that looks closer to stagnation than expansion. A 1.6% gain is better than expected, but it is hardly robust for an economy of Mexico’s size, especially after a stretch of uncertainty around trade policy, public security and the lack of structural reform. The survey also showed 39% of the 42 analysts polled said now is not a good time to invest, underscoring that the private sector has not turned decisively bullish even as it trims recession risk.
The cautious tone is important for investors because it points to uneven support for Mexican assets. Better growth expectations can help sentiment toward equities, the peso and domestic cyclical stocks, but the same survey shows businesses still see the operating environment as fragile. Inflation expectations, meanwhile, remain a separate constraint: analysts now see consumer prices rising 3.83% this year, only marginally below the prior month and still above target. They expect inflation to average 3.85% over the next 12 months, and they do not see it hitting Banxico’s 3% goal even over the next five to eight years.
That combination leaves Banxico with limited room to pivot aggressively. Slower inflation than feared may eventually support rate cuts, but persistent price pressures argue for caution. For markets, the message is that Mexico may be heading for a softer landing rather than a strong growth cycle, with policy easing likely to be gradual and valuation gains in local assets dependent on a more convincing pickup in investment.
The broader backdrop is mixed. A larger share of analysts now expects the business climate to improve over the next six months, while references to public insecurity, trade-policy uncertainty and the absence of structural change remain the main obstacles cited. In other words, the GDP revisions reflect incremental optimism, not a wholesale reassessment of Mexico’s outlook.
| Entity | Gains | Losses |
|---|---|---|
| Mexico economy | ▲Slightly higher growth outlook | ▼Still weak expansion |
| Mexican equities and peso | ▲Better sentiment from forecast upgrades | ▼Limited upside from sticky inflation |
| Banxico | ▲More room to calibrate policy | ▼Pressure to keep rates restrictive |
| Businesses and investors | ▲Improved near-term outlook | ▼Uncertain operating climate |