The bigger story is not that the peso is strong, but that Mexico’s currency has spent the post-pandemic era trading in a completely different regime than the one businesses, households and investors grew up with.
Mexico peso stays below 17 per dollar

If the peso had followed its 1995-to-2020 pattern, it would now be near 37 per dollar. Instead, it was changing hands around 16.86 on Friday, still pinned close to record highs and holding below 17. That gap is more than a quirky statistic. It is a signal that the old playbook for Mexico — steady annual peso erosion, predictable hedging costs and chronic import-price pressure — has been broken, with major consequences for exporters, remittances, inflation and asset allocation.
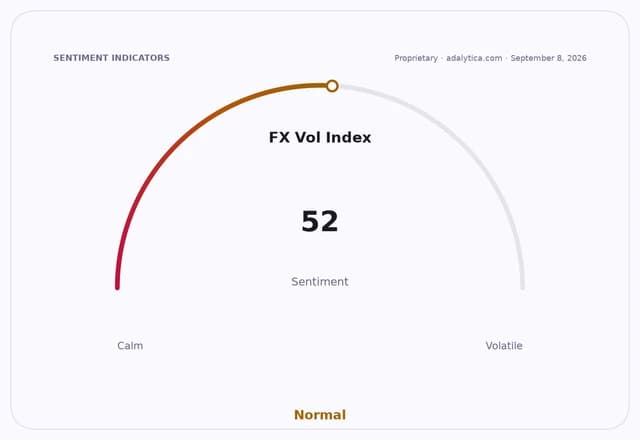
For investors, that regime shift matters because the peso’s strength is not just a currency story; it is an earnings and valuation story. A stronger peso lowers the local-currency cost of imports and helps anchor inflation, which supports Banco de México’s room to ease policy over time. But it also squeezes manufacturers, tourism operators and other peso earners that compete globally, while reducing the peso value of remittance inflows that have already become a central cash source for millions of households.
The latest move is being driven by a weaker dollar as much as by Mexico’s own fundamentals. Expectations around the Federal Reserve have softened the greenback, helped by recent commentary from Fed Governor Christopher Waller and a strong US jobs report, keeping pressure on dollar bulls. That has helped keep the peso in a range that would have looked unrealistic to anyone who lived through the years when annual devaluations of roughly 10% were considered normal.

The market impact is visible in Mexico-linked assets. The iShares MSCI Mexico ETF, EWW, has held above both its 50-day and 200-day moving averages, with its latest close at 76.63, while the iShares China Large-Cap ETF, FXI, has also stabilized after a weaker stretch, reflecting how global capital continues to chase relative value in non-US markets. On the technical side, EWW’s RSI near 60 suggests momentum remains constructive, while FXI’s recovery shows that investors are still rotating among emerging-market exposures rather than abandoning them entirely.
That helps explain why the peso’s strength is so economically important: it is changing who wins and who loses in Mexico. Importers, consumers and companies with dollar-linked costs benefit from cheaper inputs and lower inflation pressure. Exporters, offshore manufacturers and families dependent on remittances lose purchasing power. The Mexican state also faces a subtler trade-off: a stronger currency can ease price pressures, but if it persists too long, it can erode the competitiveness that has drawn manufacturing investment into the country.
This is why the current move should be seen less as a temporary FX rally and more as a structural inflection point. Mexico has gone from a market where currency weakness was the default assumption to one where strength has become durable enough that people are asking the opposite question: why isn’t the peso at 37? The answer is that the old depreciation model no longer holds, and investors who keep pricing Mexico as if it does may be missing the most important macro shift in the region.
The actionable takeaway is straightforward: expect continued opportunity in Mexico’s domestic, import-sensitive and inflation-benefiting sectors, but remain selective on exporters and remittance-exposed names. For broader exposure, EWW remains the cleaner way to express a strong-peso thesis, while FXI’s resilience is a reminder that capital is still rewarding select emerging-market dislocations when the dollar weakens.
| Entity | Gains | Losses |
|---|---|---|
| Mexican consumers | ▲Cheaper imports | ▼Dollar earners |
| Banco de México | ▲Lower inflation pressure | ▼Export competitiveness |
| Importers | ▲Lower input costs | ▼Peso-revenue firms |
| Remittance recipients | ▲Stronger macro stability | ▼Fewer pesos per dollar |