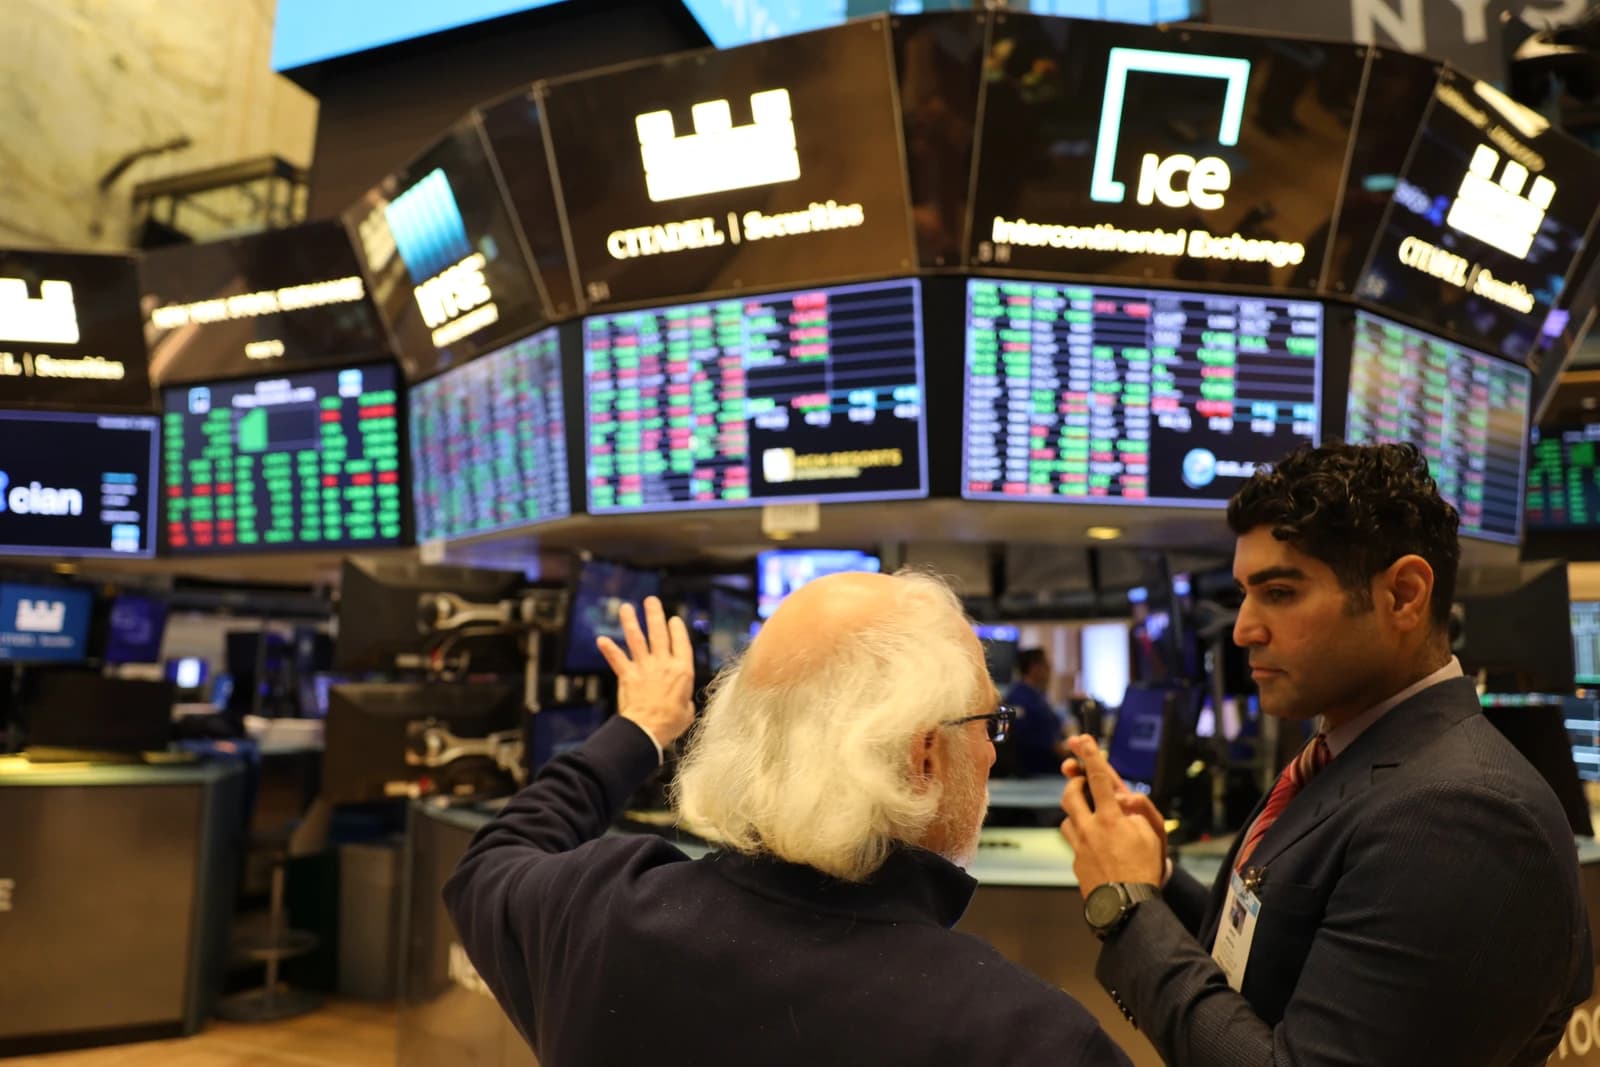
Mexico’s stock market outperformed Wall Street on Friday, extending a two-week rally as US shares slumped on renewed pressure in semiconductor stocks and technology names.
Mexico stocks rise as US tech and chips fall
The benchmark S&P/BMV IPC rose 1.87% to 68,929.72 points, according to the exchange, leaving it up 4.36% for the week and on track for a second straight weekly gain. The move matters because it shows investors rotating toward markets with less direct exposure to the AI-fueled valuation reset hitting US megacaps and chipmakers.
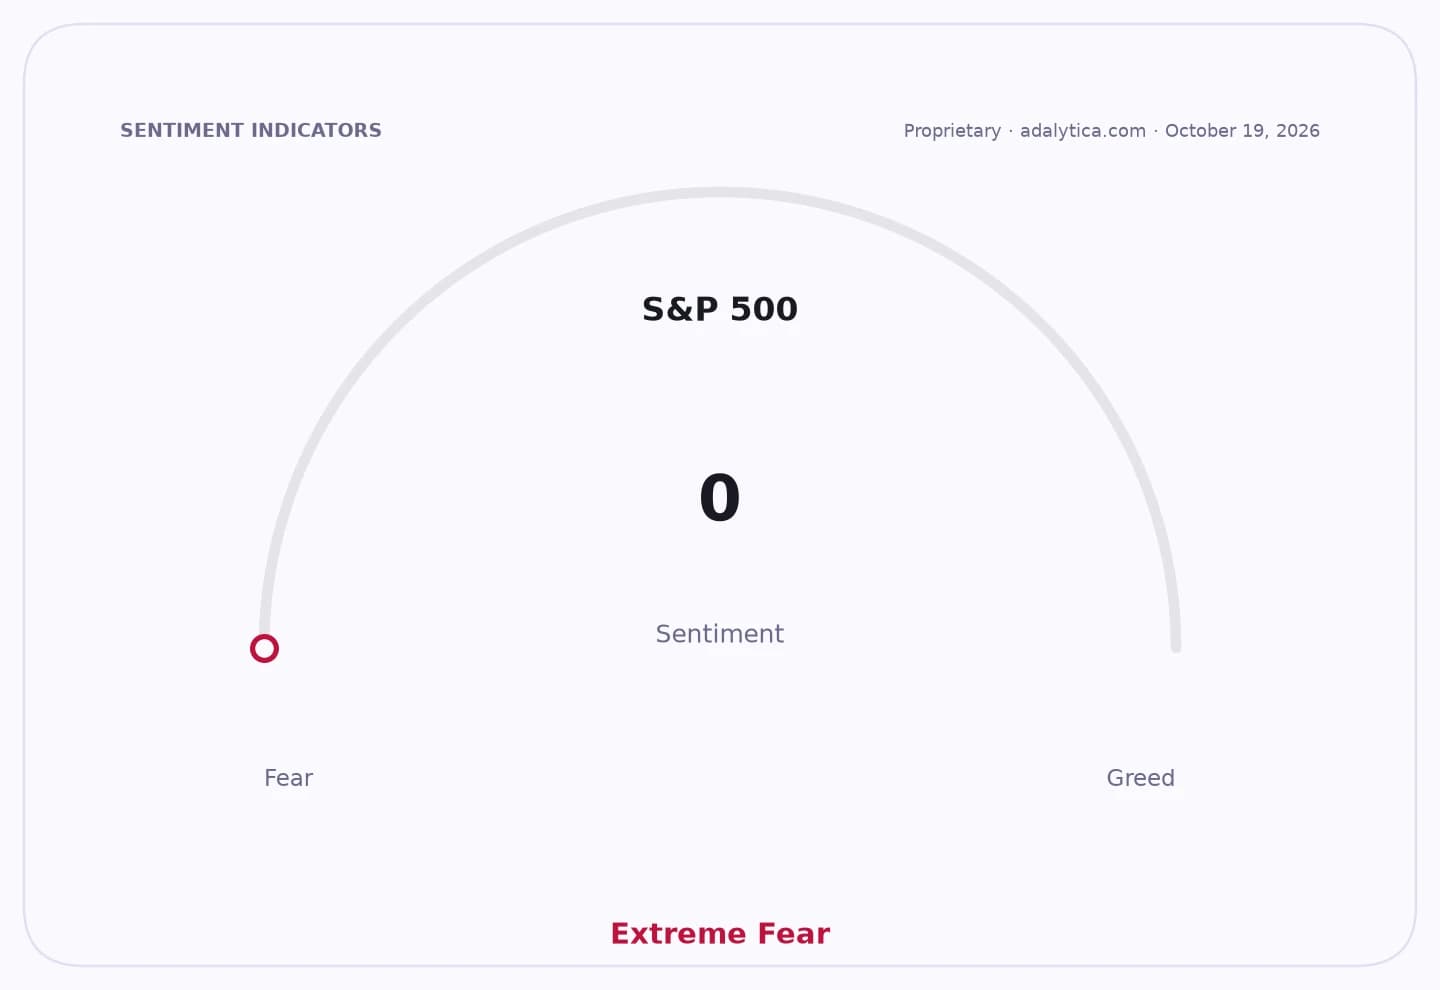
Sentiment IndicatorsⓘProprietary · adalytica.com · October 20, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
By contrast, US equities ended broadly lower. The S&P 500 fell 1.09%, the Nasdaq Composite dropped 2.15% and the Dow Jones Industrial Average slipped 0.34%. The weakness was led by semiconductor makers, as markets grew more uneasy about the debt being taken on to finance artificial-intelligence projects and the pace of progress among Chinese chip rivals.
That divergence left Mexican equities looking relatively defensive. The iShares MSCI Mexico ETF, which tracks large-cap Mexican stocks, rose to $74.94 on Friday after touching $73.88 the prior session, with momentum supported by a rebound in price action after a recent pullback. Its 50-day moving average sat at $74.57, while the relative strength index climbed to 61.5, suggesting the fund was regaining bullish traction but had not yet entered overstretched territory.
The broader US market showed the opposite setup. The SPY ETF tracking the S&P 500 fell to $763.25, with its relative strength index easing to 47.6 and its price slipping below the prior session’s close, a sign that recent gains are being tested as investors reassess risk in the technology complex. Adalytica’s US dollar trade signals remained neutral, pointing to no major currency stress, but the sharp drop in Wall Street sentiment underscores a broader shift out of the most crowded US growth trades.
Oil added another layer to the session. West Texas Intermediate jumped 3.87% to $101.77 a barrel and Brent rose 3.56% to $109.70, helping support energy-linked assets and reinforcing the idea that markets are grappling with a mix of inflation pressure, supply concerns and sector rotation rather than a single macro shock.
For Mexico, the takeaway is that domestic equities can benefit when global investors pull back from expensive US technology exposure. The bull case is that the BMV remains relatively cheap, with improving momentum and some insulation from the semiconductor selloff. The bear case is that the rally could fade if US risk appetite deteriorates further or if higher oil prices feed into broader volatility and tighter financial conditions.
For investors, Friday’s close was less about Mexico-specific data than about relative positioning: when Wall Street’s biggest growth engines stumble, capital can temporarily migrate toward markets offering steadier earnings and lower valuation risk. The next test will be whether Mexican shares can keep outperforming if the correction in US chip stocks deepens.
| Entity | Gains | Losses |
|---|---|---|
| Mexican equities / BMV | ▲Second weekly gain | ▼Global risk-off fades |
| US semiconductor stocks | ▲— | ▼AI debt concerns |
| S&P 500 / Nasdaq | ▲Defensive rotation pressure eases in Mexico | ▼Technology-led selloff |
| Oil producers | ▲Higher crude prices | ▼Refiners and consumers |