The Nasdaq 100 and Brent crude are both pressing higher while USD/JPY is sliding toward a key support zone, reflecting a market shift toward lower U.S. rate expectations, weaker dollar demand and renewed energy-supply risk.
Nasdaq 100, Brent rise as USD/JPY slides
That combination matters for investors because it is helping risk assets and commodities at the same time the yen strengthens and Treasury yields ease. Christopher Waller’s dovish turn pushed traders to cut the implied probability of a September Fed hike to about 50% from 63% a day earlier, while the dollar index drifted toward a four-month low and two-year Treasury yields hovered near 4.34%.
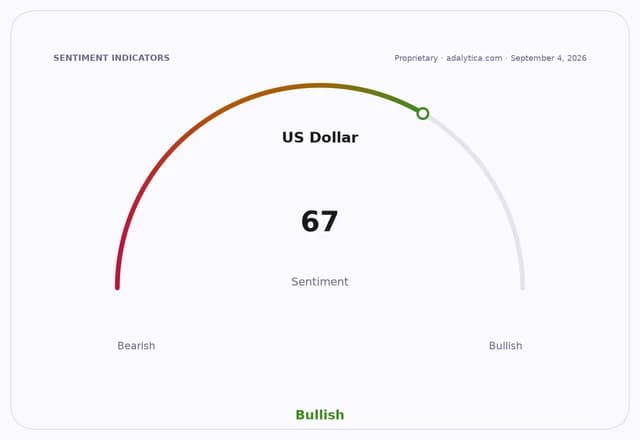
Sentiment IndicatorsⓘProprietary · adalytica.com · September 4, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For equities, the Nasdaq 100 is trying to build on a bounce from this week’s 28,953 low, near the August trough at 28,876. The index is still capped by its August-to-September downtrend line at 29,539, but a break above that level would put last week’s 29,753 high back in view, with 29,947 and 30,196 the next upside markers.
The technical picture has improved only marginally. The index closed at 29,523 on Sept. 4, still below the 29,539 resistance line, with the 50-day moving average at 29,369 offering nearby support. Momentum remains subdued, with RSI readings around 39.7 and MACD only just back above signal, suggesting the rally has room to extend but not much margin for disappointment.
Brent is the clearer winner. The contract has climbed from a late-August $87 low to as high as $99.77 in September, leaving it on track for its biggest weekly gain since July as renewed US-Iran tensions and Strait of Hormuz shipping risks raise supply fears. Brent settled at $95.83 on Sept. 4, still above its 50-day moving average at $86.17 and holding well over its August base.
For oil investors, the next test is the psychological $100 level. A clean break there would open a move toward $101.25, while support sits in the $96.19 to $94.33 area. The move is already filtering into broader inflation expectations at a time when Fed officials are sounding less uniform on the path of rates.
USD/JPY is the main countertrend move. The pair dropped to 156.22 on Sept. 4 after briefly probing below 159 the day before, but the May-to-August lows are still acting as a floor and may trigger another bounce if they hold. A failure at ¥155.03 on a daily closing basis would change the medium-term setup and bring the ¥150 area into focus.
That makes the yen rally more than a short-term currency trade. Stronger expectations for a Bank of Japan hike on Sept. 17-18, combined with intervention fears and softer U.S. yields, are encouraging carry trade unwinds and weighing on the dollar. The result is a market that is still favoring risk assets and crude, but with foreign exchange positioning becoming more fragile.
The next catalyst is the U.S. payrolls report, which could reset Fed expectations again and either extend the Nasdaq and Brent rally or give USD/JPY the bounce it needs from support.
| Entity | Gains | Losses |
|---|---|---|
| Nasdaq 100 bulls | ▲Relief from lower-rate bets | ▼Failure at downtrend resistance |
| Brent crude longs | ▲Supply-risk bid, $100 test | ▼Pullback if $96 support fails |
| Yen bulls | ▲BOJ hike bets, intervention fears | ▼Rebound in USD/JPY if ¥155.03 holds |
| U.S. dollar bulls | ▲Temporary support from yields | ▼Softer Fed path, weaker index |