JPMorgan’s new buy rating on NexGen Energy is the latest sign that uranium equities may be moving from a speculative trade to a mainstream energy bet, with a giant Canadian project at the center of the story.
NexGen Energy Rises on JPMorgan Buy Rating
That matters because the market is increasingly treating nuclear fuel as a strategic commodity, not just a cyclical one. If the bull case for uranium holds, the winners will not be the miners with the best headlines — they will be the developers that can actually deliver new supply into a market where demand is being pulled higher by nuclear restarts, data-center power needs and long-dated energy security concerns.
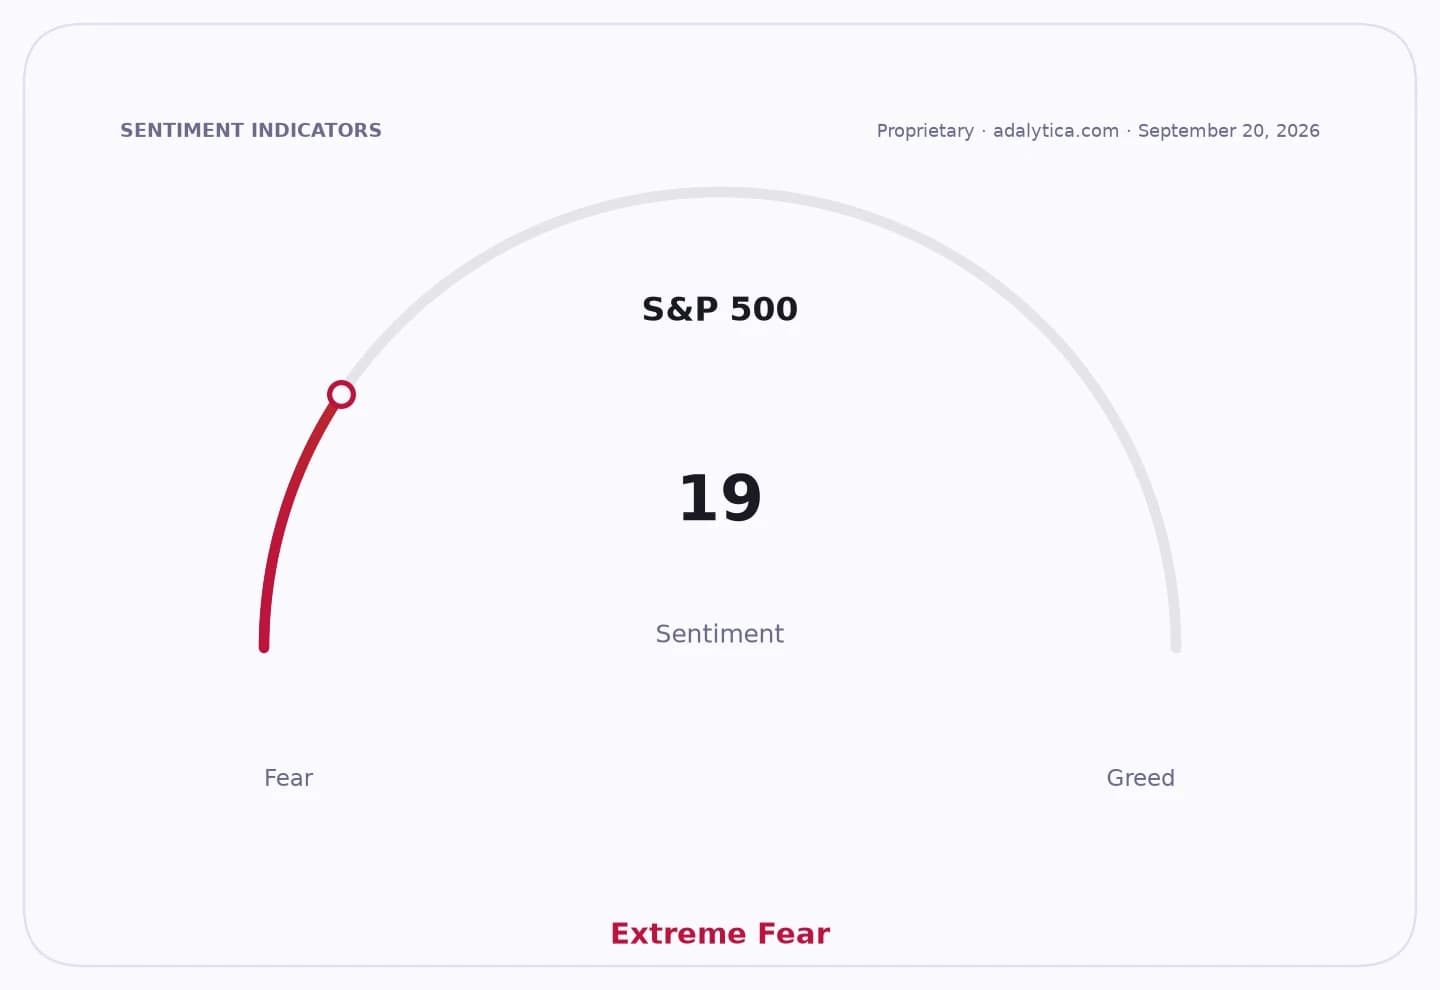
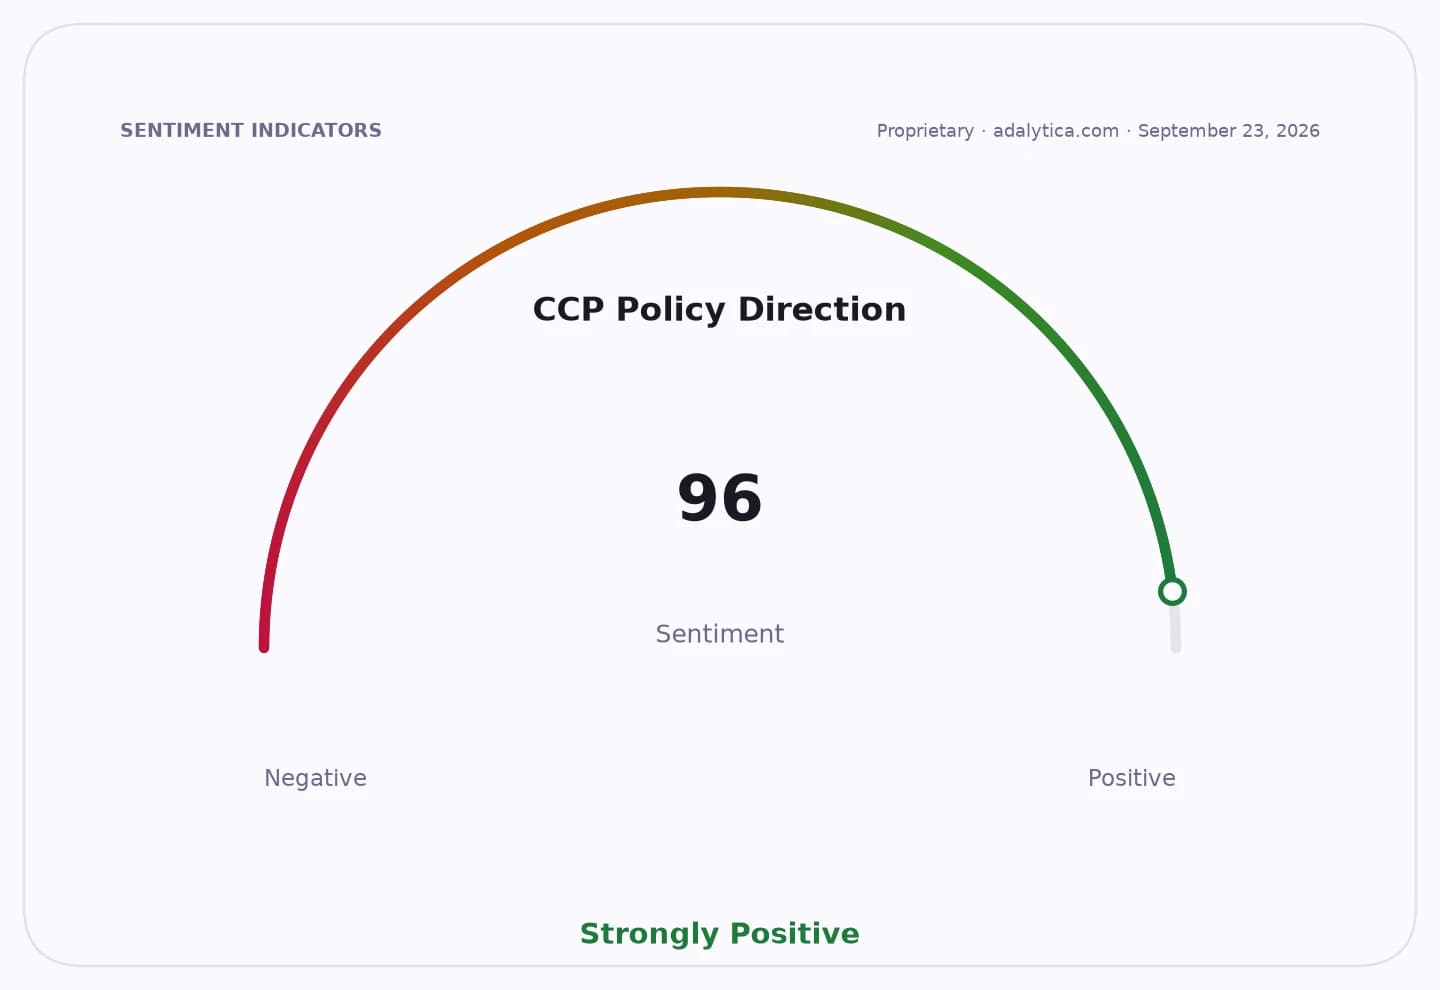
Sentiment IndicatorsⓘProprietary · adalytica.com · September 26, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
JPMorgan initiated coverage on NexGen with an Overweight rating and a $14 price target, implying more than 50% upside from recent levels. The call helped lift the stock as much as 3% on Monday, and it reinforces a broader Wall Street view that NexGen is one of the cleaner ways to play the uranium upcycle. All eight analysts tracked by LSEG rate the shares Buy or Strong Buy, and the consensus target points to more than a doubling from here.
The core of the thesis is NexGen’s Rook I project in Canada, which the company says could eventually produce about 30 million pounds of uranium a year starting around 2030. JPMorgan likes the project’s scale, ore quality and location, arguing that Canada offers a better jurisdictional backdrop than many competing uranium assets. That is exactly the kind of advantage the market tends to underprice early: permitted or near-permitted supply in a geopolitical safe haven is far more valuable when governments and utilities are scrambling to lock in fuel for the next decade.
For investors, the setup is less about chasing an already crowded trade and more about positioning ahead of a supply-response story that may still be underestimated. The uranium sector has already seen sharp bursts of momentum, but the real upside comes if the market starts rewarding developers that can convert higher prices into bankable projects. NexGen sits in that lane, with a large-scale asset that could become a meaningful future source of primary uranium supply.
The broader backdrop is constructive for the whole uranium complex. Oil prices remain elevated enough to keep the energy-security debate alive, while U.S. bond yields near 5.1% and a still-uncertain macro environment reinforce the appeal of long-duration infrastructure themes with strategic importance. Nuclear power fits that profile, and so does the uranium supply chain.
I believe the market is still early in separating the real winners from the rest of the uranium basket. If uranium prices stay firm and project finance remains available, names with high-quality Canadian assets and credible development paths could be the next leg of the trade. For investors looking for leverage to the nuclear buildout, NexGen is one to watch closely.
| Entity | Gains | Losses |
|---|---|---|
| NexGen Energy | ▲Higher valuation, analyst support | ▼Execution and permitting scrutiny |
| Uranium bulls | ▲Momentum and broader re-rating | ▼Missed upside if underweight |
| Canadian uranium developers | ▲Jurisdiction premium | ▼Riskier foreign peers |
| Short sellers | ▲Little immediate support | ▼Squeezed by bullish target calls |