Running is no longer just about fitness — it has become a mass consumer phenomenon, and the money is increasingly flowing to the brands that can turn that obsession into premium product, pricing power and repeat purchases.
Nike, Lululemon, Deckers Tied to Running Boom
That shift matters because the running boom is now a genuine retail and apparel story, not a niche lifestyle trend. As more consumers move from casual jogging to structured training, marathon culture and performance gear, the category is pulling demand toward shoes, apparel and accessories that sit at the intersection of health, identity and status. The market is also rewarding companies tied to that behavior, even as broader consumer spending remains uneven.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 23, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Nike, Lululemon and Deckers are all trading around the same basic message: investors are still trying to sort out which brands can monetize the surge in performance running and which are vulnerable to fashion fatigue, margin pressure or a slowdown in discretionary demand. Nike shares have fallen to about $37.67 from above $63 earlier in the period tracked, leaving the stock below its 200-day moving average and showing the kind of reset that often precedes a bigger product-cycle debate. Lululemon has been cut in half from the highs above $215 to about $100, while Deckers has dropped from a January peak around $119 to $81, even after a sharp earlier rally. Those moves suggest the market is not paying up for execution risk — but it is also not fully pricing in how durable the running boom could be.
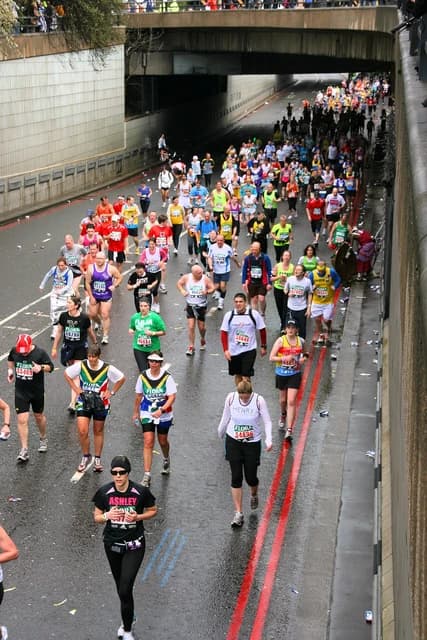
The underlying consumer story is bigger than one shoe cycle. Running has become social, data-driven and aspirational, especially as more people chase half marathons and marathons and build training around performance metrics. That creates a recurring replacement cycle for footwear, higher engagement with premium brands and room for companies to sell not just shoes but a broader athletic wardrobe. In a soft consumer environment, that kind of habit formation is gold: it is less cyclical than fashion, more defensible than commodity sportswear and far easier to scale globally.
For Nike, the opportunity is obvious but the burden is heavier. It remains the category leader, yet the stock’s slide and technical weakness reflect investor doubt that the company can reaccelerate growth quickly enough while managing a product and channel reset. Lululemon has the strongest brand heat in premium athleisure, but its sharp share-price compression shows the market is asking whether it can extend beyond yoga and lifestyle into more durable performance-led demand. Deckers, meanwhile, is the clearest example of a company the market keeps re-rating around product relevance: its footwear franchises can still generate breakout demand when consumers decide a brand is “in.”
That is why running matters as an investment theme. The market often treats it as a consumer fad, but the economics look more durable: higher average selling prices, more frequent replacement, and a long runway tied to wellness, endurance events and the continued elevation of athletic wear in everyday life. If the running boom persists, the winners will be the companies that own performance, fit and community — and the losers will be brands that remain too dependent on broad lifestyle demand.
The next catalyst is simple: product launches, seasonal footwear demand and whether these companies can prove that running is not a spike, but a secular upgrade in consumer behavior. I believe investors should focus on the brands with the strongest product credibility and the most room for a valuation reset higher if the market stops underestimating the category’s staying power.
| Entity | Gains | Losses |
|---|---|---|
| Nike | ▲performance footwear demand | ▼channel and turnaround pressure |
| Lululemon | ▲premium running crossover sales | ▼growth skepticism |
| Deckers | ▲product-led brand momentum | ▼valuation volatility |
| Consumers | ▲better gear and choice | ▼higher prices |