Asian equities were mixed on Tuesday, but Tokyo stood out on the downside, with the Nikkei 225 falling 1.1% as investors looked past Germany’s Alternative for Germany victory and stayed focused on regional market and currency drivers.
Nikkei 225 Falls 1.1% as Asia Trims Risk

The move in Tokyo mattered more than the political noise from Europe because Japan’s market remains one of Asia’s biggest barometers for global risk appetite, exporter earnings and the yen trade. A 1.12% decline in Tokyo came alongside smaller losses in Hong Kong, Mumbai and Seoul, while Shanghai and Shenzhen held marginal gains, underscoring a session defined by rotation rather than a broad selloff.
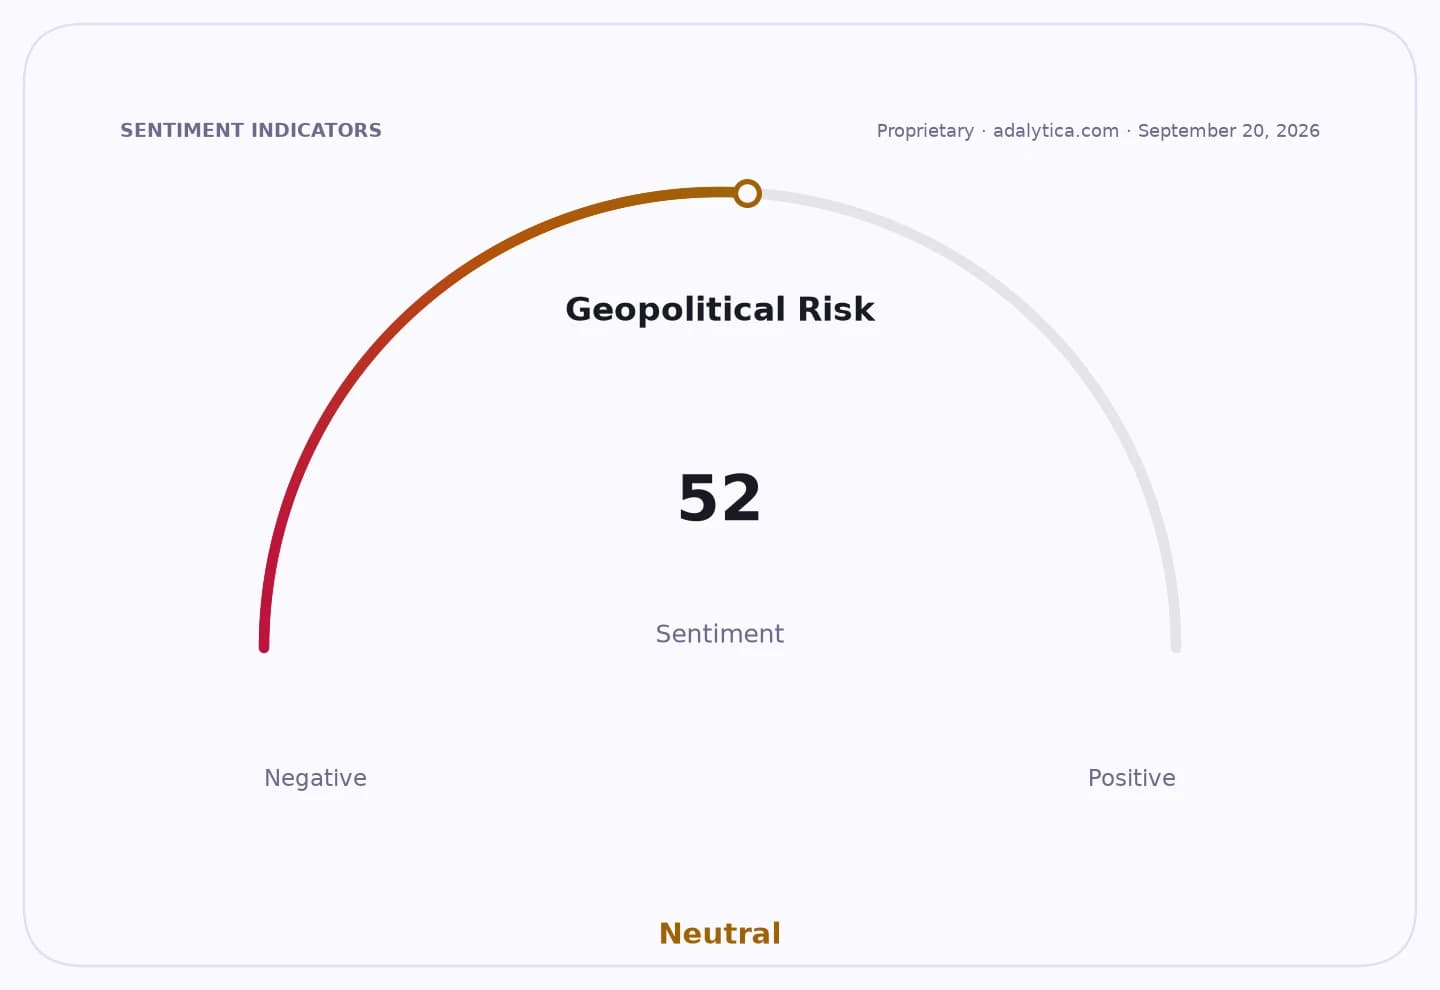
Sentiment IndicatorsⓘProprietary · adalytica.com · September 8, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
For investors, the key issue is that Japan is still trading near recent highs after a strong run in exchange-traded funds and the Nikkei, leaving it vulnerable to profit-taking. EWJ, the iShares MSCI Japan ETF, closed at 98.25 on the latest reading, well above its 50-day and 200-day moving averages, but its relative strength index at 69.1 points to a market that has been extended. That leaves room for a pullback even without a major macro shock.
The broader Asian picture was similarly uneven. The Hong Kong Hang Seng was down 0.34%, Mumbai’s Nifty 50 slipped 0.45% and Seoul lost 0.20%, while mainland Chinese markets were slightly firmer, with Shanghai up 0.12% and Shenzhen off 0.20%. The mixed tape suggests traders are still discriminating between domestic cycles, valuation levels and sensitivity to the dollar, rather than moving as a single regional bloc.
That is why the AfD’s latest electoral success in Germany did not move Asia much, at least for now. The event may matter for European politics and eventually for German fiscal or coalition dynamics, but it is not an immediate driver of earnings expectations, rates or capital flows in Tokyo, Shanghai or Hong Kong. By contrast, the dominant forces for Asian equities remain U.S. rate expectations, the dollar and local policy settings.
The stronger dollar backdrop remains relevant for the region. Adalytica’s U.S. dollar trade signals show greed at 76, with the 30-day change still elevated, a setup that can pressure Asian currencies and export-sensitive markets if it persists. At the same time, Adalytica’s S&P 500 signal is in extreme fear, suggesting global risk appetite remains fragile even if U.S. stocks have not entered a full corrective phase.
China’s equity gauges are providing some support but not enough to change the regional tone. FXI, the China large-cap ETF, has recently held above both its 50-day and 200-day moving averages, with a rising RSI above 50, indicating improving momentum. AAXJ, the broader Asia ex-Japan ETF, has also been firmer, but the day-to-day action still points to selective buying rather than a conviction bid.
For now, the market narrative is straightforward: investors are trading Asia on fundamentals and positioning, not geopolitics from abroad. Tokyo’s decline is the most important move because it reflects how quickly a crowded trade can unwind, even while the region as a whole remains broadly supported by still-resilient Chinese indices and a softer risk tone elsewhere. The next test will be whether Japan’s pullback remains a routine consolidation or turns into a wider de-risking across Asia if the dollar stays firm and global sentiment deteriorates further.
| Entity | Gains | Losses |
|---|---|---|
| Shanghai/Shenzhen | ▲Slight inflows | ▼Broader Asia caution |
| Tokyo Nikkei 225 | ▲None | ▼Profit-taking |
| Exporters in Japan | ▲Weaker yen support | ▼Equity de-rating |
| Traders in China | ▲Relative resilience | ▼Regional volatility |