Nscale’s decision to leave ByteDance unnamed in its $35 billion IPO filing puts a spotlight on the hardest problem in the AI infrastructure trade: how much of the boom is real, recurring demand, and how much is customer concentration wrapped in geopolitical risk.
Nscale IPO Filing Leaves Out ByteDance
That matters because the AI buildout has become one of the market’s biggest capital-allocation stories, with investors treating cloud and compute providers as the toll roads of the next technology cycle. But when the largest customer is a Chinese tech giant that is sensitive politically and commercially, the revenue stream becomes harder to underwrite, not easier. For public-market investors, disclosure is not a footnote here — it is the difference between a scalable infrastructure platform and a business leaning on one opaque, potentially volatile client.
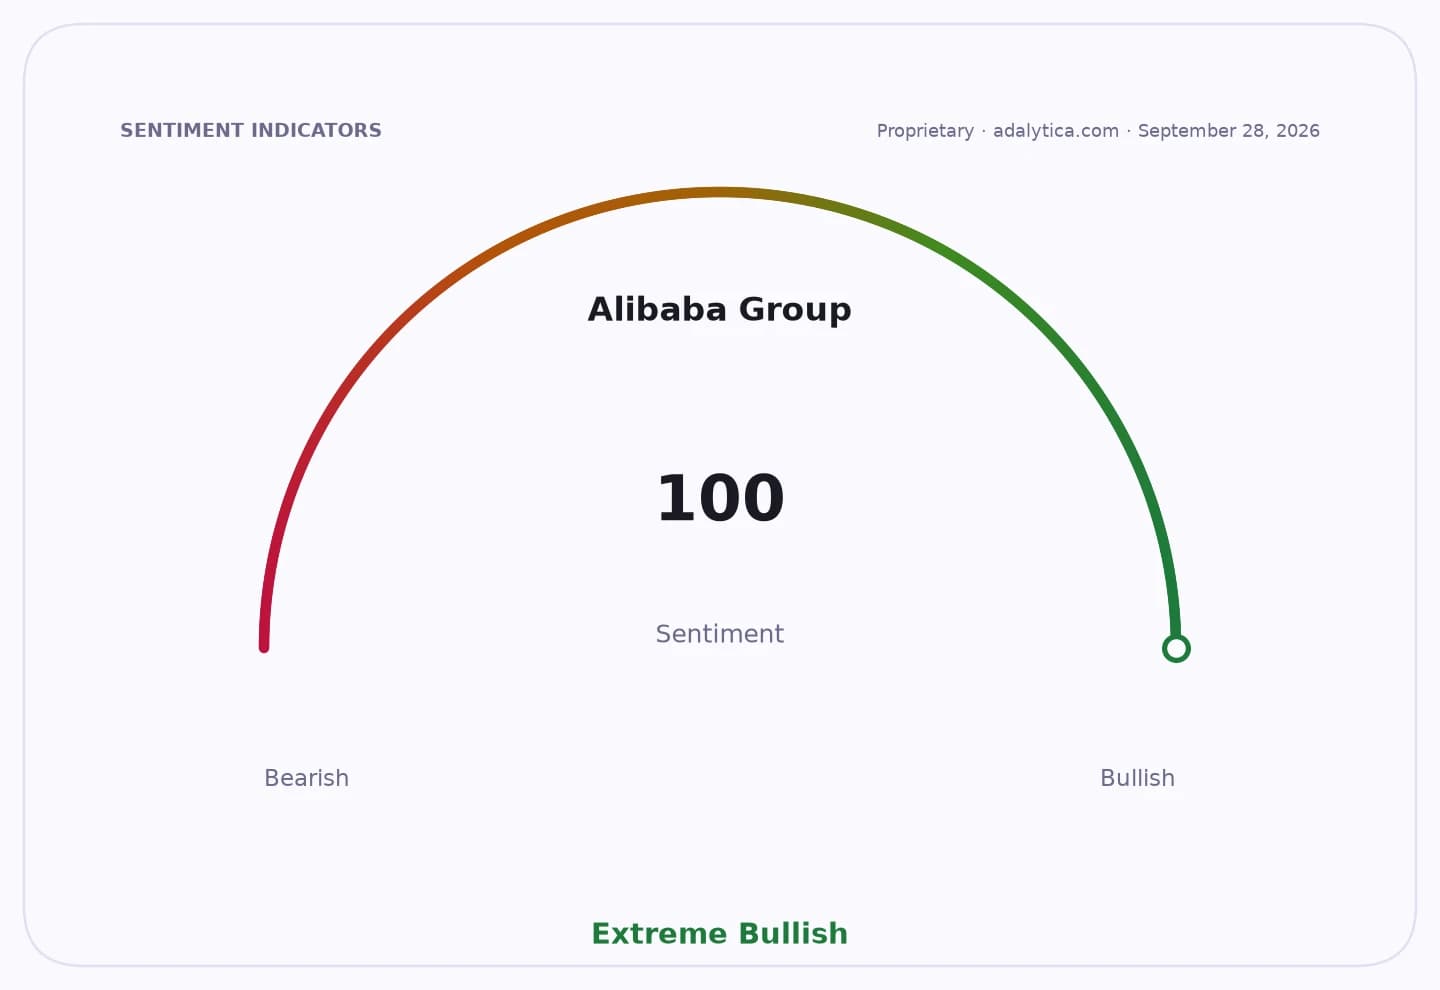
Sentiment IndicatorsⓘProprietary · adalytica.com · September 28, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The omission is especially notable because ByteDance was Nscale’s biggest customer last year, according to the seed filing context, yet it is not prominently named in the pitch to stock market investors. That kind of selective presentation can change how the IPO is valued. A company selling itself as an AI cloud provider wants to be compared with the picks-and-shovels winners of the AI capex cycle. But if a meaningful slice of demand depends on one overseas customer, particularly one tied to Chinese tech and US-China strategic friction, the market may demand a discount for concentration, counterparty and regulatory risk.
This is the real investment issue: AI infrastructure spending is still accelerating, but investors are getting more selective about who deserves the premium multiple. The market has already shown it will pay up for companies with diversified enterprise demand, durable contracts and clear visibility into capacity monetization. It is far less forgiving when growth depends on a single anchor customer whose presence must be inferred rather than clearly marketed. That can compress demand for the IPO, cap valuation and force a wider spread between the sector’s winners and the names most exposed to hidden concentration.
The broader backdrop is not helping. IPO markets remain uneven, with other listings facing scrutiny, delays and governance questions, while investors are already parsing whether the current wave of AI spending is broad-based or still too concentrated in a few hyperscale and frontier-AI customers. The SPY sentiment gauge showing extreme greed underscores a market willing to chase the theme, but that is precisely when disclosure risk can matter most: euphoric capital tends to punish surprises later.
For investors, the message is straightforward. The AI infrastructure trade is still alive, but the next leg of returns will likely come from companies that can prove diversified demand, not just headline growth. If Nscale’s customer mix is as concentrated as the filing implies, the IPO may end up testing whether the market is still willing to buy the AI buildout story at any price — or whether it now wants cleaner revenue visibility before paying up.
| Entity | Gains | Losses |
|---|---|---|
| Nscale | ▲IPO proceeds | ▼valuation if concentration is discounted |
| ByteDance | ▲secure AI compute access | ▼public attention and geopolitical scrutiny |
| AI infrastructure peers | ▲sector read-through demand | ▼if investors apply a broader risk discount |
| IPO investors | ▲exposure to AI capex theme | ▼if customer concentration proves material |