Nvidia remains the clearest long-term winner in the market’s AI spending boom, but the bigger message from this group of “final trades” is that investors are still paying up for companies tied to durable growth stories rather than short-term macro noise.
Nvidia, Okta, Cognex and Delta after sharp rallies
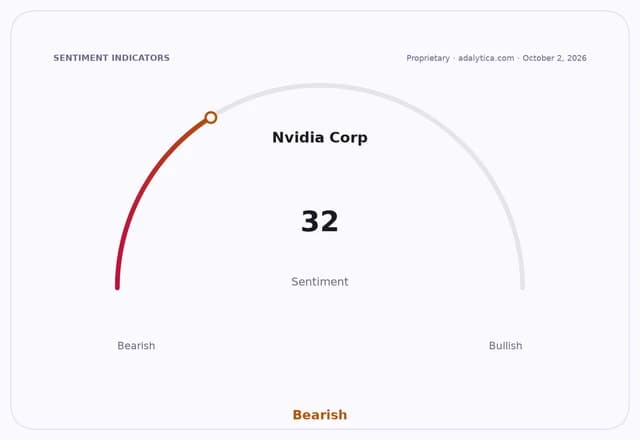
That matters because the market is still rewarding businesses with real pricing power, recurring demand and improving earnings visibility. Nvidia’s shares closed at $233.95 on Oct. 2, well above their 50-day moving average of $218.12 and 200-day average of $200.38, with RSI readings at 83 showing the stock is extended after a powerful run. Even so, the broader setup remains bullish: the chipmaker is still the anchor of AI infrastructure spending, and its long-term case is driven by data center demand, not day-to-day sentiment swings.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 2, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The same preference for quality growth explains why Okta, Cognex and Delta remain in the conversation. Okta has staged a dramatic rerating, climbing to $211.49 from a $164.75 50-day average and a $112.14 200-day average. That kind of move tells you investors are no longer treating it like a fragile cybersecurity turnaround, but as a subscription software business with a clearer path to compounding revenue and cash flow. For patient investors, the question is not whether the stock can keep rising every week. It is whether identity security stays mission-critical for years. The answer still looks like yes.
Cognex, meanwhile, is more of a cyclical beneficiary, but it is exactly the sort of industrial automation name long-term investors should keep on a shortlist. The machine-vision specialist rebounded to $64.97 from recent lows near $57.74, and it remains above both its 50-day and 200-day moving averages. As factories keep automating and manufacturers push harder on efficiency, Cognex has exposure to a secular trend that is bigger than any one quarter.
Delta Air Lines is the value-and-cash-flow name in the group, and it offers a different kind of appeal. Airlines are still cyclical, but Delta has repeatedly shown that premium demand, loyalty revenue and disciplined capacity can produce stronger economics than the industry used to deliver. In a market that has become more selective, that matters. Investors do not need to chase every airline, but Delta remains one of the better ways to own travel demand with a business model that is more resilient than most.
The broader investment lesson is simple: the market is still putting a premium on companies that can grow through multiple cycles. Nvidia is the purest AI play. Okta is a recurring-revenue software story. Cognex gives investors industrial automation exposure. Delta offers cash generation and premium travel demand. None of them should be bought blindly, especially after sharp rallies, but all four fit a long-term portfolio built around secular growth, diversification and patience.
If you are investing for the next 3 to 10 years, not the next 3 to 10 days, these names are worth watching closely. The best returns usually come from businesses that keep earning the market’s trust, not from trying to time the next pullback.
| Entity | Gains | Losses |
|---|---|---|
| Nvidia | ▲AI infrastructure demand | ▼Short sellers |
| Okta | ▲Identity security adoption | ▼Skeptics of the rerating |
| Cognex | ▲Factory automation spending | ▼Cyclical industrial bears |
| Delta Air Lines | ▲Premium travel and cash flow | ▼Complacent airline rivals |