Nvidia’s march to a record high has put a $6 trillion valuation within sight, underscoring just how dominant the chipmaker remains even as AMD moves aggressively to expand AI-chip supply through 2027.
Nvidia Hits Record as AI Demand Stays Strong
That matters because the AI buildout is no longer just a story about who has the fastest chips — it is becoming a story about who can secure the most lasting economic value from the infrastructure layer powering the boom. Nvidia is still capturing the market’s confidence, and the latest rally suggests investors see its moat in software, systems and customer lock-in as more powerful than the growing competition.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 7, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
Shares of Nvidia hit a fresh record on Monday, extending a run that has left the stock well above its 50-day moving average and near the upper end of its recent trading bands. The stock closed at $239.24 in the data provided, after touching an intraday high of $243.37, while momentum readings showed the name deep in overbought territory. That kind of strength is exactly why the company has become the face of the AI trade, but it also explains why skeptics are warning that the stock could be vulnerable to a sharp correction if enthusiasm cools.
Even so, the bigger long-term message is constructive for investors. Nvidia is still the company that most directly monetizes the explosion in AI spending, and the scale of its business keeps widening. Its latest filing showed supply and capacity commitments had surged to $279 billion from $119 billion the prior quarter, a striking signal that customers are still locking in access to its chips and systems well ahead of delivery. In other words, demand is not just strong — it is being booked far into the future.
That is the key reason AMD’s offensive does not automatically change the narrative. AMD is clearly making a serious push, including partnerships with 14 South Korean AI chipmakers and plans to lift chip shipments materially by 2027. For the broader semiconductor market, that is healthy: more supply, more competition and more investment across the AI ecosystem. But for Nvidia, the near-term effect is more likely to be pressure at the margin than an immediate threat to its leadership.
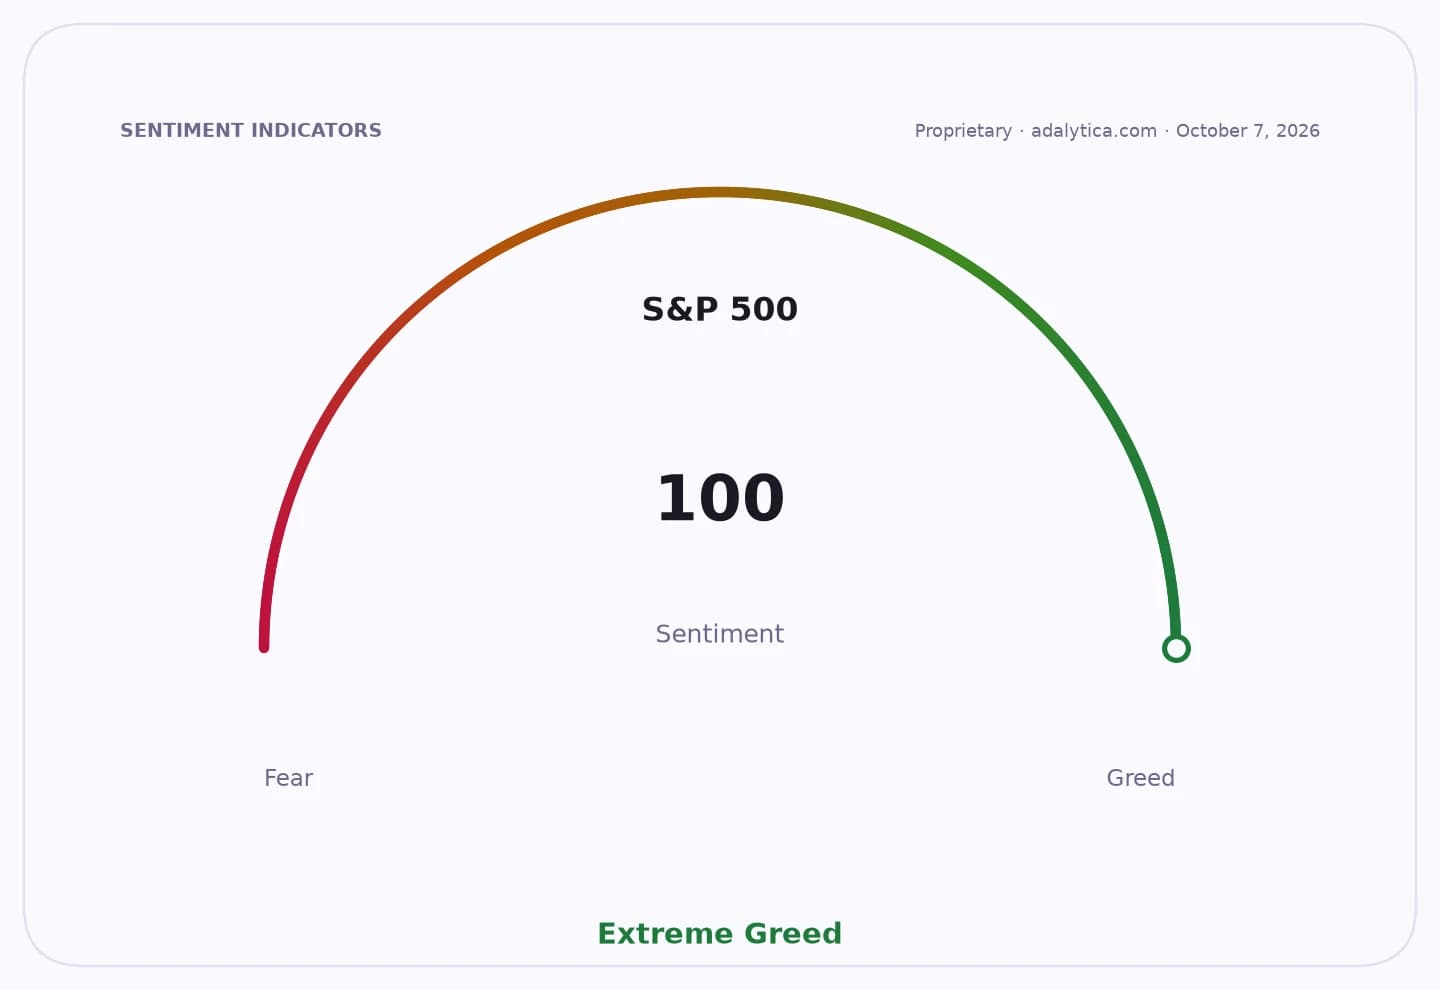
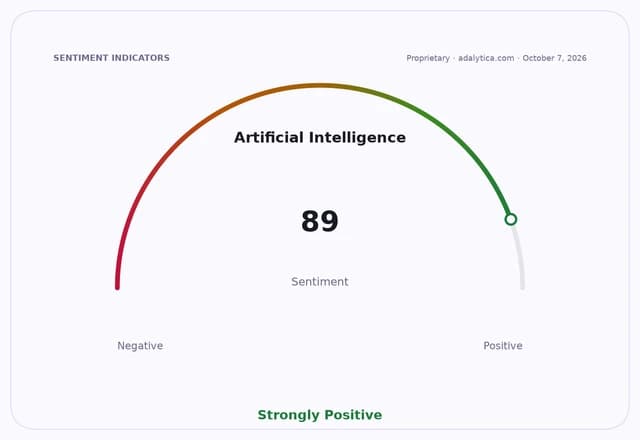
Investors should watch the tug of war between enthusiasm and valuation. Adalytica’s proprietary sentiment gauge for Nvidia remains in “Fear” even after the stock’s latest climb, a reminder that the market is excited but not uniformly comfortable chasing the shares higher from here. At the same time, the broader AI sentiment reading remains in “Extreme Greed,” which helps explain why the sector continues to attract capital despite stretched valuations.
For long-term investors, the more important question is not whether Nvidia can survive AMD’s rise — it can — but whether it can keep compounding at a pace that justifies one of the richest valuations in market history. The answer will depend on how durable AI demand proves to be, how quickly customers convert their spending into revenue, and whether Nvidia can keep translating technical leadership into cash flow. For now, the stock still looks like the clear leader in a secular growth wave that remains very much intact, but after such a powerful run, patience and diversification matter. Nvidia belongs on the watchlist, and for some investors, on the buy list on weakness.
| Entity | Gains | Losses |
|---|---|---|
| Nvidia | ▲Higher valuation, AI demand leadership | ▼More scrutiny on valuation |
| AMD | ▲More AI-chip capacity, market share push | ▼Faces dominant rival |
| AI infrastructure buyers | ▲More supply options | ▼Near-term pricing pressure |
| Short sellers / skeptics | ▲Potential pullback if rally cools | ▼Pain from continued momentum |