Ho Chi Minh City police have detained two shareholders of O Cap Housing Development over allegations they helped defraud 262 customers in a land project where buyers paid up to 100% of contract value even as the developer lacked the legal right to transfer the plots.
O Cap Housing shareholders detained in land fraud case
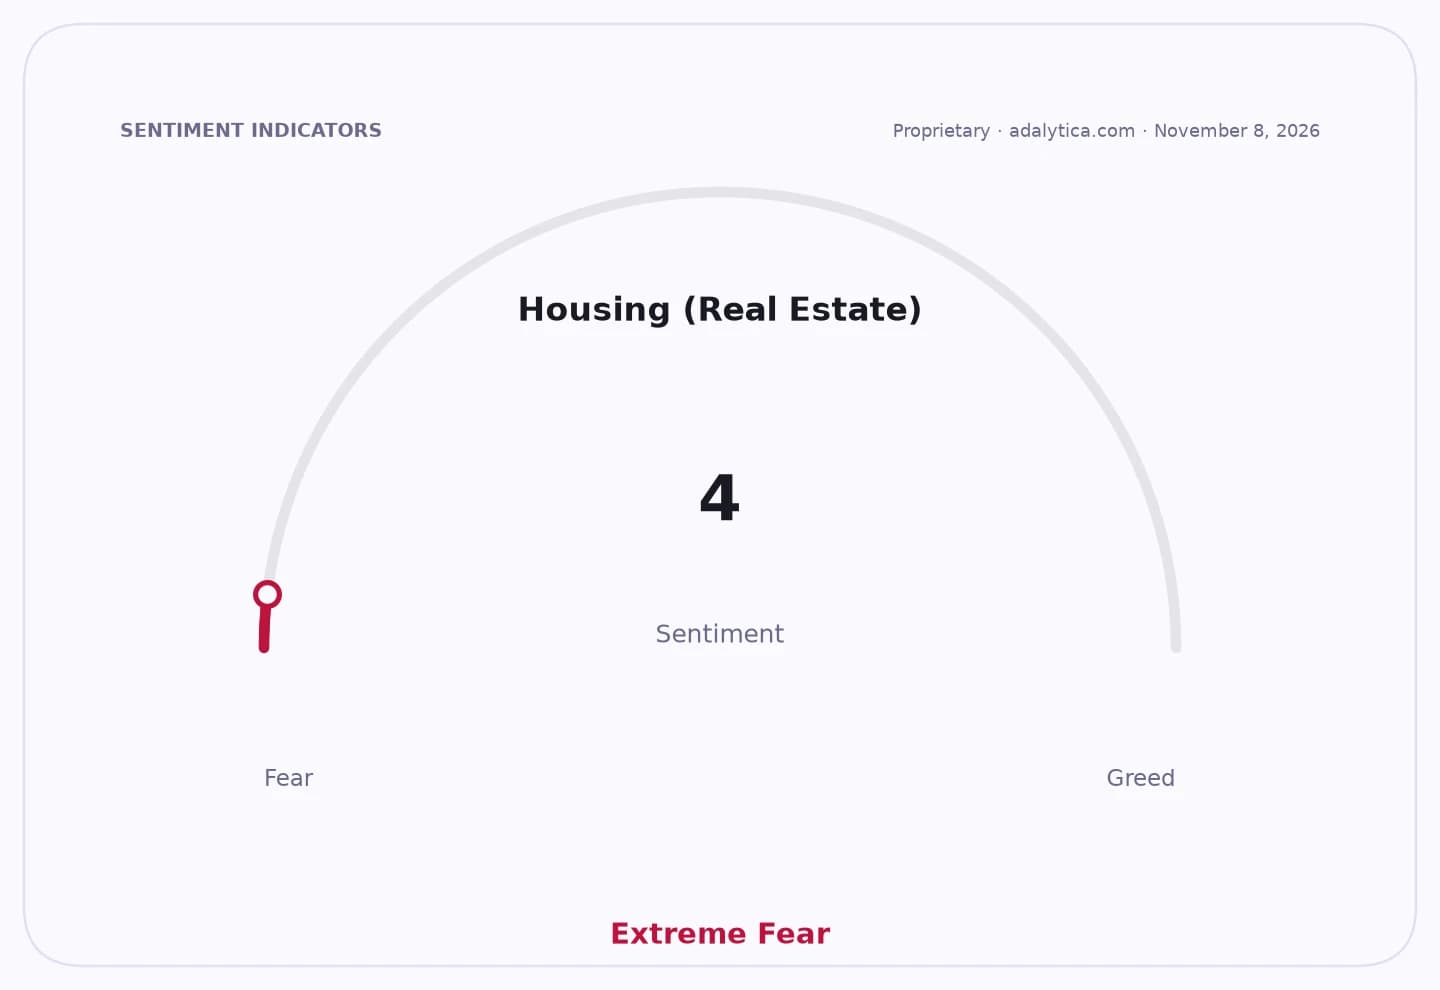
The case matters because it hits the most fragile part of Vietnam’s property market: pre-sale and capital-raising structures that depend on trust, informal financing and delayed legal completion. When those deals unravel, the damage does not stop at one company. It ripples through buyer confidence, bank collateral quality and the broader willingness of households to commit savings to land-linked investments.
Police said Nguyen Van Thanh and Phan Hong Viet were charged with fraud and temporarily detained after prosecutors approved the moves. They were shareholders in O Cap Housing Development and were tied to fund-raising and land transfers at the No. 1 Southwest Long Dien residential project, now in Ho Chi Minh City’s Long Dien area after administrative changes.
Investigators said the company was founded in 2001 and was assigned the project by Ba Ria-Vung Tau authorities in 2003-2004. But O Cap had not completed the legal procedures required to transfer land-use rights, while all land certificates for the project had already been pledged to banks. Even so, the company signed capital contribution contracts with 262 customers and collected more than 79.7 billion dong, or roughly $3 million, taking 70% to 100% of contract value.
The more damaging detail for investors is that after the plots were subdivided, the company and its shareholders allegedly failed to finish the paperwork needed to hand them over, then used the same land parcels as collateral for loans benefiting individuals and other businesses. Police say customers were cheated of more than 51 billion dong, about $2 million, and that the money was diverted in a way that left O Cap unable to deliver the plots or refund buyers.
This is exactly the kind of legal overhang that can keep Vietnam’s real estate market discounting to book and suppress capital formation across smaller developers. The market already underestimates how much value is trapped in incomplete projects and how quickly legal disputes can turn land inventory into stranded collateral. That is why the case is more than a criminal investigation: it is a stress test for developer governance, bank underwriting and the enforceability of property claims.
For investors, the message is straightforward. The winners are developers with clean title, transparent funding and access to formal financing. The losers are speculative land-flippers, thinly capitalized operators and any lender exposed to pledged project land without airtight legal control. If Ho Chi Minh City continues tightening enforcement while also trying to stabilize the market through clearer compensation rules for informal buyers, capital should migrate toward the strongest balance sheets and the most legally secure projects.
The next catalyst is whether authorities widen the probe into related land transfers and recover assets. If they do, the case could reset risk pricing across Vietnam’s residential sector and further separate investable names from the market’s weaker, more opaque players.
| Entity | Gains | Losses |
|---|---|---|
| Ho Chi Minh City authorities | ▲Enforcement credibility | ▼None immediate |
| Bonafide homebuyers | ▲Stronger legal protection | ▼Delayed recoveries |
| O Cap Housing Development | ▲None | ▼Reputation, control, liquidity |
| Other leveraged developers | ▲Relative market share | ▼Higher scrutiny, tighter funding |