PKO BP has sharply lifted the cost of legal risk tied to foreign-currency mortgages, underscoring how the last unresolved legacy of Poland’s housing boom continues to drain capital from even the country’s strongest lender.
PKO BP Raises FX Mortgage Legal Risk Charges
The bank said preliminary, unaudited charges linked to loans denominated and indexed to foreign currencies came to 371 million zloty in the third quarter, up from 297 million zloty in the second quarter. The increase reflects a fresh reserve after updating its legal-risk model and a higher estimated cost of settlements, which PKO BP said mirrors its current litigation strategy for the portfolio.
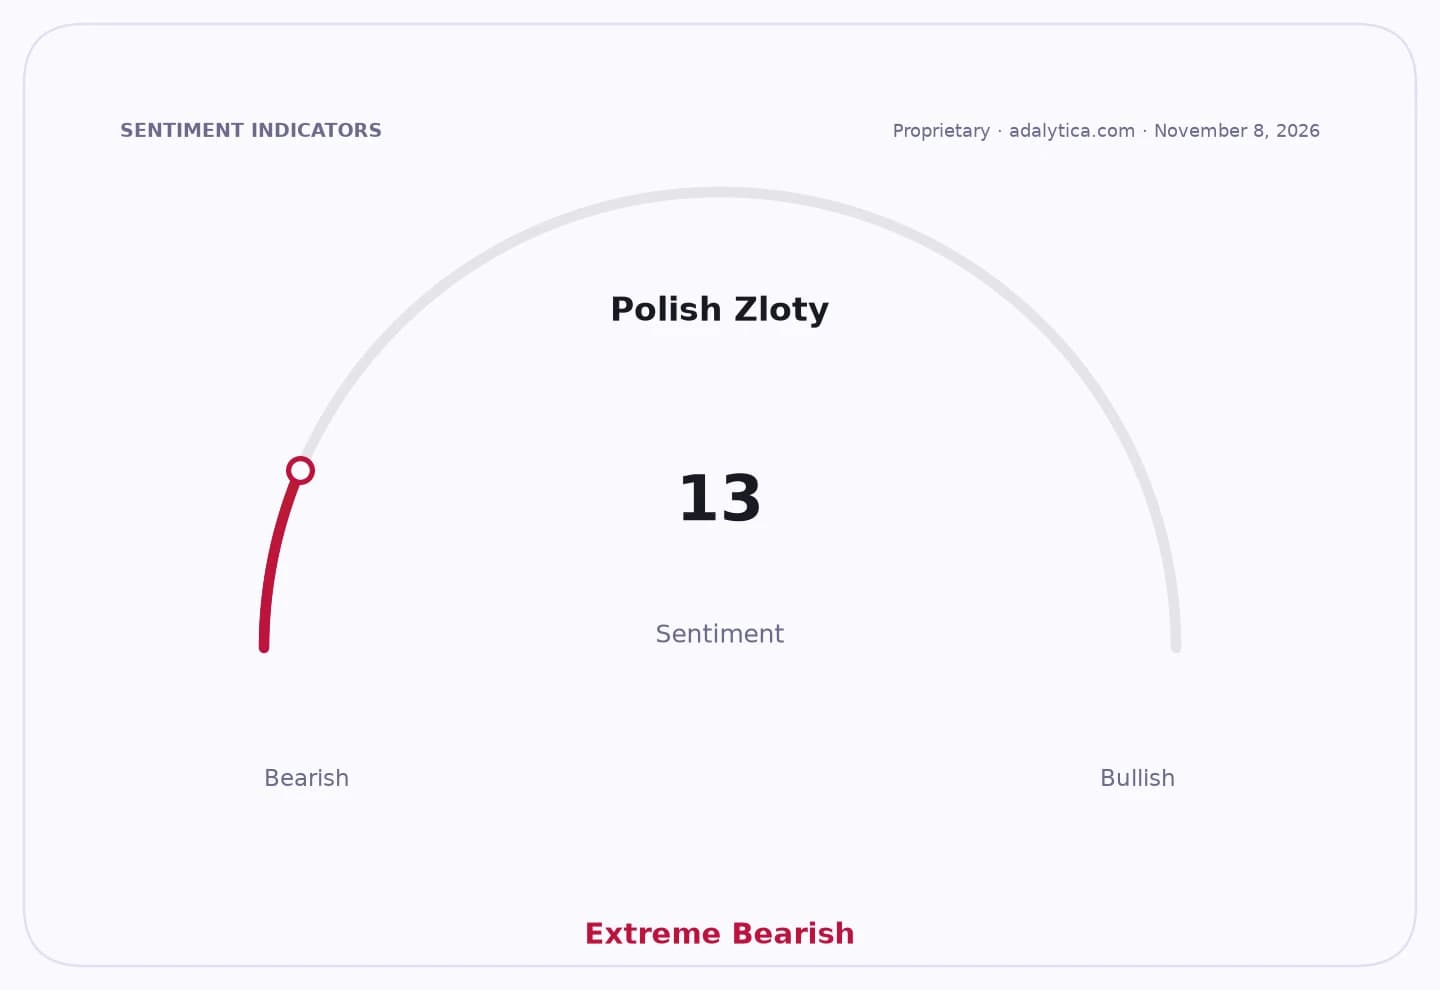
Sentiment Indicators
That matters because the bill is not just accounting noise. For Poland’s largest bank, with more than 12 million customers and the state still owning 29.43% of the shares, every extra zloty set aside for FX mortgages is a zloty that cannot be deployed into growth, dividends or buybacks. The drag also shows how the industry is still paying for a product sold years ago, even as the broader banking sector has been posting record profits.
PKO BP has been one of the clearest beneficiaries of higher rates and robust lending activity, reporting a record 10.68 billion zloty net profit in 2025 after more than 4 billion zloty of write-downs tied to foreign-currency loans. In the first half of this year, group net profit still reached 5.29 billion zloty. But the latest charge shows that the FX mortgage overhang remains big enough to bite into those earnings and keep valuation discounts alive.
Investors should read this as a reminder that Polish banks are not yet free of legal-risk volatility. Shares of PKO BP have been strong this year, but the stock has now climbed far enough that any deterioration in settlement assumptions or court outcomes can hit sentiment quickly. The recent pullback from the highs also suggests the market is starting to price in that risk again.
The broader story is that Poland’s banking windfall remains vulnerable to legacy mortgage litigation, even as balance sheets are otherwise solid. If settlement costs continue to rise, the sector will have less room to convert earnings into shareholder returns. If they stabilize, the market will likely reward PKO BP and its peers with a cleaner rerating. For now, the asymmetry still favors watching this legal overhang very closely.
| Entity | Gains | Losses |
|---|---|---|
| PKO BP shareholders | ▲Strong core earnings | ▼Higher legal provisions |
| Borrowers in FX-mortgage settlements | ▲More willingness to settle | ▼Limited bargaining leverage |
| Polish banking sector | ▲Continued profitability | ▼Ongoing legacy-risk drag |
| State Treasury | ▲Dividend support potential | ▼Lower distributable capital |