Plaza Retail REIT reported third-quarter adjusted funds from operations of CA$0.08 per unit, keeping the Canadian retail landlord on track but in a market still defined by weak housing sentiment and uneven demand for income property.
Plaza Retail REIT reports Q3 AFFO of CA$0.08 per unit
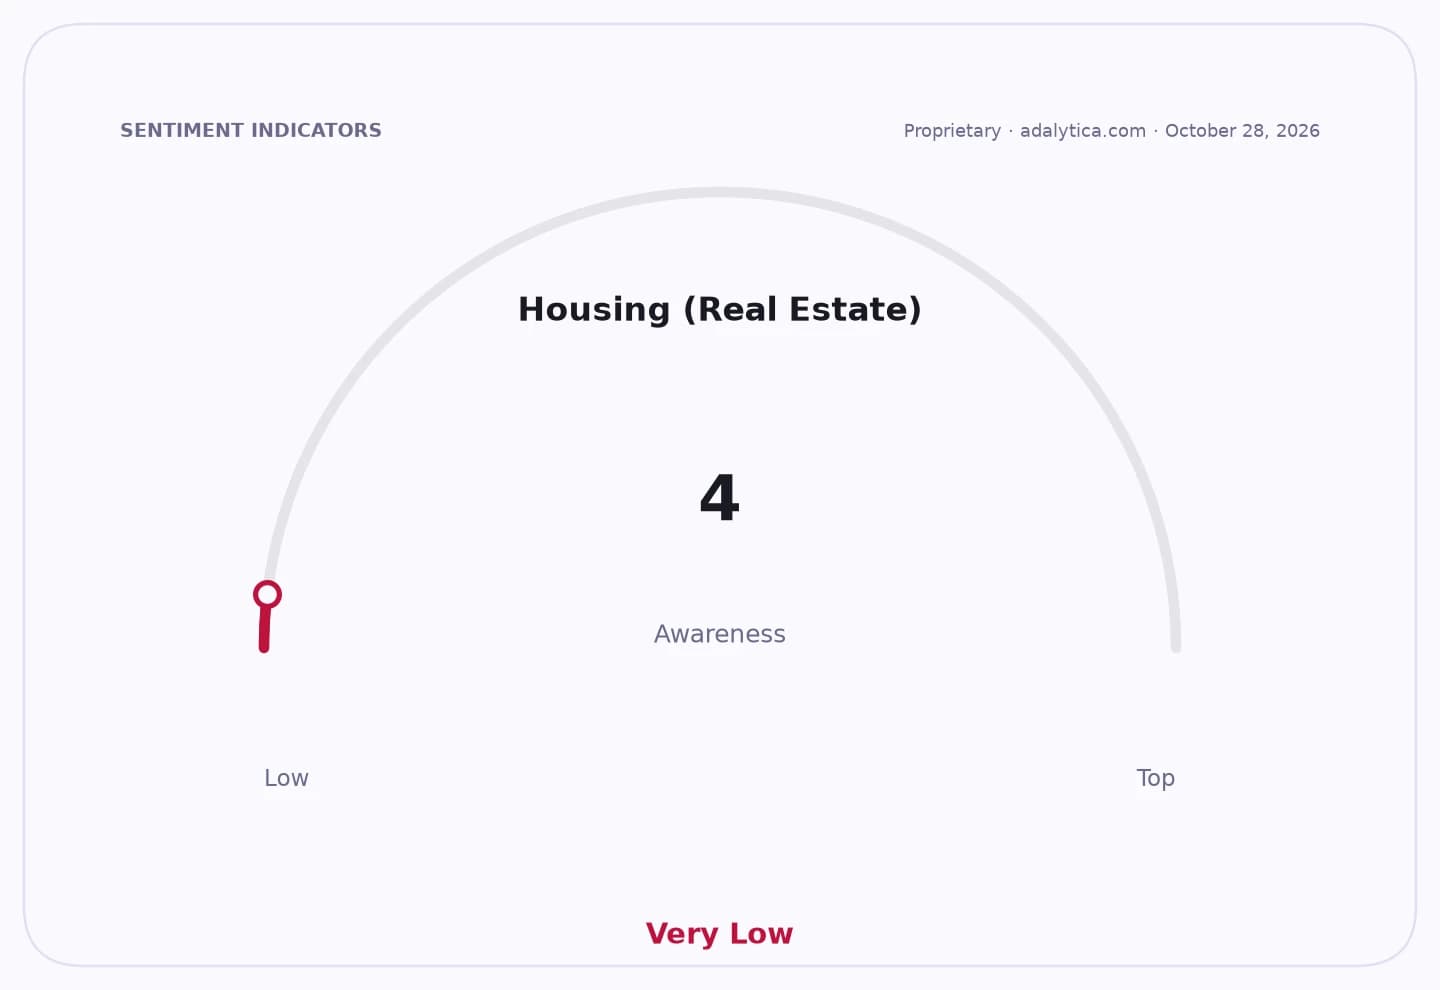
The result matters because REIT investors are balancing stable cash generation against a tougher backdrop for consumer-facing real estate. Plaza’s earnings come as Adalytica’s Housing Fear & Greed Index sits at 4, or “Extreme Fear,” a sign that caution around the broader property market remains intense even as some listed REITs continue to post operationally resilient results.
Sentiment Indicators
For investors, the key question is whether Plaza can sustain distributions and occupancy without leaning too heavily on a capital market that has become more selective. The sector has been receiving support from better-than-feared operating updates elsewhere, but the market is still differentiating sharply between landlords with steady cash flow and those exposed to weaker tenant demand or higher refinancing risk.
Plaza’s Q3 AFFO figure suggests the trust is generating enough cash to cover near-term obligations, though the market will focus on same-property performance, leasing spreads and debt costs in coming updates. Shares in the Canadian REIT space have also shown sensitivity to technical and macro shifts, with Plaza trading above its 50-day moving average in recent sessions and holding a stronger trend than earlier in the year.
The broader REIT backdrop remains mixed: Dream Industrial REIT has recently delivered strong quarterly results, while peers such as Dream Office and Granite have also highlighted portfolio and capital moves. For Plaza, the next catalyst is whether it can extend that operating stability into year-end while keeping distribution coverage intact and avoiding pressure from a still-fragile housing and retail environment.
| Entity | Gains | Losses |
|---|---|---|
| Plaza Retail REIT | ▲Stable AFFO coverage | ▼Margin for error remains thin |
| Income-focused REIT holders | ▲Near-term cash generation | ▼No clear growth re-rating |
| Competing retail landlords | ▲Validation for sector resilience | ▼Less room to stand out |
| Cautious property bears | ▲Evidence of soft macro backdrop | ▼REITs still posting earnings stability |