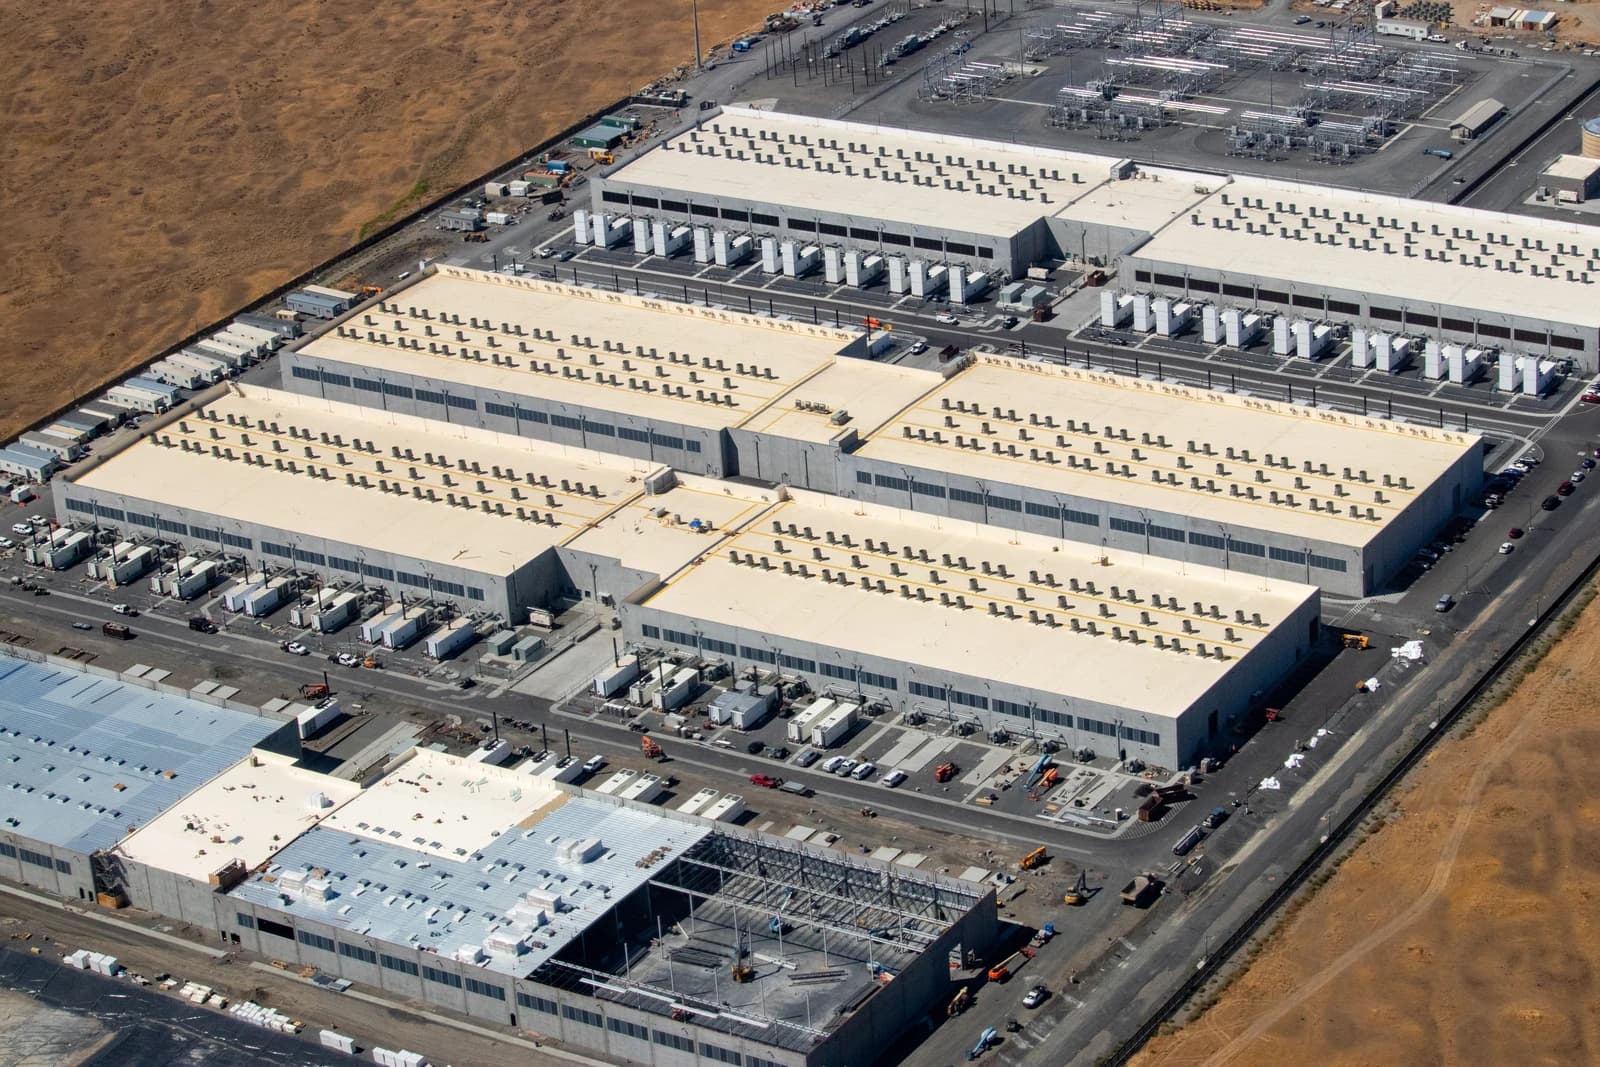
Qualcomm is drawing fresh backing from Alphabet as the Google parent deepens its push into AI infrastructure, a vote of confidence in the chipmaker’s effort to break out beyond smartphones and tap one of the fastest-growing parts of the semiconductor market.
Qualcomm Gets $548M Alphabet Investment
Alphabet disclosed an investment of about $548 million, or roughly Rp9.94 trillion, in Qualcomm in the third quarter, according to filings cited in Indonesian media. The transaction’s structure was not detailed, but it lands as Qualcomm targets data-center AI chips as a new growth engine after years of dependence on handset demand.
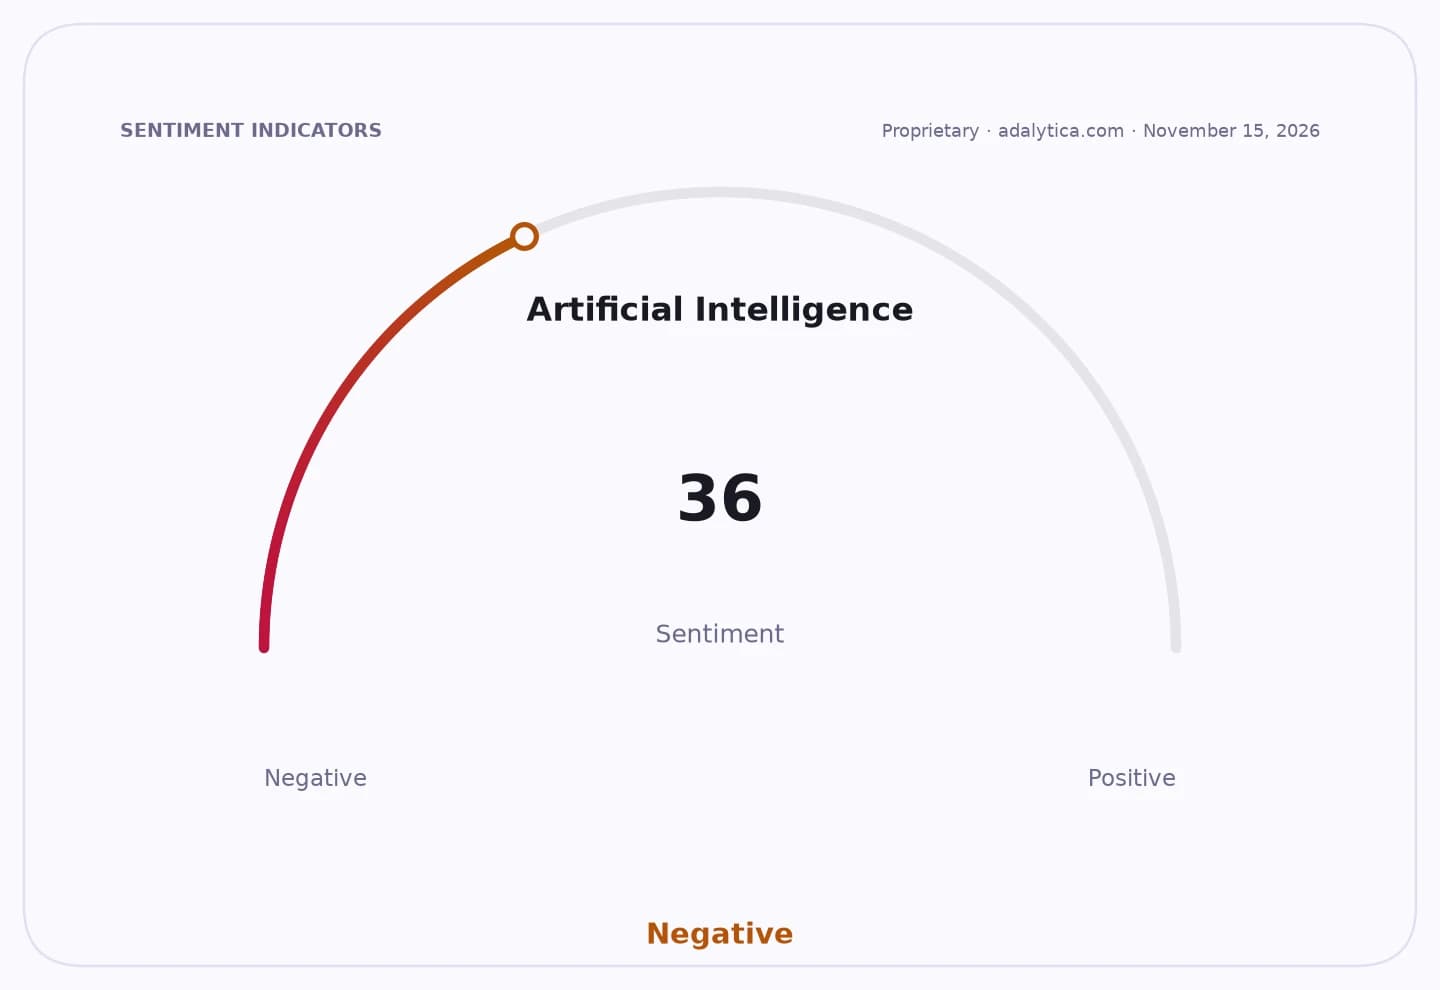
Sentiment Indicators
For investors, the significance is less about the size of the stake than what it represents: validation from one of the biggest spenders in AI hardware that Qualcomm wants a seat in the data-center buildout. Qualcomm has said AI data centers could generate about $15 billion in revenue by 2029, a forecast that would meaningfully diversify a business long tied to mobile devices.
The timing matters. Smartphone sales have slowed, while soaring memory costs since late 2025 have added pressure across consumer electronics, forcing companies including Samsung, Google and Apple to raise prices on some devices. HP has said RAM can account for nearly 30% of bill of materials in some products, underscoring how supply-chain inflation is squeezing margins and encouraging chipmakers to chase higher-value enterprise demand.
Qualcomm is already trying to capitalize on that shift. The company has said it is expanding into AI server chips and was reported earlier this year to have secured work with Amazon and Meta, signaling a broader effort to build relevance in the cloud-infrastructure market alongside rivals such as Broadcom and Nvidia.
Shares in Qualcomm have been volatile, with recent technical readings showing the stock below its 50-day moving average and its MACD still negative after a pullback from earlier highs. Google parent Alphabet, meanwhile, has continued to spend heavily across AI, reinforcing the broader capex cycle that is benefiting semiconductor suppliers tied to data-center expansion.
The key question now is whether Qualcomm can turn strategic interest into recurring revenue. Investors will be watching for follow-up customer wins, execution on AI chip design and whether management can bridge the gap between a long-term $15 billion target and actual orders from hyperscalers.
| Entity | Gains | Losses |
|---|---|---|
| Qualcomm | ▲AI credibility, new revenue path | ▼Smartphone dependence |
| Alphabet/Google | ▲Access to broader chip supply | ▼Capital deployment risk |
| AI chip suppliers | ▲Bigger infrastructure demand | ▼More competition for contracts |
| Smartphone makers | ▲None | ▼Higher input costs, slower demand |