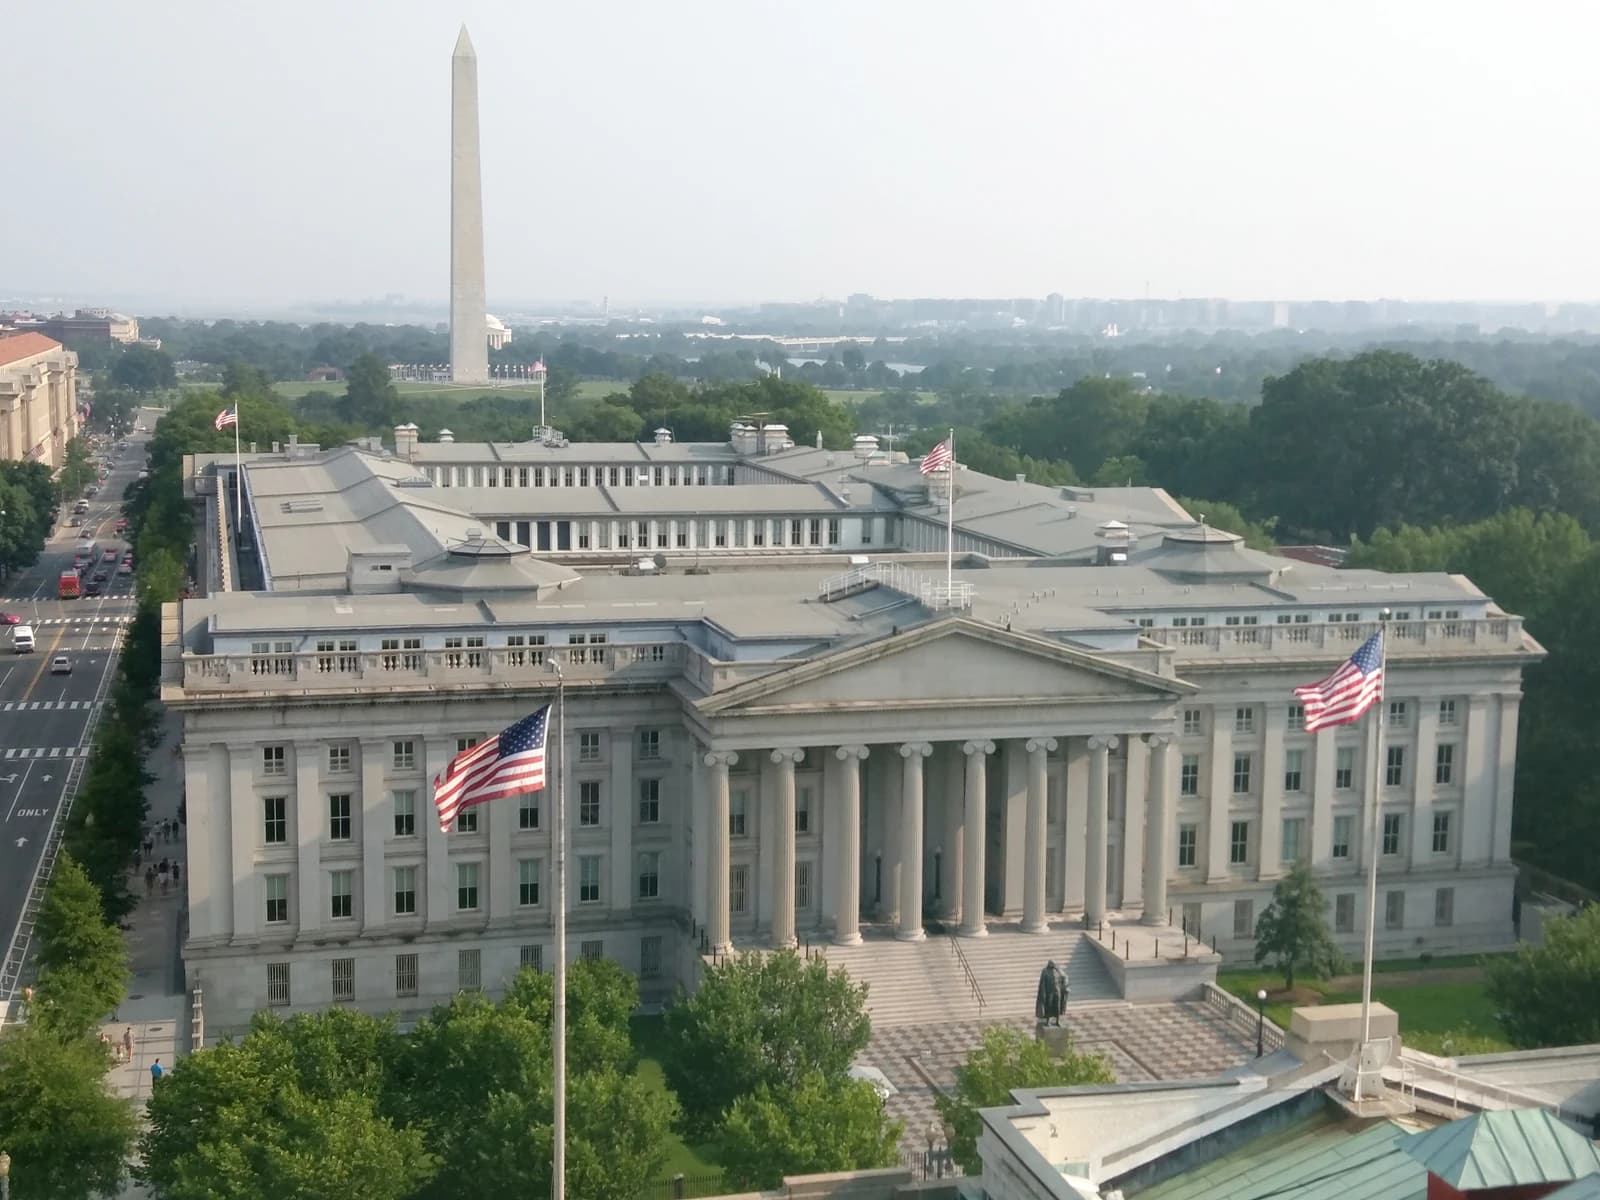
Higher interest rates are still the biggest headwind for real estate investors, and the latest market action shows the pain is not fading. U.S. REIT funds are under pressure, commercial property financing is tightening, and the global appeal of income-producing assets is being tested by a 10-year Treasury yield around 5.1% and a fed funds rate near 3.75%.
REITs Fall as Treasury Yields Stay Near 5.1%
That matters because real estate is one of the most rate-sensitive corners of the market. When borrowing costs stay elevated, property owners refinance at higher rates, buyers pay less for future rent streams, and lenders become more selective. The result is weaker valuations, fewer transactions, and slower growth in real estate credit — exactly the combination investors have been wrestling with across the REIT sector.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 17, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The numbers back that up. The Vanguard Real Estate ETF, or VNQ, has slipped to $91.76 from a recent high above $97, while the iShares U.S. Real Estate ETF, IYR, has fallen to $97.39 from more than $103. The Real Estate Select Sector SPDR, XLRE, has retreated to $42.16 from a spring peak near $44.59. These are not collapse levels, but they do show a sector struggling to regain momentum even after brief rallies.
The weakness is not just a U.S. story. REITs are being marked down globally because higher rates raise the discount rate on future cash flows everywhere, not just in American malls, offices and apartments. That is why investors are paying close attention to any sign that central banks can ease financial conditions without reigniting inflation. For now, the bond market is doing the tightening for them.
DGS10 vs FEDFUNDS — macro contextadalytica.com
Explore this data interactively — full history, time series and cross-market comparisons.Open AlphaPulse
At the same time, the financing backdrop is getting less forgiving. U.S. housing starts are forecast at just 1.2785 million for September after a choppy year, a reminder that high mortgage and construction costs are still weighing on real estate activity. In the credit market, the broader lending environment is also less accommodating, making it harder for property owners to rely on cheap leverage to juice returns.
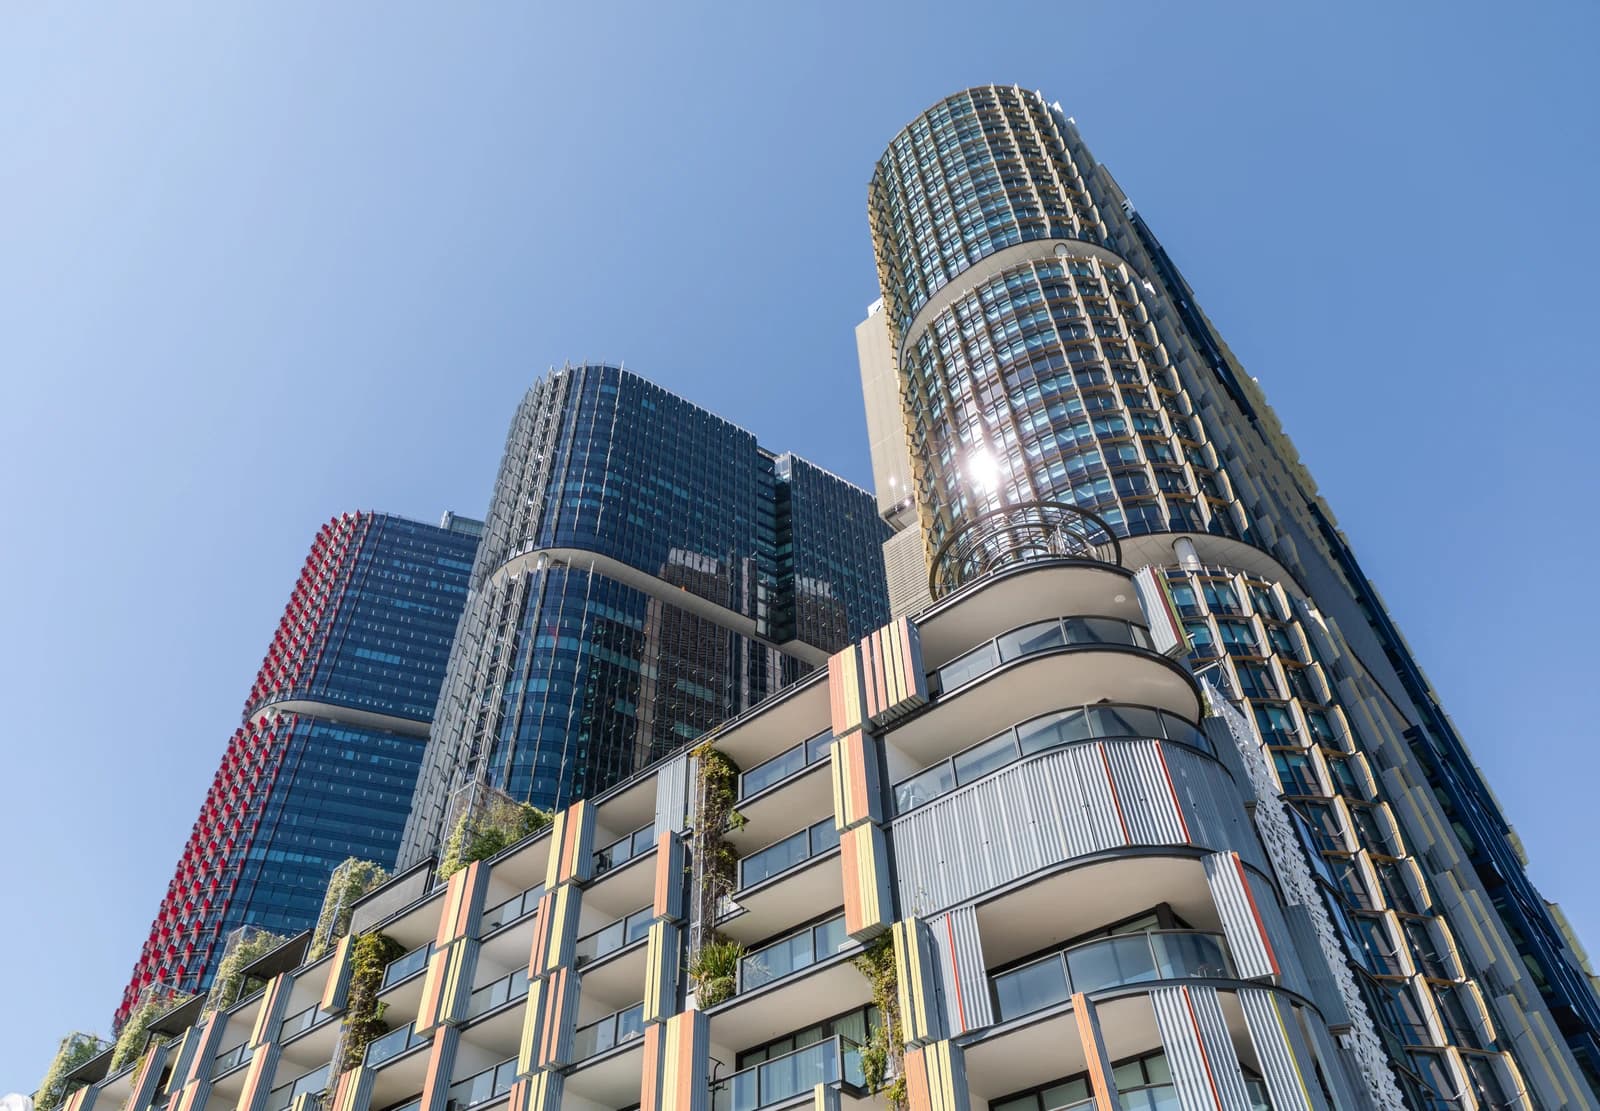
And yet, the story is not uniformly bearish. Premium assets are still attracting capital, which is a useful reminder for long-term investors that not all real estate is equal. The latest evidence is an $864 million purchase by an offshore REIT to increase its stake in Sydney’s tallest commercial tower. That kind of deal suggests that top-tier properties in major cities can still command global demand, even when the broader sector is under stress.
For investors, the message is straightforward: rates still matter more than most other single variables for REIT performance. If yields stay near current levels, weaker balance sheets, shorter-dated debt and lower-quality properties will continue to feel the most pressure. If borrowing costs eventually ease, the same sector could recover quickly because REITs are built around income and long-duration cash flows.
That is why patient investors should focus less on trying to time every swing and more on quality. REITs with strong occupancy, pricing power, conservative leverage and access to capital are the ones most likely to compound over years, not quarters. The current pullback may be uncomfortable, but for long-term buyers it is also a reminder that the best real estate businesses can survive bad rate cycles and emerge stronger when the cycle turns.
| Entity | Gains | Losses |
|---|---|---|
| Treasury bondholders | ▲Higher yield appeal | ▼REIT valuations |
| Prime-property owners | ▲Capital for trophy assets | ▼Secondary real estate |
| Low-leverage REITs | ▲Better financing access | ▼Highly indebted REITs |
| Long-term investors | ▲Better entry points | ▼Short-term holders |