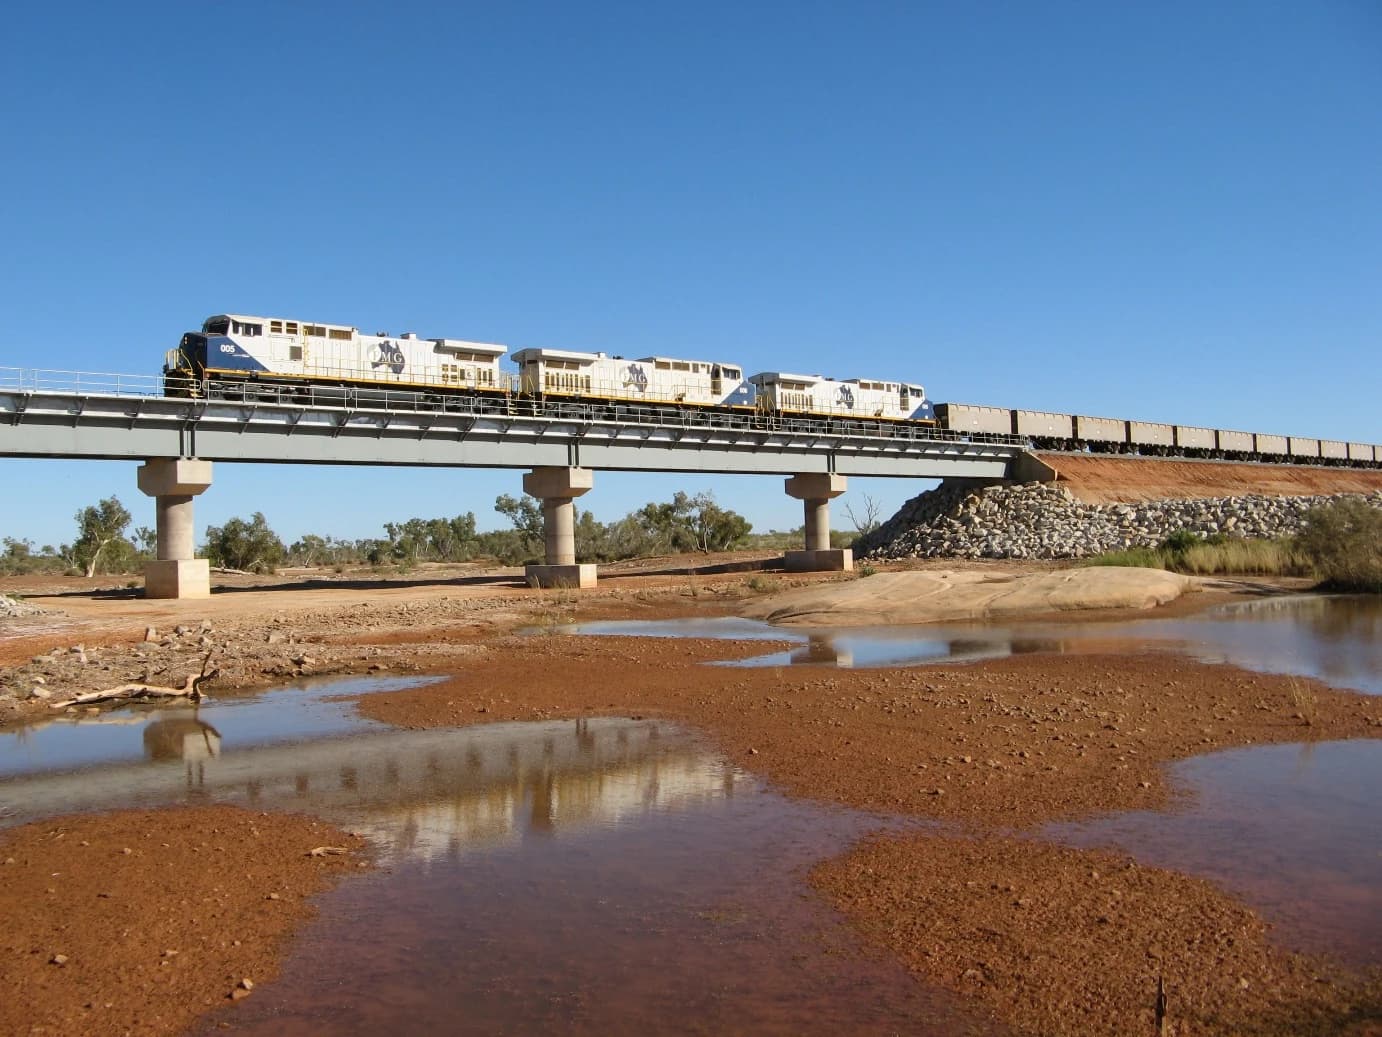
Rio Tinto’s exposure to iron ore looks less vulnerable than the market fears, and that matters because the miner still leans heavily on a commodity that drives cash flow, dividends and buybacks across the global bulk materials trade.
Rio Tinto Iron Ore Outlook Seen as Less Risky
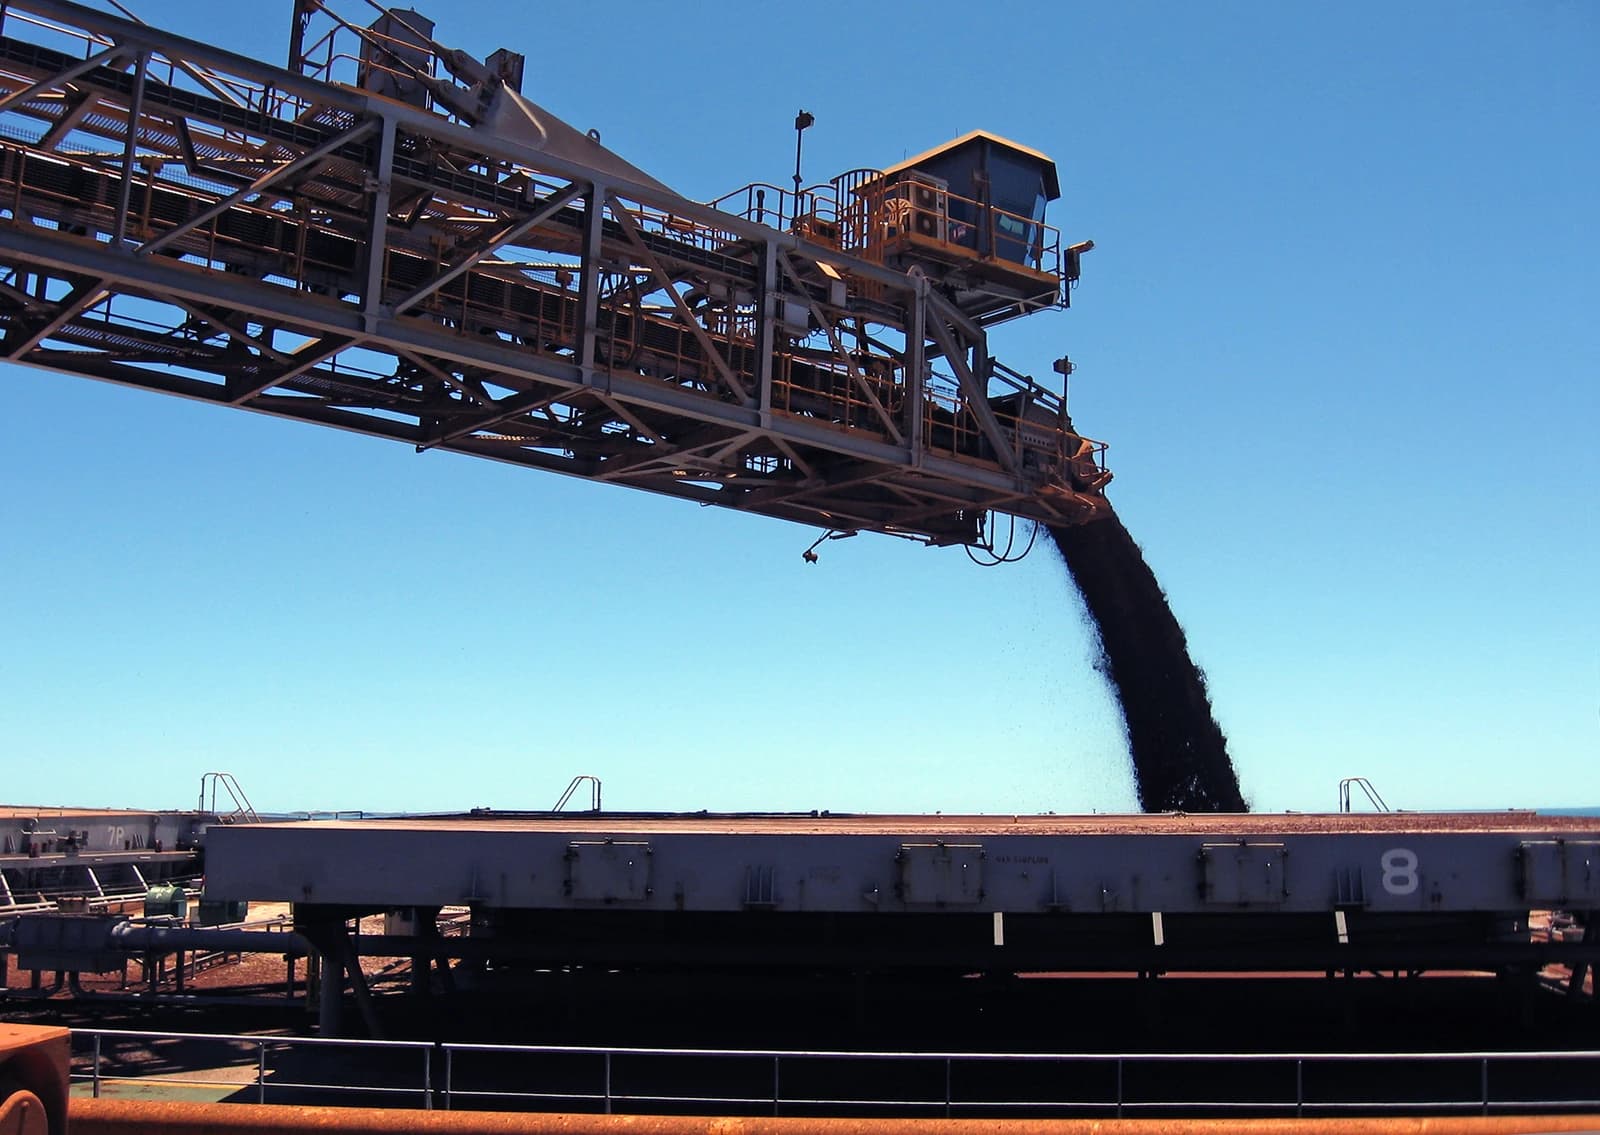
RBC Capital Markets’ view that the risk of a decline in iron ore prices is lower for Rio Tinto lands at a time when the stock has already run hard. Rio shares were recently trading around $95.89 in New York, well above the 50-day moving average of $98.39 and 200-day average of $93.51, with technical momentum easing but still holding close to the upper end of its recent band. That puts the debate squarely on fundamentals: if iron ore does not weaken as much as bears expect, Rio’s earnings power stays far more resilient than the market is pricing.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 8, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
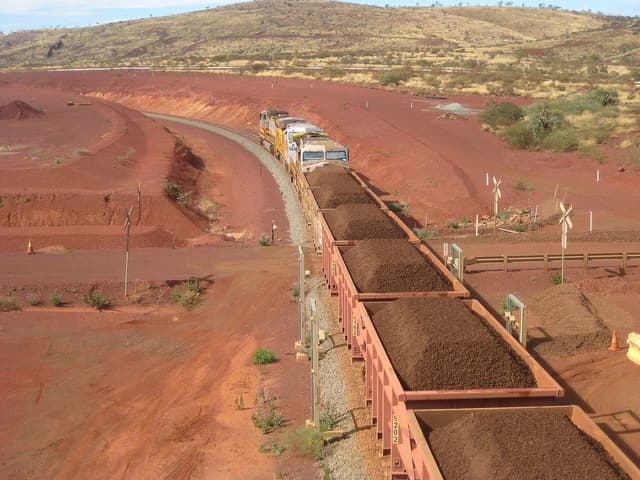
That is important for investors because Rio is one of the cleanest ways to express a China-linked commodity recovery without taking on the same degree of operational complexity as more diversified miners. The broader market backdrop is also supportive. Adalytica’s China growth-target signal shows extreme greed, while the yuan trade signal sits at extreme fear, a combination that often marks a policy-sensitive setup for industrial demand and pricing. In other words, investors are still braced for China weakness, but the positioning looks more defensive than the macro data may justify.
The contrast with peers matters. BHP was trading near $87, while Vale was around $14.08, underscoring how tightly the entire iron ore complex remains tied to shifts in China demand and sentiment. If iron ore prices stabilize instead of rolling over, the leverage is most attractive in the high-quality producers with the strongest balance sheets and the best asset bases — Rio first among them.
For the market, the key issue is not whether iron ore is booming; it is whether the downside case has become too crowded. RBC’s call suggests the answer may be yes. That opens the door to a rerating of the miners if China stimulus, infrastructure demand or supply discipline keeps prices from breaking lower. For investors looking for a cyclical with upside torque and limited balance-sheet risk, Rio remains one of the most compelling names to own into year-end.
| Entity | Gains | Losses |
|---|---|---|
| Rio Tinto | ▲More resilient cash flow | ▼Iron ore bears |
| BHP | ▲Sector support from firmer ore | ▼Short sellers |
| Vale | ▲Stabilized pricing backdrop | ▼Buyers expecting steep discount |
| China steel demand | ▲Better miner supply discipline | ▼Deflationary commodity traders |