Iron ore prices are under pressure as signs of softer Chinese steel demand outweigh support from stronger miner earnings and rising supply-side activity in India and Brazil.
Iron ore prices fall on weak Chinese steel demand
The market backdrop is turning less favorable for producers and miners’ customers alike. Global crude steel output fell 1.2% in August, inventories in China have been building and steel margins remain squeezed, keeping a lid on iron ore sentiment even as some import losses narrow on lower freight costs and softer premiums.
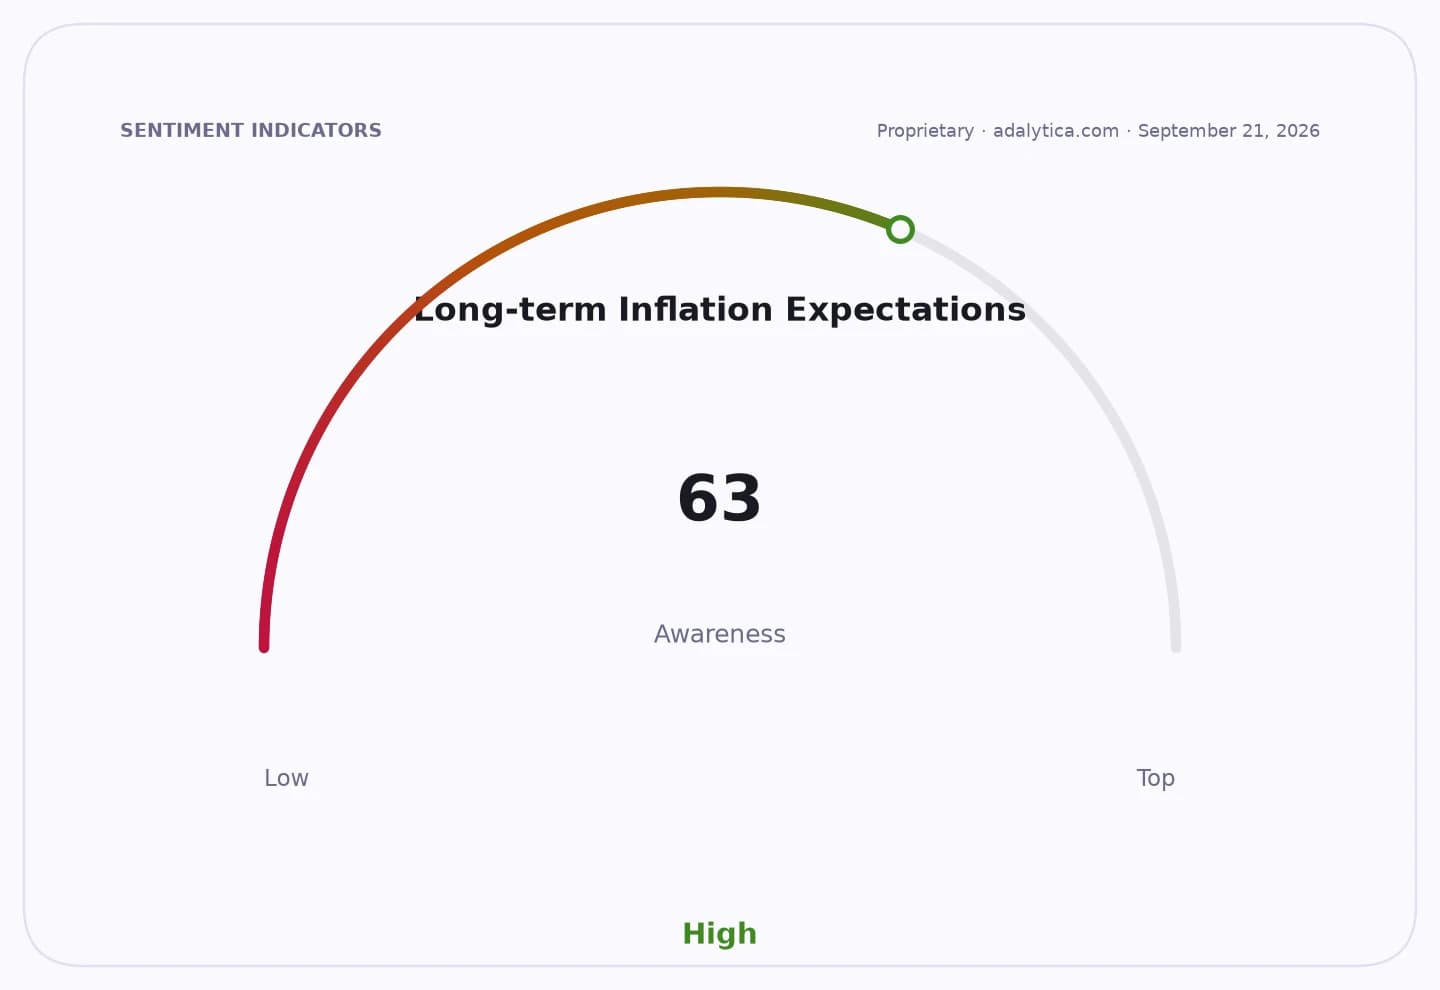
Sentiment IndicatorsⓘProprietary · adalytica.com · October 2, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
BHP’s latest earnings offered some offset, with the miner reporting a 9% profit increase on robust copper and iron ore performance. But the stock reaction shows investors are looking past near-term profit strength and focusing on the demand side: BHP fell to $84.65 on Oct. 1 from $84.84 a day earlier and $87.83 on Sept. 22, while Rio Tinto slipped to $92.87 from $94.17 on Sept. 30 and $99.33 on Aug. 5.
Vale has seen the sharpest pressure, dropping to $13.45 on Oct. 1 from $13.41 the day before and $15.73 in early September, with its RSI, a standard technical indicator, sinking to 19.7, a level that points to deeply oversold trading. Rio’s RSI was 22.1 and BHP’s was 39.3, underscoring the broader weakness across iron ore-linked equities.
The slump comes despite supply-side support from India, where NMDC said iron ore production rose 23% to 27 million tonnes in the April-September period, and from new domestic projects such as Tata Steel’s approved $347 million grinding plan in Odisha. Those investments may help local supply over time, but they also reinforce the view that the market is adjusting to shifting flows and a softer global steel cycle.
For investors, the key question is whether Chinese construction and industrial demand stabilizes enough to arrest the slide in ore prices. Until then, miners may keep generating healthy cash flow from existing operations, but their share prices are likely to stay tied to steel margins, freight costs and Beijing’s next move on growth support.
| Entity | Gains | Losses |
|---|---|---|
| Steel mills | ▲Lower input costs | ▼Weak finished-steel margins |
| Iron ore miners | ▲Volume from supply projects | ▼Weaker pricing power |
| Chinese buyers | ▲Cheaper imports | ▼Oversupplied steel market |
| BHP/Rio/Vale shareholders | ▲Earnings support from operations | ▼Share-price downside from demand fears |