The Indian rupee is entering Samvat 2082 under renewed pressure even as the 10-year bond yield hardens, a combination that matters because it tightens financial conditions for the economy just as global dollar strength is reasserting itself.
Rupee and India Yields Pressure Samvat 2082
For investors, that mix is more important than the day-to-day move in either market on its own. A weaker rupee lifts import costs, keeps a lid on how quickly inflation can fade, and forces the Reserve Bank of India to balance currency stability against growth support. At the same time, firmer long-end yields raise the government’s borrowing bill and make domestic equities less attractive relative to cash and fixed income.
Sentiment Indicators
The macro setup is not benign. Benchmark US 10-year Treasury yields have climbed to around 4.88%, while US inflation has stayed sticky, with the latest CPI reading at 337.476 and a forecast for 338.6475 next month. That keeps the dollar supported, and Adalytica’s US Dollar Trade Signals show “Extreme Greed,” a clear sign that the greenback’s strength is still in force. For India, that translates into less room for the rupee to stage a durable rally unless crude prices stay contained and foreign inflows improve materially.
That is why the bond market matters here. Harder domestic yields reflect a market that is demanding more compensation to hold Indian duration in a world where global rates remain elevated. Higher yields can attract some portfolio money, but they also raise the hurdle rate for corporates and the sovereign alike. If the rupee stays soft while borrowing costs rise, the impact is felt first in rate-sensitive sectors, infrastructure funding and import-heavy businesses.
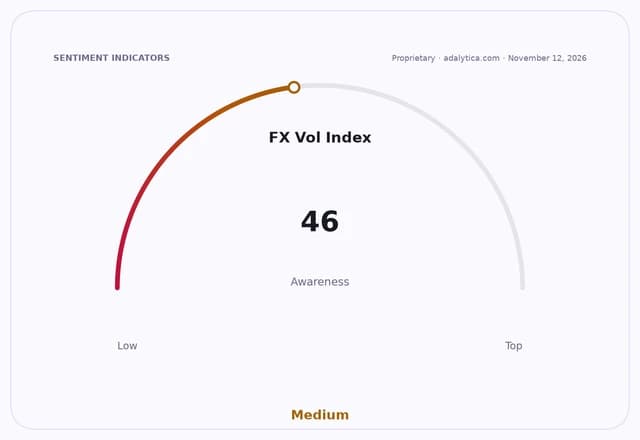
Indian equities are already pricing in some of that tension. The INDA ETF has jumped to 51.72 after a sharp recovery from an October low near 45.56, but its RSI at 85.5 points to a stretched short-term move rather than a clean breakout. The EPI ETF, which tracks a broader basket of Indian shares, is firmer too at 44.24, but that strength is coming alongside currency weakness rather than because it has been solved. In other words, the market is rewarding India’s growth story, but it is not ignoring the cost of capital.
The immediate trade is straightforward: if the rupee remains under pressure and yields keep hardening, investors should favor exporters, IT services and other dollar earners over banks, real estate and leveraged domestic cyclicals. That is the asymmetry in Samvat 2082. India’s long-term growth case remains intact, but the next leg of returns is likely to come from companies that can turn a softer rupee and higher rates into a margin advantage, not from those that depend on cheap money.
| Entity | Gains | Losses |
|---|---|---|
| Exporters, IT services | ▲Higher rupee realizations | ▼Importers, margin compression |
| Bondholders, RBI | ▲Tighter inflation control | ▼Borrowers, higher funding costs |
| Dollar, US assets | ▲Safe-haven demand | ▼Rupee, India duration |
| Indian growth stocks with leverage | ▲Selective pricing power | ▼Rate-sensitive sectors |