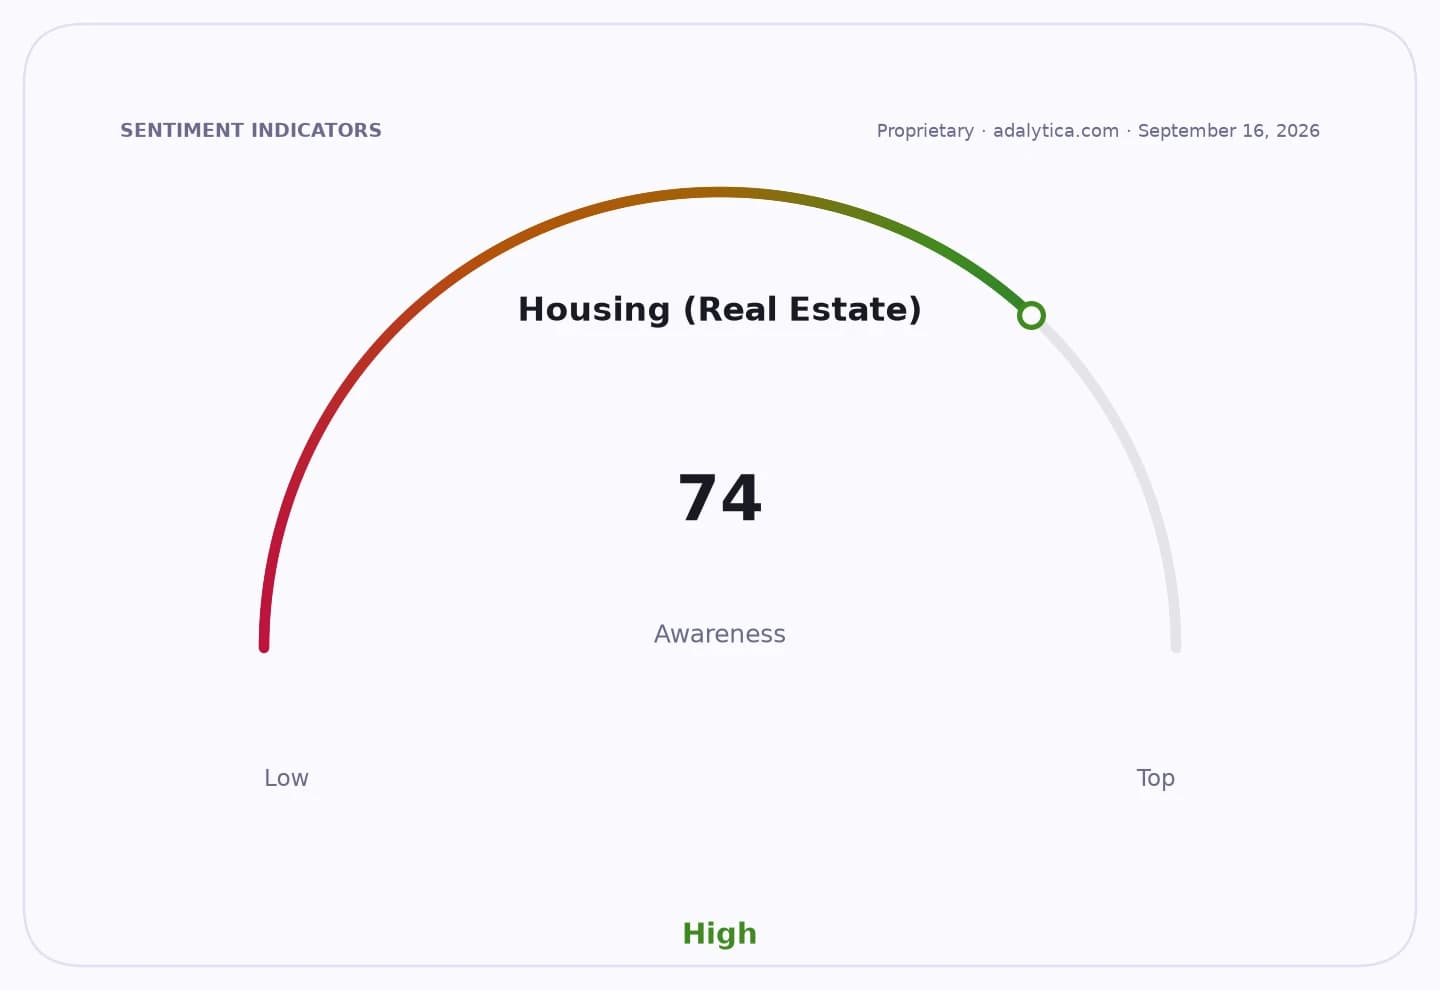
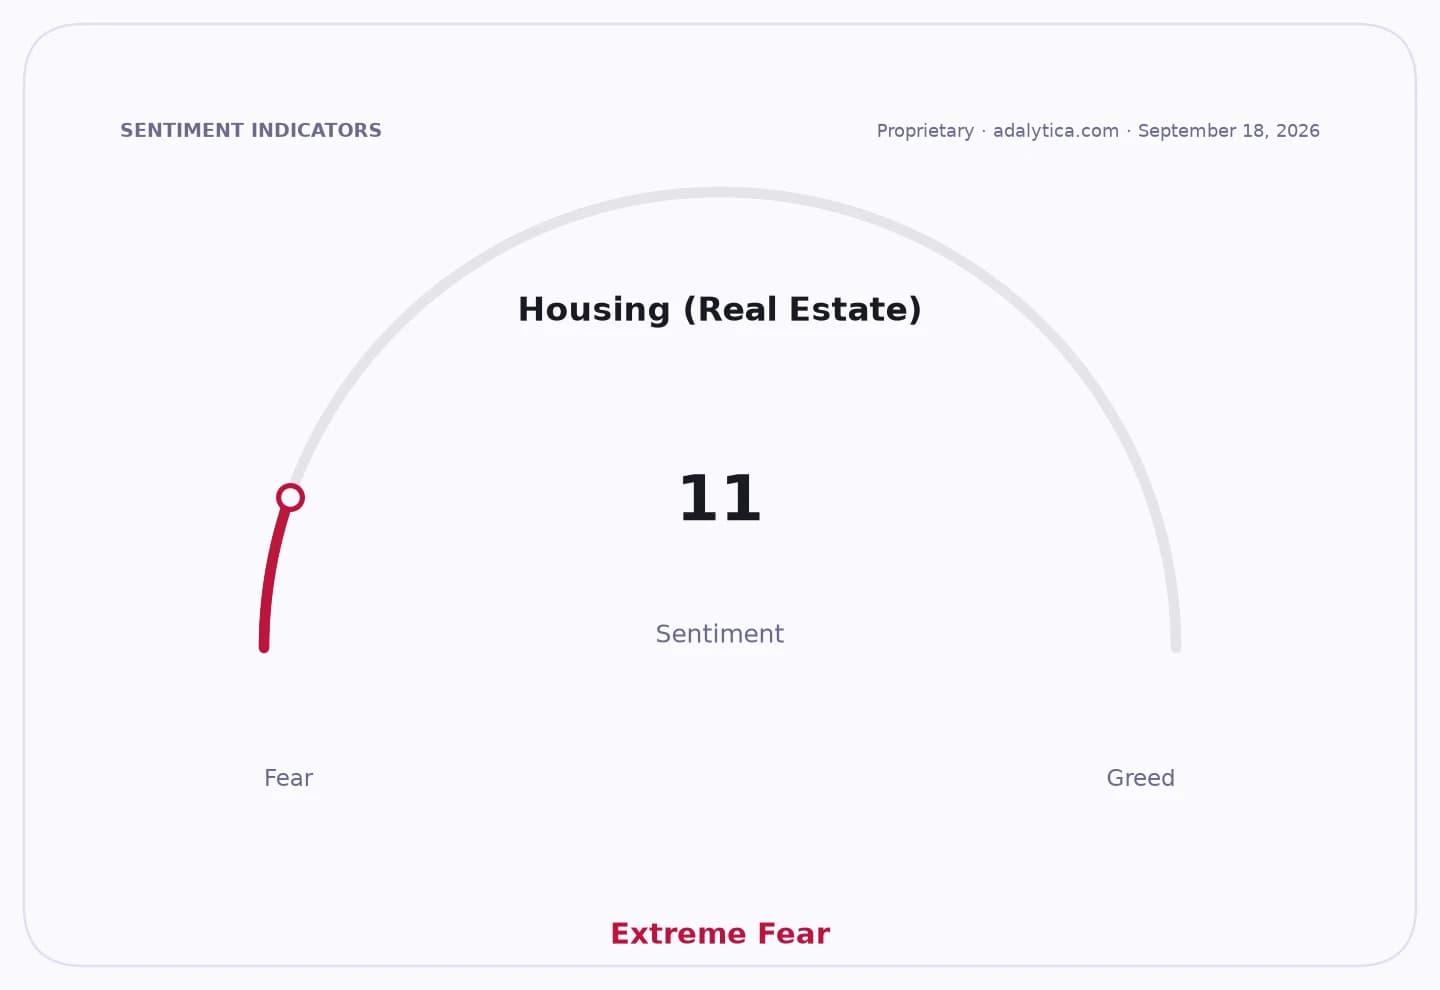
Russia’s finance ministry has rewritten the terms of its flagship family mortgage program from October 2026, making borrowing cheaper for bigger families and more expensive for smaller ones in a move that deepens state support for childbirth, housing demand and the construction sector.
Russia raises family mortgage rates for smaller households
The change matters because the family mortgage has become one of the Kremlin’s main policy levers for propping up home purchases in an environment of elevated borrowing costs. By linking the subsidy more directly to family size, Moscow is trying to steer scarce budget support toward households it views as most aligned with its demographic goals, while preserving demand for developers and related industries.
Under the new rules, loans for families with five or more children and at least one child under seven will carry a 2% rate outside Moscow, St. Petersburg and the surrounding regions, with a maximum loan size of 10 million rubles. Families with four children will pay 4%, those with three children 6%, and those with two children 8%. Families with one child under seven will face a 10% rate and a 6 million-ruble cap.
In the four capital regions, the program is more generous in absolute terms because of higher housing costs, but still follows the same sliding scale: 4% for the largest families and 12% for one-child households, with loan limits ranging from 12 million rubles to 18 million rubles depending on family size.
The ministry said the program has already issued about 11 trillion rubles in subsidized loans since its launch in 2018, and more than 2 million families have improved their housing conditions. That scale shows why the policy matters well beyond household affordability: it has become a material support for mortgage origination, construction activity and the broader housing market.
For investors, the revised framework points to a more selective form of state intervention. The most obvious beneficiaries are Russian homebuilders, lenders with exposure to subsidized mortgages and suppliers tied to residential construction. The losers are smaller families, who will now face much steeper financing costs, and potentially developers in segments that had relied on broad-based subsidy demand.
The timing also underlines the government’s balancing act. Russia wants to promote family formation, but it is also trying to avoid unlimited budget leakage into a housing market already shaped by high rates and strained affordability. Tying cheaper credit to larger families could help target public spending more precisely, but it may also reduce the pool of eligible borrowers compared with the current program.
For the housing market, the key question is whether the new structure supports enough volume to keep demand steady when the changes take effect. If uptake remains strong among large families, the program should continue to cushion builders and mortgage lenders. If not, the higher rates for smaller households could slow transactions and leave some segments more exposed to tighter financing conditions.
The broader message is that Moscow is using housing policy as both an economic stabilizer and a demographic tool. The new mortgage rules are designed not just to help families buy homes, but to channel credit toward the households the state wants to reward most.
| Entity | Gains | Losses |
|---|---|---|
| Large Russian families | ▲Lower mortgage rates | ▼Smaller financing burden elsewhere |
| Russian homebuilders | ▲Sustained subsidized demand | ▼Less broad-based buyer pool |
| Mortgage lenders | ▲Continued originations | ▼More complex pricing and eligibility |
| Small Russian families | ▲— | ▼Higher rates and tighter caps |