Sagicor Bank Jamaica is using eco-friendly residential mortgages to pull more borrowers into the housing market at a time when lenders are easing mortgage conditions and climate-linked financing is moving from niche product to mainstream pitch.
Sagicor Bank Jamaica Launches Eco-Friendly Mortgages
The bank’s new mortgage campaign and “Mortgage Boutique” experience is aimed at homeowners who want greener properties or energy-efficient upgrades, a move that matters because housing finance is one of the clearest channels through which banks can influence both affordability and construction activity. In markets where higher borrowing costs have strained completions and household budgets, any product that broadens access while promising lower long-term utility costs can help support demand.
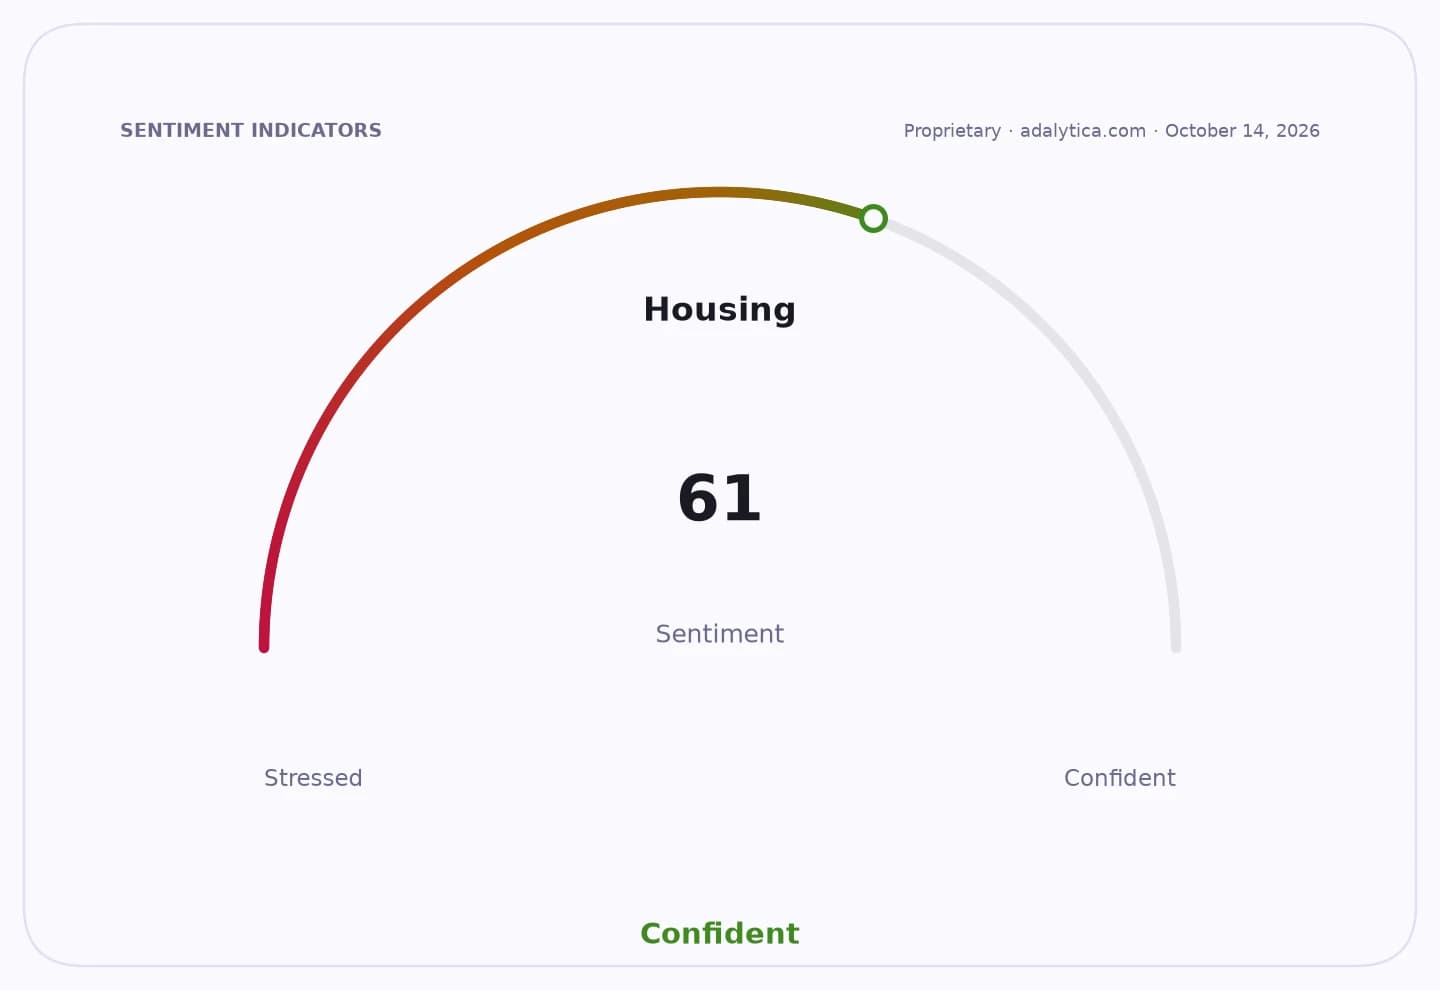
Sentiment IndicatorsⓘProprietary · adalytica.com · October 14, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The strategy also gives Sagicor a way to differentiate itself in a competitive mortgage market without relying solely on price. Eco-friendly mortgages can be marketed to first-time buyers, existing homeowners and developers looking to position projects around energy efficiency, water conservation and lower operating costs. That can improve customer acquisition and deepen relationships across deposits, insurance and other retail banking products.
For Jamaica, the initiative fits a broader financial-sector shift toward climate resilience. Caribbean economies are exposed to storms, flooding and energy-price volatility, so lenders have a commercial reason to back homes that are cheaper to run and potentially more resilient over time. That makes the mortgage book not just a consumer product, but a lever for managing future credit risk tied to environmental damage and household cash flow.
The move comes as mortgage lenders elsewhere have begun relaxing conditions after a period of tighter credit, underscoring how banks are trying to balance risk control with demand generation. If eco-friendly mortgages attract borrowers who have stronger balance sheets or lower running costs, the product could improve loan quality at the margin. The bear case is that green features can remain a marketing label unless they are paired with meaningful underwriting incentives, verified energy savings and enough housing supply to matter.
Investors should watch whether Sagicor’s campaign translates into higher mortgage originations, better fee income and a more defensible retail franchise. The bigger question is whether this becomes a template for climate-oriented lending across the Caribbean, where banks may increasingly compete not just on rates, but on how well they finance homes that are cheaper, cleaner and less exposed to weather-related shocks.
| Entity | Gains | Losses |
|---|---|---|
| Sagicor Bank Jamaica | ▲Higher mortgage demand | ▼Commodity-style pricing |
| Borrowers seeking green homes | ▲Lower utility costs | ▼Stricter eco criteria |
| Jamaican housing market | ▲Broader financing access | ▼Slow uptake if supply is limited |
| Traditional lenders | ▲— | ▼Share in differentiated niche lending |