Sarvodaya Development Finance PLC is asking to extend by six months the deadline for deploying the proceeds from its Rs. 2 billion sustainability bond, a move that underscores how even labelled green financing can run behind schedule when project pipelines take longer to execute than planned.
Sarvodaya asks to extend sustainability bond deadline
The non-bank lender said it wrote to the Colombo Stock Exchange on Oct. 20 seeking to lengthen the original 12-month deployment window to 18 months, pushing the full investment deadline to April 17, 2027. The request matters because sustainability bonds are judged not just on how much they raise, but on how quickly and credibly the money is channelled into eligible projects. Delays can weaken issuer credibility with investors and raise questions about near-term capital allocation discipline.
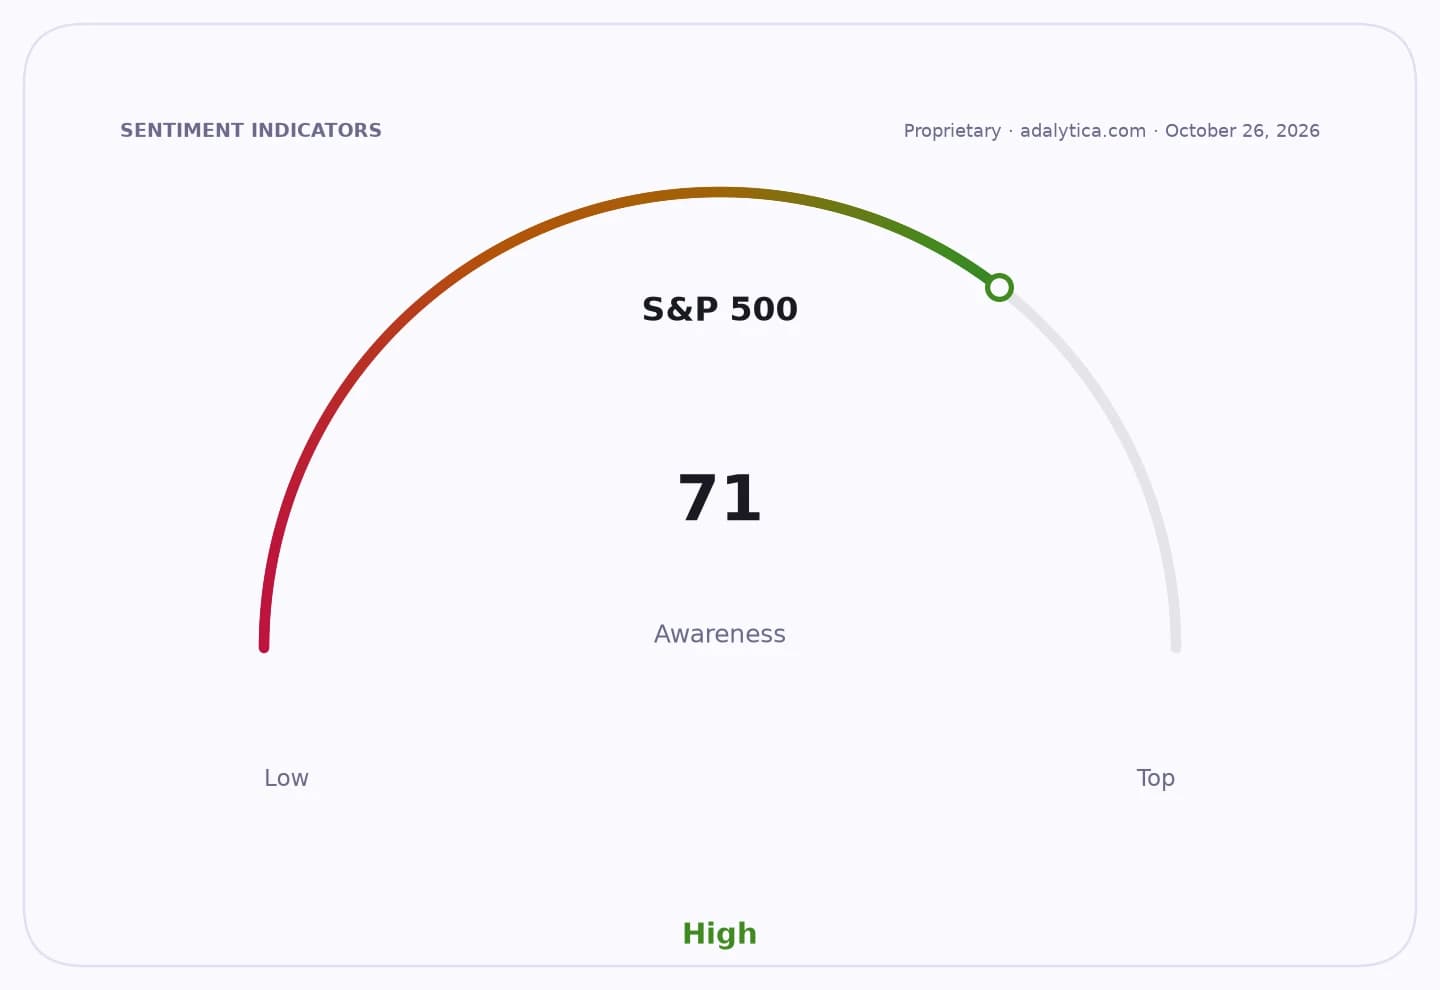
Sentiment Indicators
Under the bond’s terms, 25% of proceeds, or Rs. 500 million, were earmarked for green projects and 75%, or Rs. 1.5 billion, for social-impact projects. Sarvodaya said the social allocation has already been fully deployed, while Rs. 337 million of the green tranche still needs to be disbursed. The company said the extra time is required to ensure the funds are properly directed to the intended projects.
For investors, the immediate financial impact appears limited: the request does not imply a change to the bond’s size or coupon, but rather a timing adjustment. Still, it is a reminder that sustainability debt is increasingly scrutinised on use-of-proceeds reporting as much as on credit quality. A clean deployment record supports future issuance and pricing power; slippage can make investors more cautious, especially in smaller frontier markets where project execution risk is harder to assess.
The extension also reflects broader conditions for sustainable finance in Sri Lanka, where lenders and issuers face a thinner pipeline of bankable green investments than in larger markets. That can slow deployment even when demand for labelled funding exists. From a market perspective, the key question is whether Sarvodaya can demonstrate that the remaining green allocation is absorbed efficiently and on schedule, preserving confidence in both the bond framework and the company’s access to capital.
If approved, the revised timetable would give Sarvodaya more room to complete the remaining allocations without forcing suboptimal project selection. For bondholders, the main watchpoint is whether the delay remains a benign administrative extension or becomes a sign of weaker origination capacity in the issuer’s sustainable lending book.
| Entity | Gains | Losses |
|---|---|---|
| Sarvodaya Development Finance | ▲More time to deploy proceeds | ▼Faces closer investor scrutiny |
| Bondholders | ▲Better chance of proper allocation | ▼Wait longer for full deployment |
| Green project borrowers | ▲Additional funding runway | ▼Delayed disbursement |
| Sri Lanka sustainable finance market | ▲Preserved bond framework credibility | ▼Highlights thin project pipeline |