Saudi Arabia’s budget deficit widened sharply in the third quarter as lower oil-linked receipts left the government short of the cash needed to sustain its spending plans, underscoring how limited room Riyadh has to spend its way through a slowing fiscal cycle.
Saudi Arabia Budget Deficit Widens in Q3
The kingdom reported an 84 billion riyal deficit, or $22.38 billion, for the quarter, taking the cumulative shortfall to 230.9 billion riyals by the end of October. That is the kind of number that matters far beyond the public accounts: when the world’s biggest crude exporter leans harder on debt and reserves to bridge the gap, it has implications for domestic liquidity, bond issuance, project pacing and the broader OPEC+ calculus.
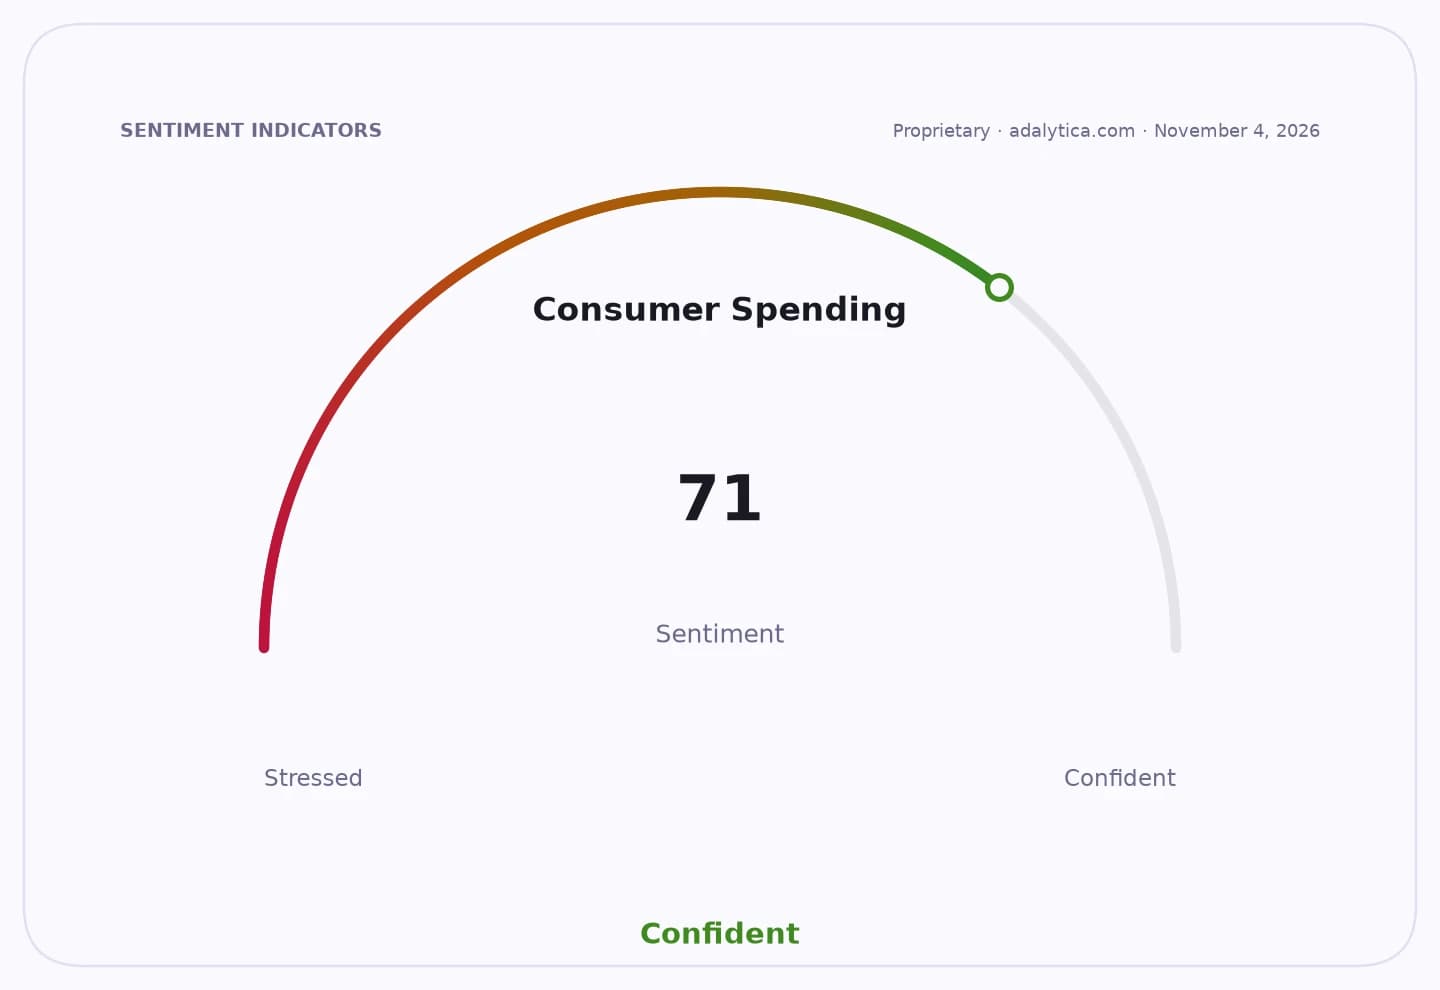
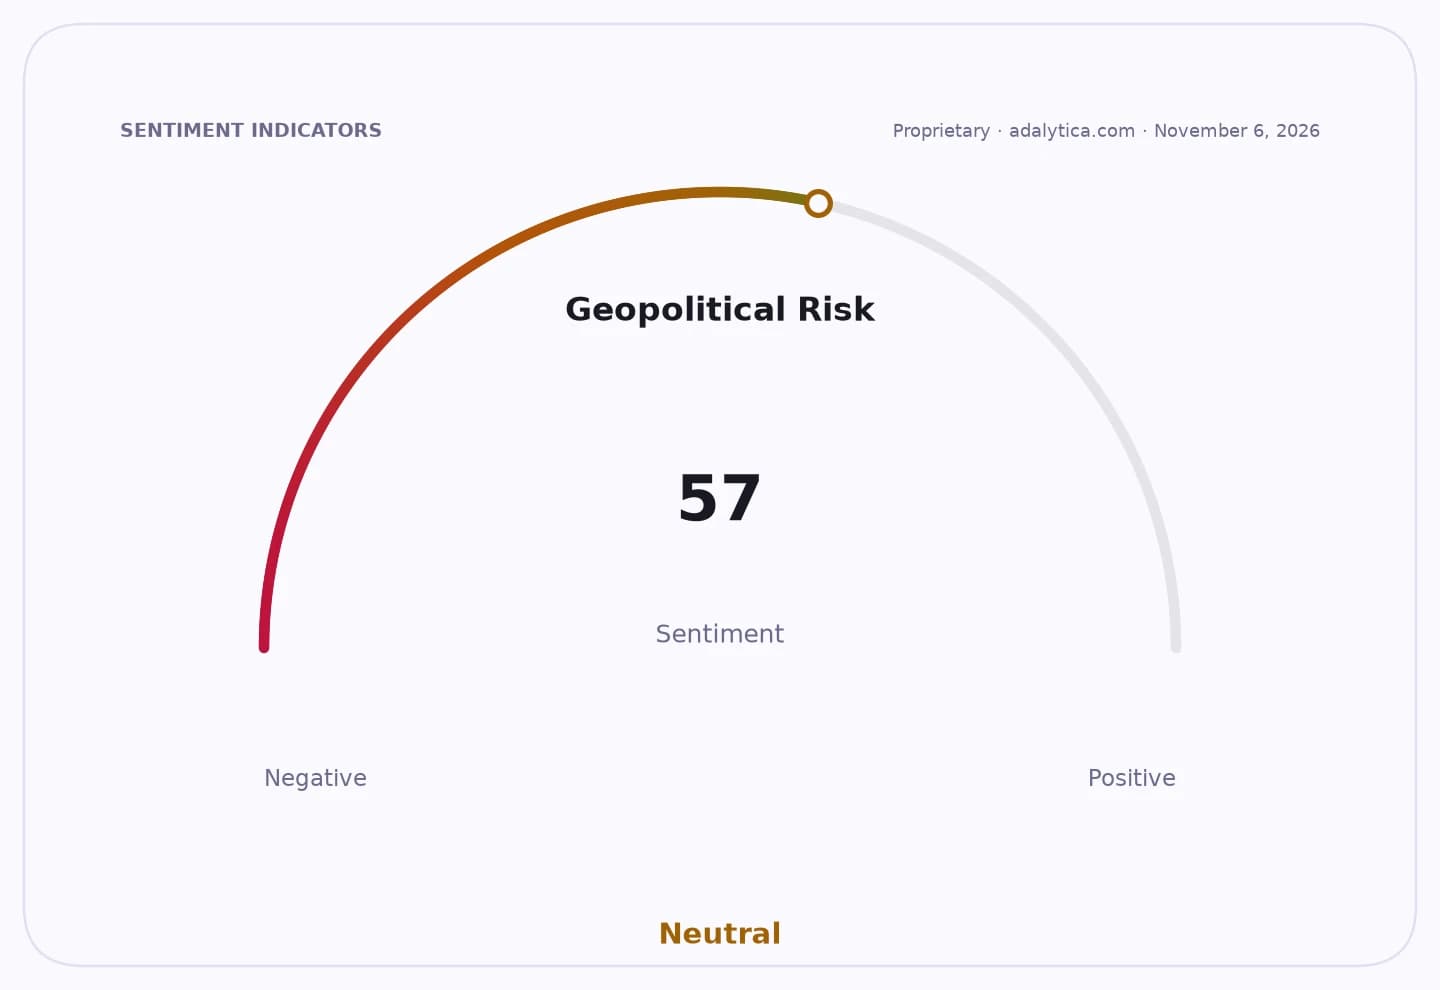
Sentiment Indicators
The fiscal strain also reinforces a key market narrative — that spending on Vision 2030 megaprojects is no longer a one-way growth story. Saudi authorities can smooth the impact in the near term, but they cannot fully offset weaker hydrocarbon income with budget outlays alone, especially if oil prices and production volumes do not rebound enough to restore balance.
For investors, the deficit matters because it raises the odds of more sovereign borrowing, tighter prioritization of capital spending and a greater push for non-oil revenue measures. That can affect Saudi debt, banks exposed to local financing demand and contractors tied to state-backed development work, while also feeding expectations around future oil policy and fiscal discipline.
The gap comes after a budget rectification that increased the nominal deficit by 3.5 billion riyals, a sign that fiscal assumptions are still moving in the wrong direction. With the October deficit already deepening the year-to-date hole, the market will be watching for whether Riyadh trims spending further, accelerates financing, or leans on higher revenues in the final stretch of the year.
| Entity | Gains | Losses |
|---|---|---|
| Saudi debt investors | ▲More sovereign issuance supply | ▼Fiscal slippage risk |
| Banks in Saudi Arabia | ▲Potential lending and underwriting volumes | ▼Slower state deposit growth |
| Contractors and project suppliers | ▲Near-term spending support | ▼Delayed project awards |
| Oil producers/OPEC+ | ▲Higher pressure for firmer prices | ▼Less fiscal room in Riyadh |