David Jones has paid its rent through September 30, giving Scentre Group a buffer of $30 million in bank guarantees even as the 188-year-old department store reportedly edges toward voluntary administration.
Scentre Group Gets $30 Million David Jones Buffer
The disclosure matters because David Jones is one of Australia’s most recognizable retail tenants and a key anchor in premium shopping centres. Scentre said it has received $45 million in gross rent from the chain in 2026, equal to about 1.8% of its total rental income, suggesting the landlord’s direct earnings hit is manageable even if the department store enters insolvency.
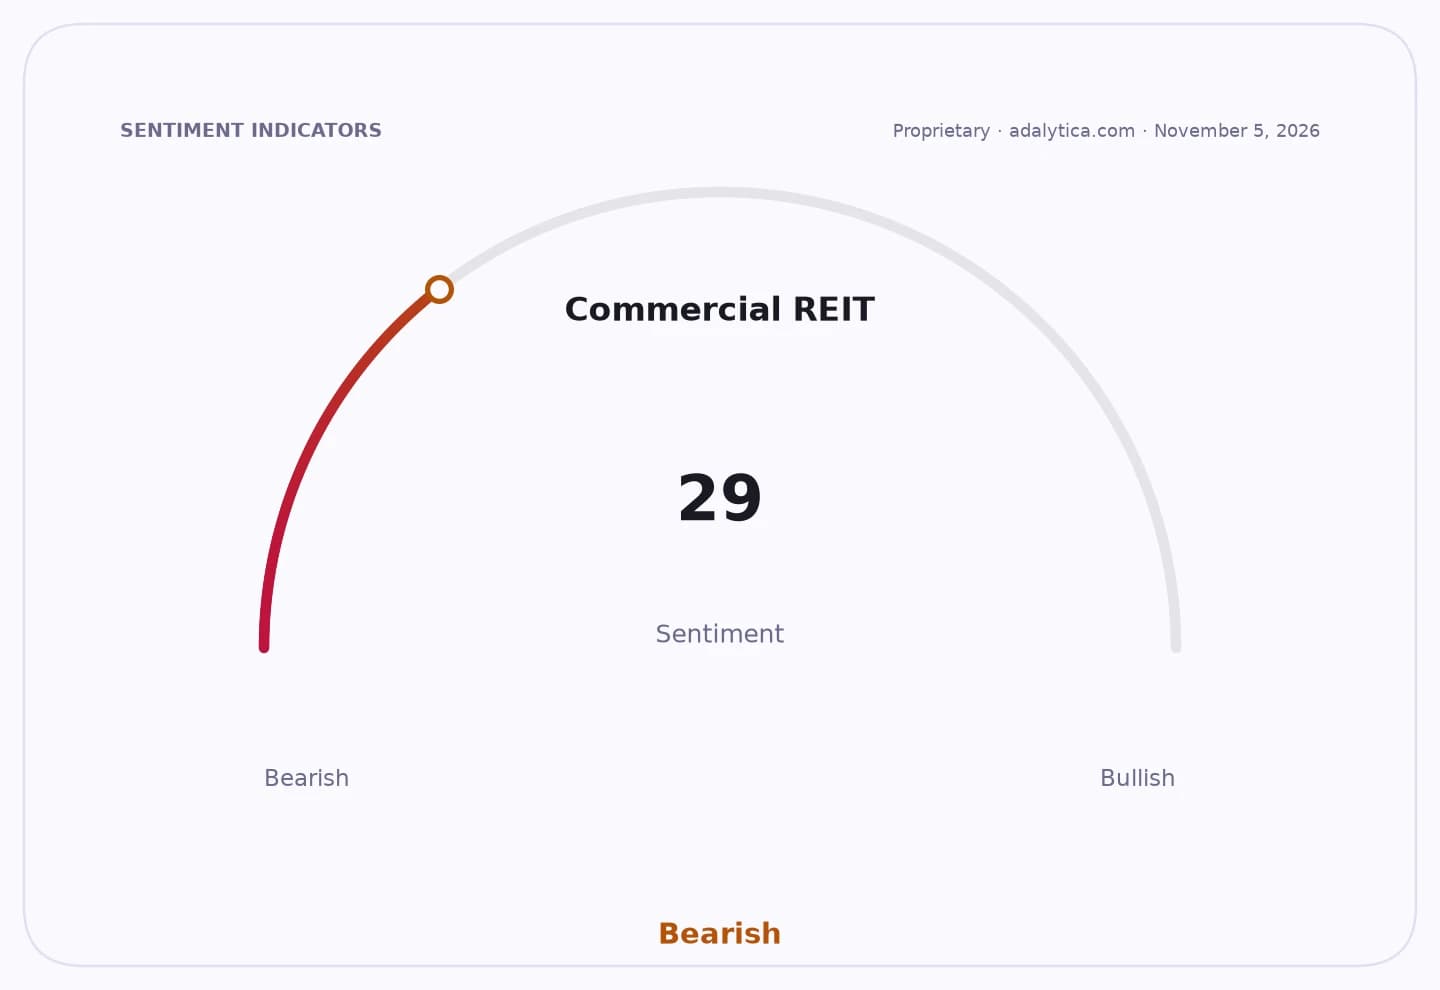
Sentiment Indicators
For investors in Scentre, the immediate takeaway is that exposure is concentrated but not existential. Seventeen of David Jones’ 38 stores across Australia and New Zealand sit in Westfield malls, including 16 in Australia and one in Auckland, so any store rationalization or administration process could still pressure occupancy, tenant mix and leasing negotiations at high-end malls.
The retailer’s position has deteriorated sharply. Australian Financial Review reported directors were expected to appoint McGrathNicol as voluntary administrators after talks with landlords broke down, while David Jones has not filed its 2025/26 accounts and posted a $95.5 million loss in 2024/25, wider than the prior year’s $74 million loss.
The collapse risk highlights the longer squeeze on bricks-and-mortar department stores from online shopping, fast fashion and low-cost imports. David Jones, which had about 6,730 employees in March, has continued operating all 38 stores, but any restructuring would test how much value remains in legacy retail brands and prime mall space.
For shareholders, the key catalyst is whether administrators keep the store network intact or force closures, leases repricing and asset sales. That decision will shape not only David Jones’ survival but also the rental outlook for Scentre and other mall landlords heading into the next round of tenancy negotiations.
| Entity | Gains | Losses |
|---|---|---|
| Scentre Group | ▲Rent collected; guaranteed cover | ▼Store-closure risk |
| David Jones | ▲Short-term trading continuity | ▼Insolvency pressure |
| Mall investors | ▲Near-term cash flow visibility | ▼Repricing risk |
| Employees and suppliers | ▲Store network may stay open | ▼Restructuring uncertainty |