Walmart’s upcoming quarterly report is expected to show another increase in revenue, but a decline in profit per share, underscoring how the world’s biggest retailer is still growing even as pricing, mix and cost pressures weigh on margins.
Walmart Earnings Seen Rising as Profit Falls
Analysts on average expect Walmart to post earnings of 63.8 cents a share for the quarter ended Oct. 31, down from 77 cents a year earlier, according to the estimates. Revenue is seen rising 4.31% to $187.24 billion from $179.50 billion. For the full fiscal year, analysts are looking for earnings of $2.89 a share on sales of $752.69 billion.
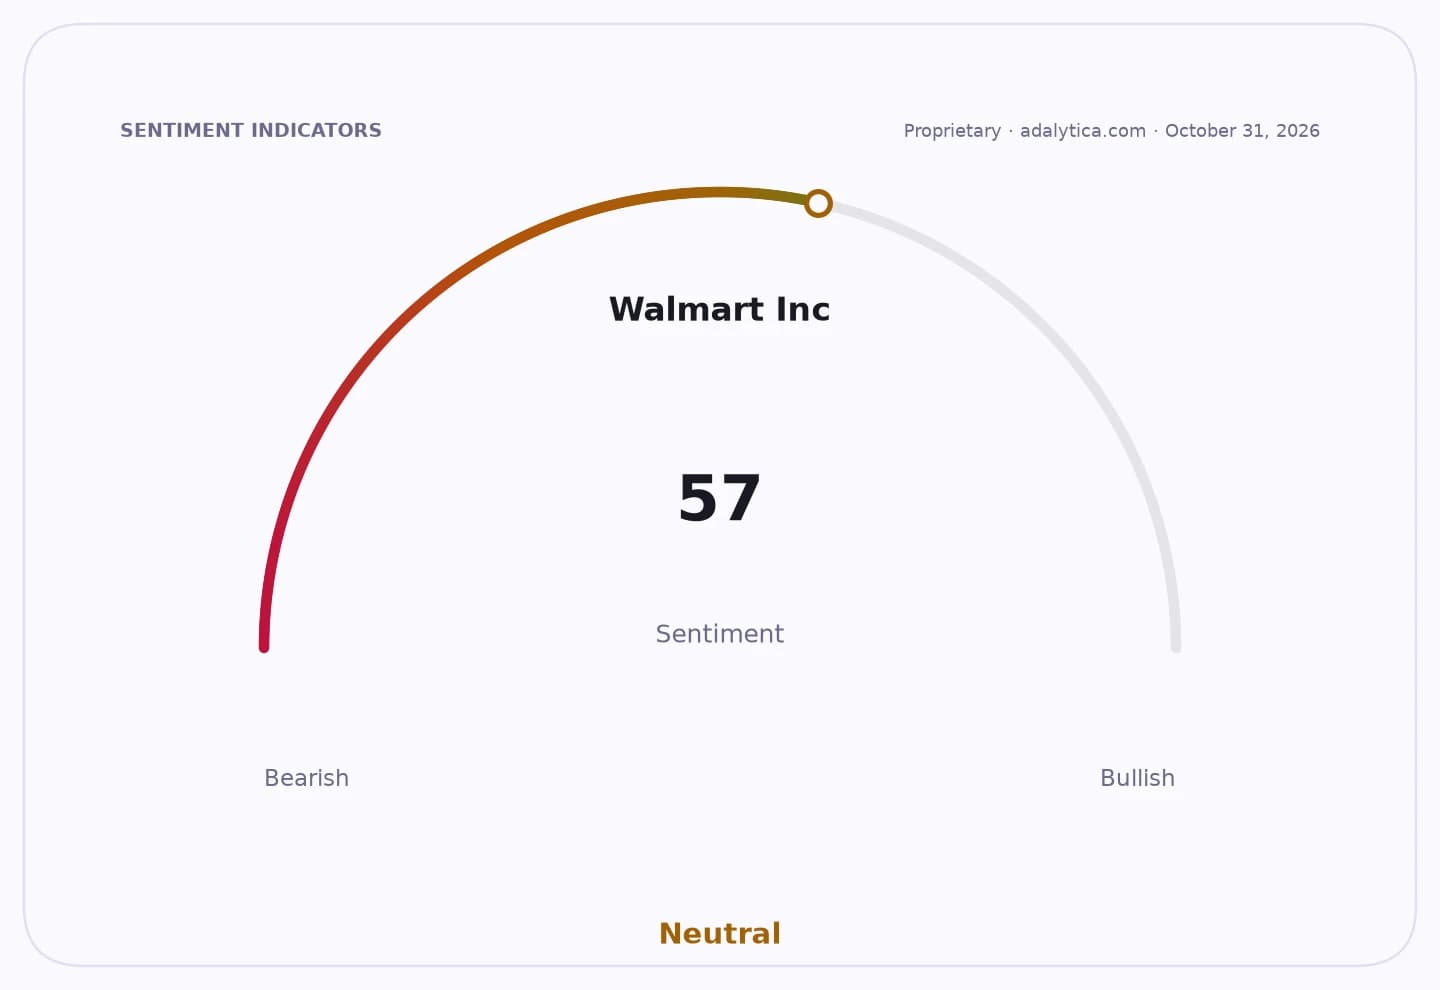
Sentiment Indicators
Walmart Inc
The numbers matter because Walmart is one of the clearest barometers of US consumer demand. Its grocery-heavy model gives it an edge when households trade down, but that same mix can cap margin expansion. A revenue gain of more than 4% would indicate the company is still taking share, helped by its scale in food, essentials and e-commerce. The weaker earnings outlook suggests that growth is coming with thinner profitability, a dynamic investors have been watching across retail as higher costs and promotional intensity offset volume gains.
Walmart shares have rallied sharply in recent months, reflecting confidence that its defensive business model can keep outperforming a stretched consumer sector. The stock closed at $126.14 on Friday, above its 200-day moving average of about $118.37, while the 50-day moving average sits near $112.49, a sign the market has already priced in substantial resilience. But the technical backdrop also shows the shares have cooled from recent highs after the RSI, a standard momentum gauge, eased from overbought levels to 64.1.
The broader retail backdrop remains mixed. Target and Costco have also shown that top-line strength does not automatically translate into margin expansion, particularly when shoppers remain price-sensitive and companies keep investing in supply chain, digital fulfillment and member loyalty. For Walmart, the key investor question is whether scale and mix can offset a softer earnings conversion rate, especially if management signals heavier spending or a more cautious consumer.
Adalytica’s Walmart Earnings Sentiment snapshot has also fallen to neutral after a sharp drop over the past day and week, reflecting a market that appears less certain heading into the print. That may prove temporary if Walmart beats expectations on traffic and same-store sales, but the setup suggests investors are focused less on revenue growth than on how much of it can reach the bottom line.
The report will therefore be judged on more than the headline EPS number. Investors will want to see whether grocery strength, marketplace growth and advertising can continue to lift sales without a further squeeze on operating margins. If Walmart can preserve that balance, it should keep extending its lead over rivals; if not, the stock’s premium valuation could become harder to defend.
| Entity | Gains | Losses |
|---|---|---|
| Walmart | ▲Revenue growth, market share | ▼Margin expansion |
| Consumers | ▲Lower prices, essentials access | ▼Less promotional room |
| Target | ▲Relative comparison opportunity | ▼Share against Walmart |
| Investors | ▲Defensive earnings visibility | ▼If profits miss estimates |