India’s market regulator has poured cold water on speculation that stock exchanges may one day be allowed to trade in their own shares, keeping a key governance safeguard intact for now.
SEBI Rejects Speculation on Exchange Self-Trading
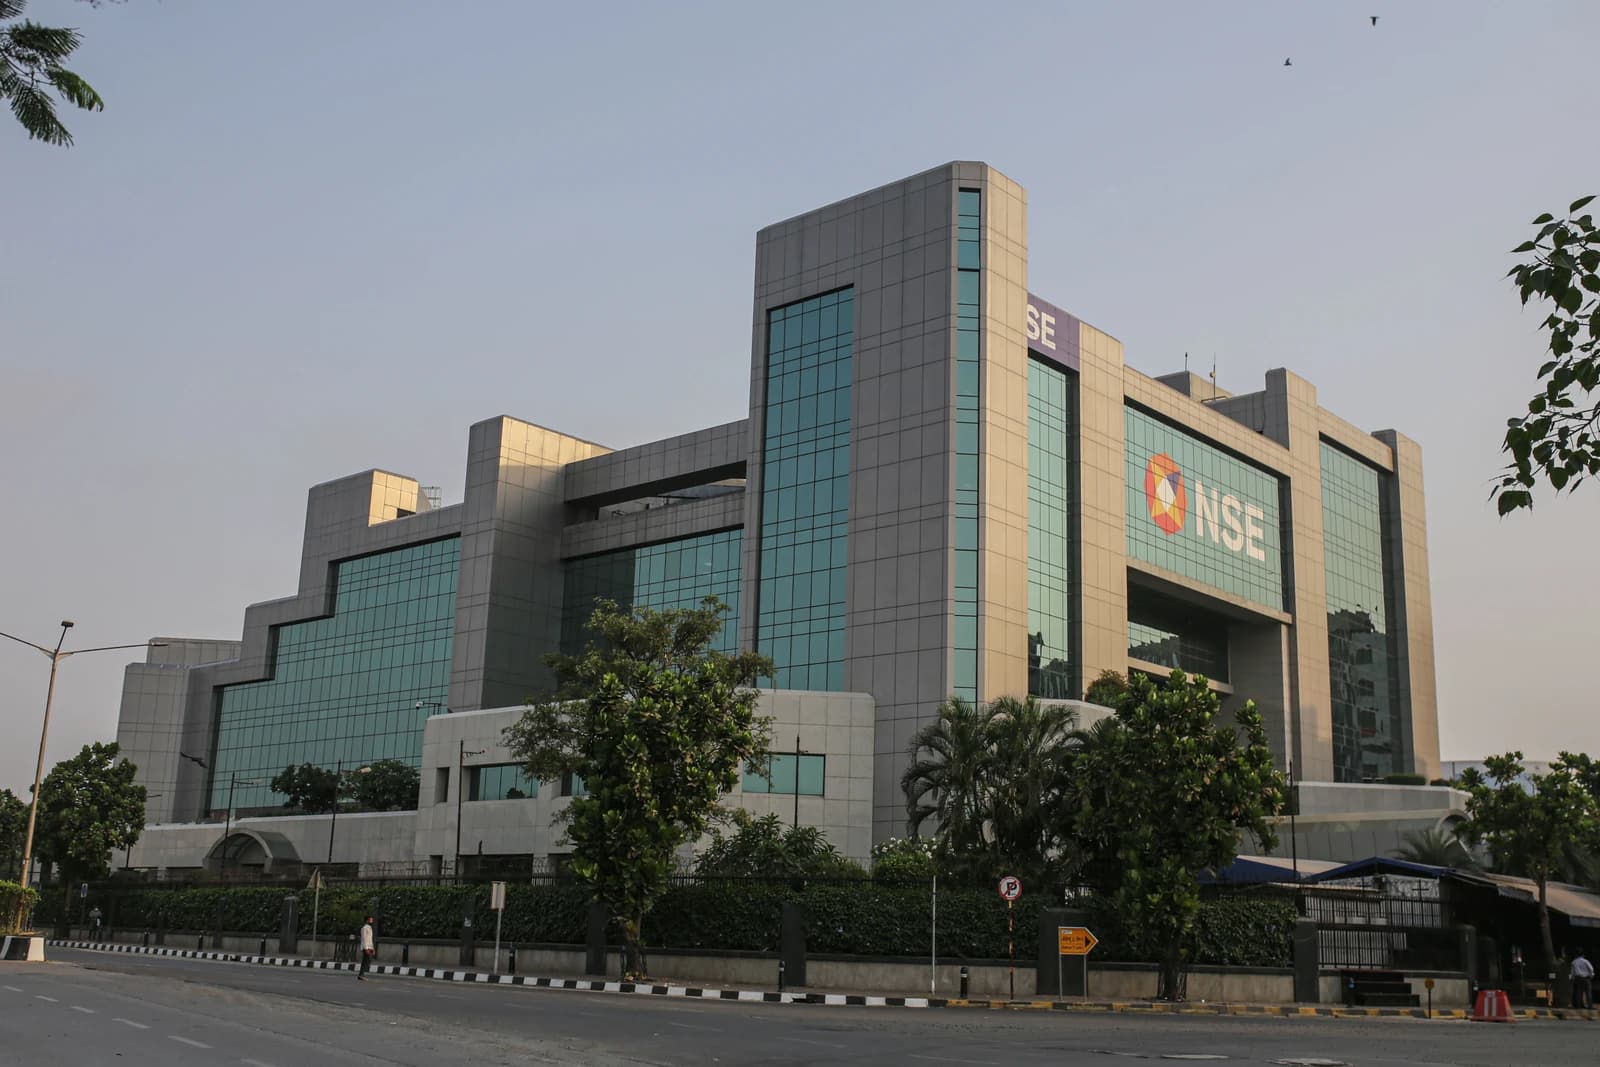
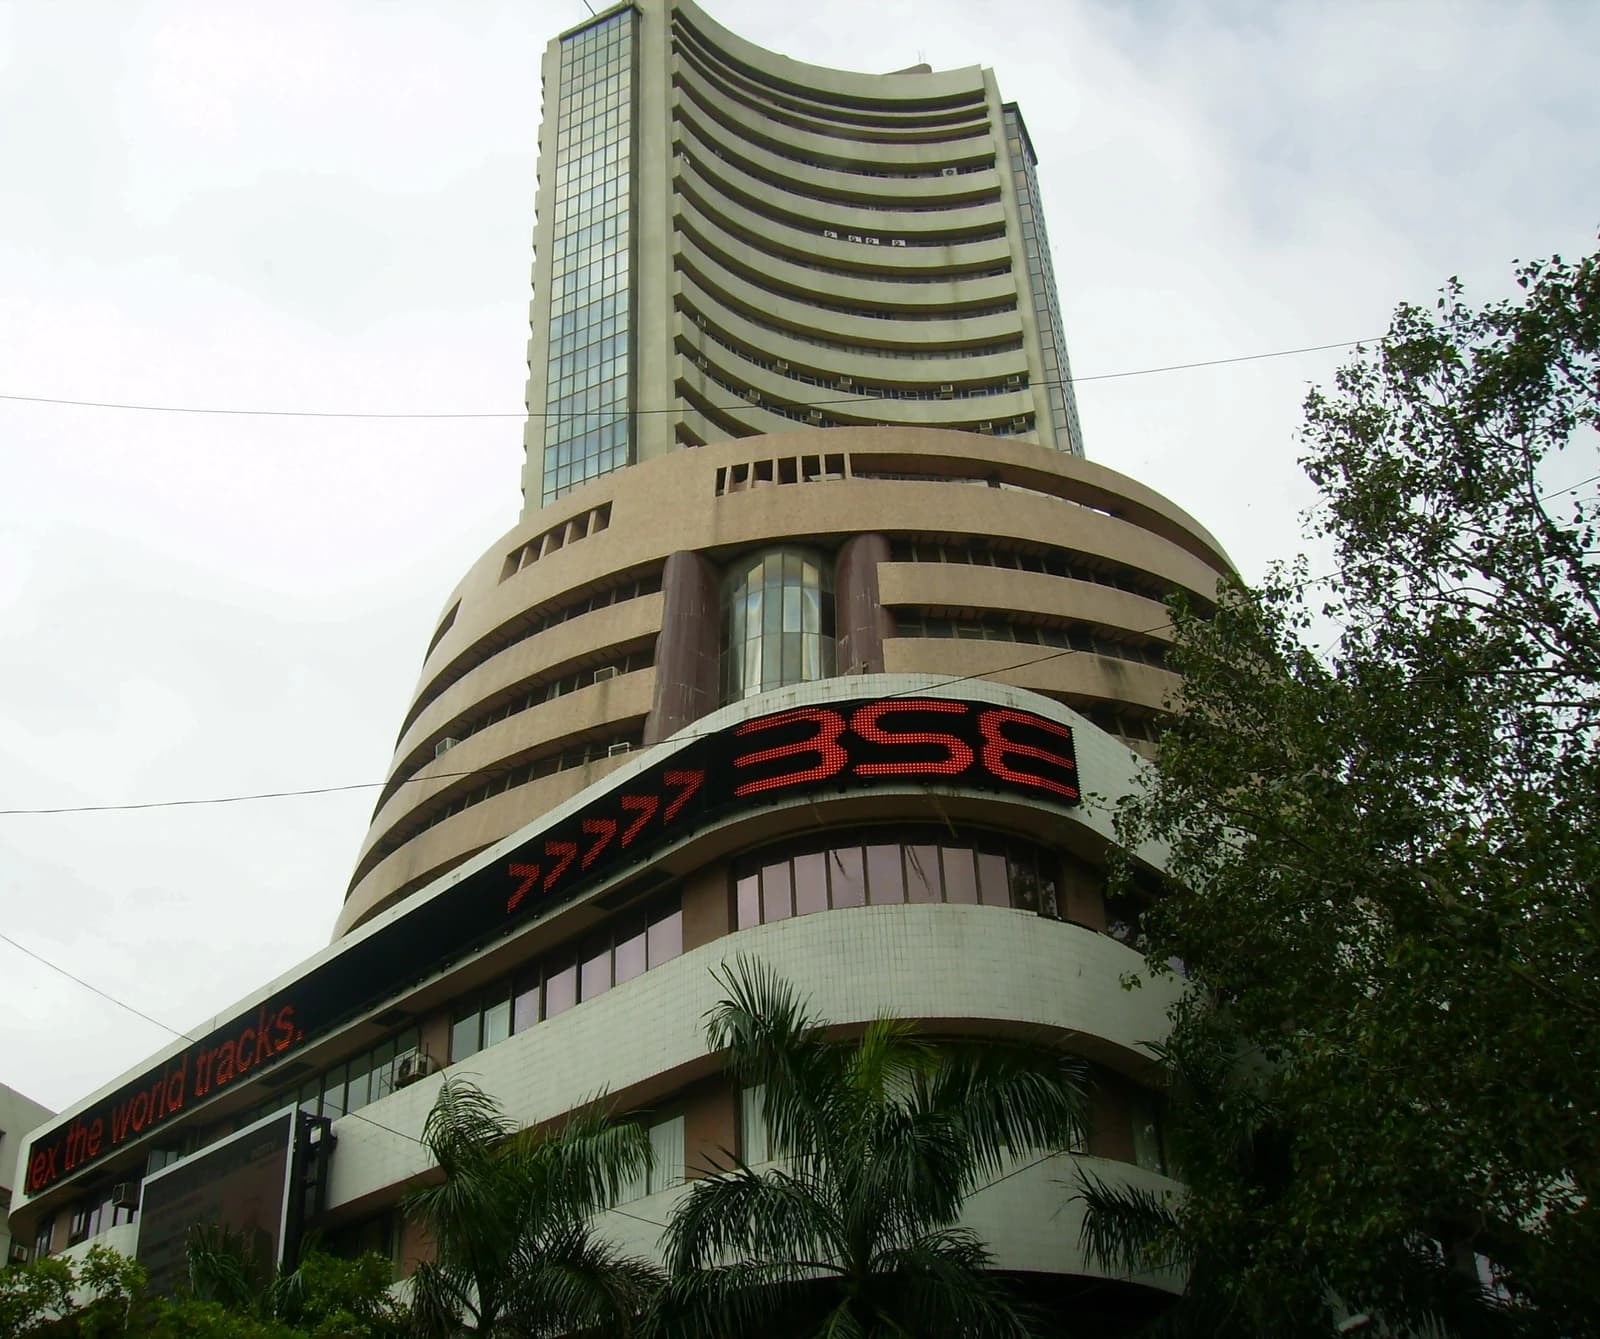
That matters because exchange ownership is not a niche regulatory detail; it goes to the heart of market integrity. If operators such as BSE and NSE were ever permitted to buy or sell their own stock, investors would immediately start asking how to separate fair price discovery from conflicts of interest. SEBI chairman Tuhin Kanta Pandey said on the sidelines of an industry conference that “nothing like this is happening” and that, if it ever does, the market will be informed. For now, the answer is no.
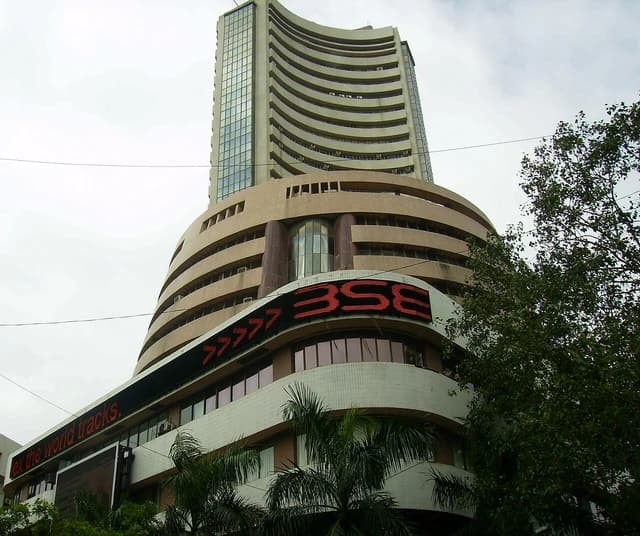
The clarification should remove at least some uncertainty for investors in listed exchange operators and for anyone weighing the long-term structure of India’s capital markets. Exchanges are already powerful toll booths on the flow of savings into equities, derivatives and listings. Allowing them to trade their own shares would have raised questions about self-dealing, governance standards and whether the rulebook was moving too fast for comfort.
Pandey’s comments also suggest SEBI is focused on more practical reforms with broader economic payoff. The regulator and the Reserve Bank of India are working to finalize guidelines on bond indices and futures and options, while also trying to make it faster and easier for foreign portfolio investors to register and start investing in India. Those steps matter more for market depth than any speculation about exchange share trading because they speak directly to liquidity, capital formation and foreign participation.
That is the real narrative here: India’s markets are still being built out, and regulators are choosing to emphasize access, digital onboarding and cleaner plumbing over experimental changes that could muddy governance. SEBI said it has already adjusted the NSDL platform, launched an “India Market Access” portal for FPI applicants and introduced a common application system that lets investors track their approvals. It is also pushing digital signatures and a smoother know-your-customer process.
For investors, the implications are straightforward. The absence of any plan to let exchanges trade their own shares reduces one potential source of regulatory risk around listed market infrastructure companies. At the same time, the bigger investment case for India’s exchange ecosystem remains tied to structural growth in trading volumes, derivatives activity and cross-border participation, not to headline-grabbing rule changes.
The likely takeaway is that SEBI wants India’s market architecture to look more investable, not more speculative. That is generally good news for long-term investors who prefer predictable rules and improving access over policy experiments. The reforms worth watching are the ones that deepen participation and broaden the capital pool.
| Entity | Gains | Losses |
|---|---|---|
| SEBI | ▲Governance credibility | ▼Speculation noise |
| BSE/NSE | ▲Clearer rulebook | ▼Optionality on self-trading |
| FPIs | ▲Faster onboarding | ▼Friction from slow approvals |
| Long-term investors | ▲Better market access | ▼Risk from opaque reforms |