Shimane Bank is raising 10 billion yen of fresh capital, and the bigger story is that SBI Shinsei Bank is stepping in as underwriter and expanding its collaboration with the regional lender.
Shimane Bank Raises 10 Billion Yen With SBI Shinsei
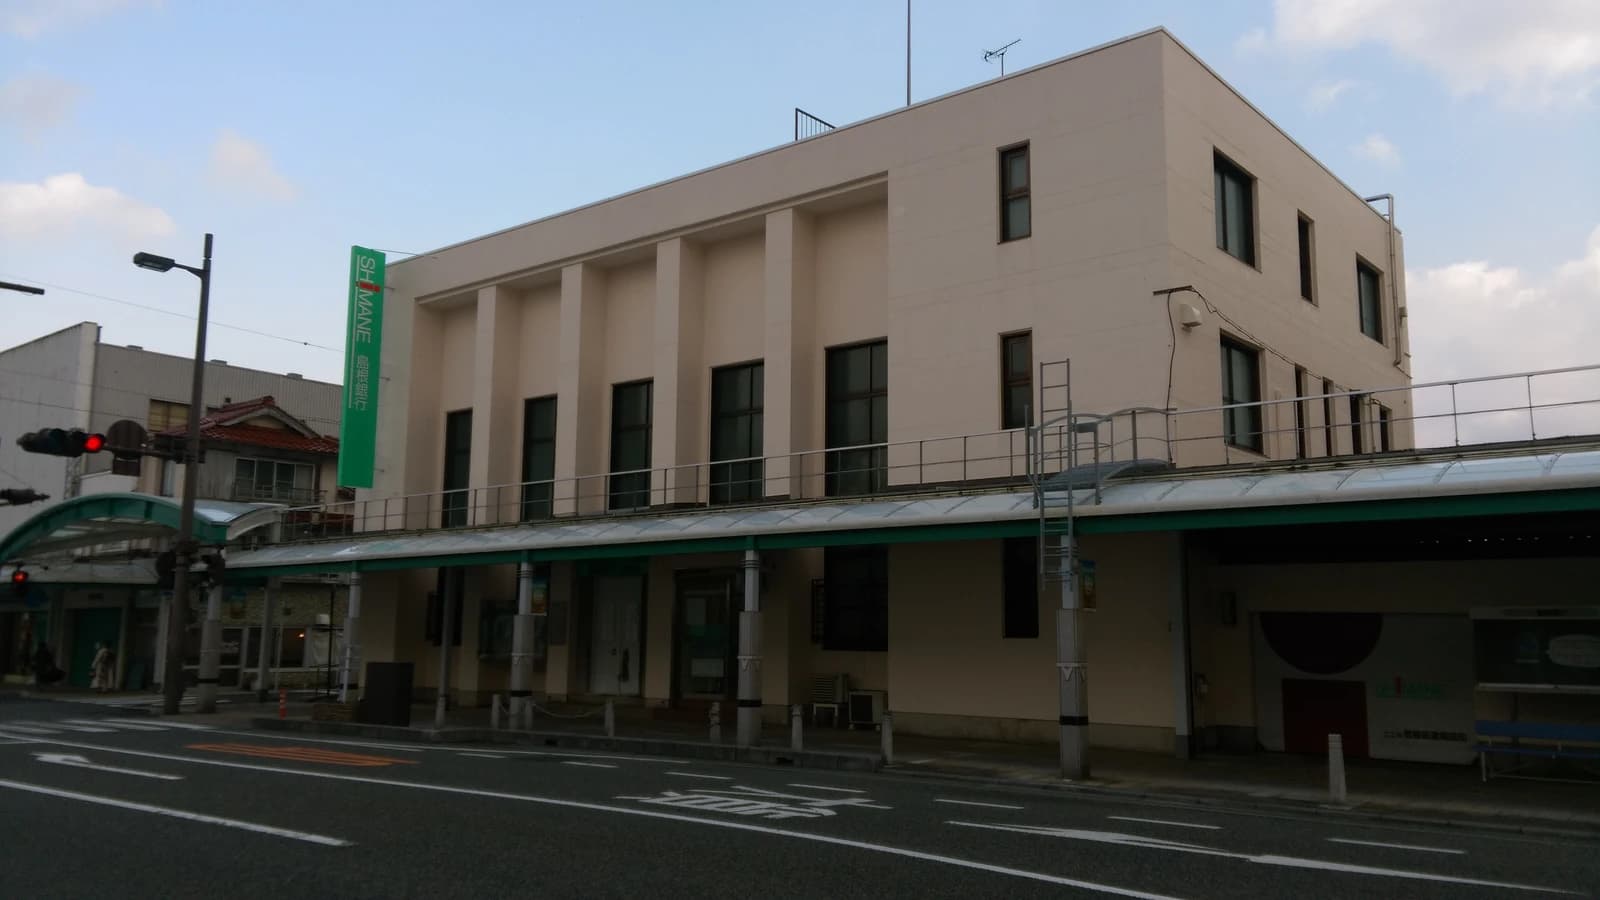
For investors, that matters because capital is the raw material of banking growth. A stronger capital base gives a regional bank more room to lend, absorb credit risk and invest in technology at a time when Japan’s local lenders are under pressure to find new sources of profitability beyond plain-vanilla deposit gathering. It also shows how Japan’s larger financial groups are moving deeper into regional finance, where scale, distribution and digital capabilities can make a meaningful difference over time.
The transaction fits a broader trend across the banking sector: institutions are trying to fortify their balance sheets so they can support lending while still meeting tighter expectations around resilience. That is especially important for regional banks, which face a structural challenge — they are expected to finance local businesses and communities, yet many of those borrowers are small firms with limited appetite for debt or uneven growth prospects.
In practical terms, the deal could help Shimane Bank widen its lending capacity and fund upgrades in areas such as systems and operations. The underwriting by SBI Shinsei Bank also points to a strategic partnership model that is becoming more common in Japanese finance, where regional lenders can tap a larger partner for capital support, product expertise and possibly new customer channels. For SBI Shinsei, the move expands its footprint in a part of the market where consolidation and collaboration may become increasingly attractive.
The underlying investment case is straightforward. A better-capitalized regional bank is usually a more durable regional bank. That does not guarantee rapid earnings growth, but it can improve balance-sheet flexibility, which is exactly what long-term shareholders want to see when the banking cycle is uncertain and loan demand is uneven. For income-focused investors, a stronger capital position can also support steadier dividends over time if credit quality holds up.
Still, investors should not confuse capital raising with an instant turnaround. Regional banks continue to face the same persistent issues: weak population trends, sluggish local demand and limited pricing power. The real test will be whether Shimane Bank can turn this capital boost into higher-quality lending, better fee income and a more efficient operating model.
For now, the message is encouraging. In a sector where scale and discipline matter more every year, this looks like a constructive step for Shimane Bank and another sign that SBI Shinsei Bank wants a bigger role in shaping Japan’s regional banking landscape. Worth watching for investors who want exposure to Japan’s financial restructuring theme over the next several years.
| Entity | Gains | Losses |
|---|---|---|
| Shimane Bank | ▲More capital, lending capacity | ▼Higher dilution risk |
| SBI Shinsei Bank | ▲Bigger regional footprint | ▼More balance-sheet exposure |
| Local borrowers | ▲Potentially easier credit access | ▼Still face strict screening |
| Existing regional rivals | ▲Sector support from consolidation | ▼Weaker relative position |