Spain’s tax authority has confirmed that people over 65 can transfer their primary home to their children without paying personal income tax, but only if the property qualifies as a habitual residence and the owner has lived there for at least three consecutive years.
Spain tax authority clarifies home transfer exemption
The clarification matters because it gives older homeowners a cleaner route to pass on housing wealth at a time when affordability remains strained, especially for younger buyers shut out of the property market. For families, it can lower the upfront tax cost of moving a home down a generation, even if it does not eliminate all taxes tied to the transfer.
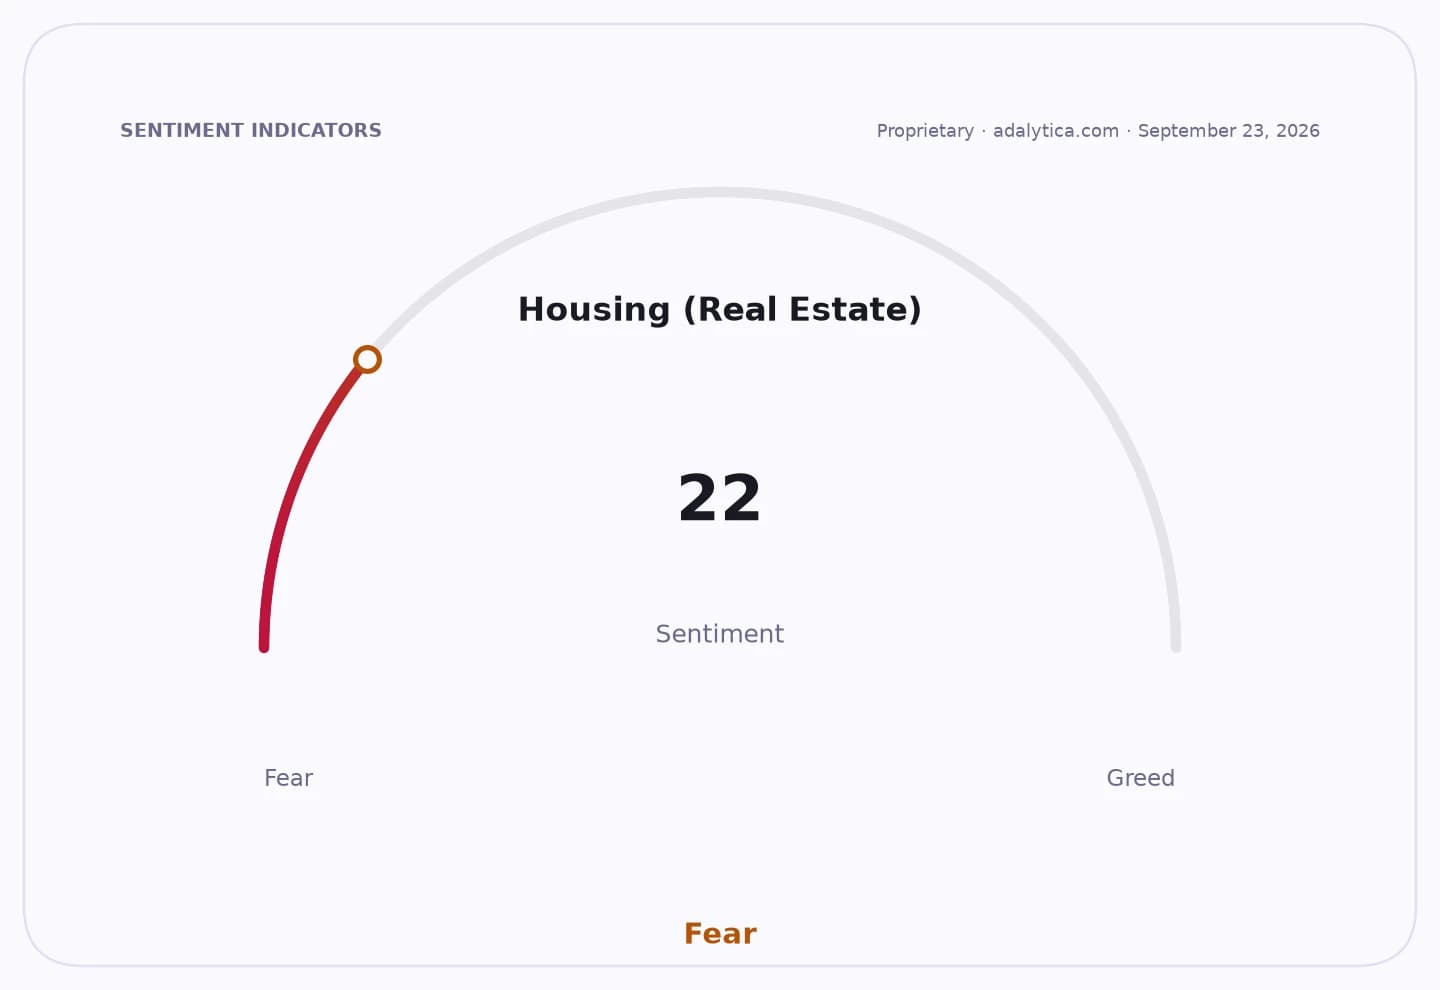
Sentiment IndicatorsⓘProprietary · adalytica.com · October 1, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The ruling, set out in a binding consultation from the Dirección General de Tributos dated July 9, says the exemption covers both full ownership transfers and gifts of bare ownership with a life usufruct reserved by the donor. It also extends to certain cases involving severe dependency, reinforcing that the key test is whether the home is the donor’s habitual residence.
That means the property must be the taxpayer’s permanent home and, in general, the owner must move in within 12 months of purchase or construction. The three-year residency requirement starts from the date of effective move-in, although exceptions apply in cases such as marriage, separation, job relocation or death.
Not every transfer qualifies. If the home is split between a bare owner and a usufructuary, neither can use the exemption, according to the tax authority. And while the donor may avoid personal income tax on the gain, the children receiving the property still have to pay inheritance and gift tax under regional rules, including potential reliefs that can be large in places such as Madrid.
For investors, the decision is less about markets than about the housing and wealth-transfer backdrop: it supports continued intergenerational movement of real estate, potentially boosting gift and succession activity among older households. It also underscores how much of Spain’s effective tax burden still depends on regional treatment, which keeps estate-planning demand high for advisers, banks and legal firms.
The next question is how widely taxpayers will use the ruling in practice and whether regional governments adjust their own inheritance tax benefits. The exemption is now clearer, but the final bill for families still depends on how the property is structured and where the heirs live.
| Entity | Gains | Losses |
|---|---|---|
| Over-65 homeowners | ▲Income tax exemption | ▼Less flexibility if residency test fails |
| Children/heirs | ▲Faster family transfer | ▼Inheritance and gift tax liability |
| Tax advisers/banks | ▲More planning demand | ▼More compliance scrutiny |
| Spanish tax authority | ▲Clearer enforcement line | ▼Less ambiguity in disputes |