Suriname is trying to convince creditors and investors that a larger oil-driven revenue stream will be enough to keep its swollen debt burden under control.
Suriname Debt Plan Relies on Future Oil Revenue
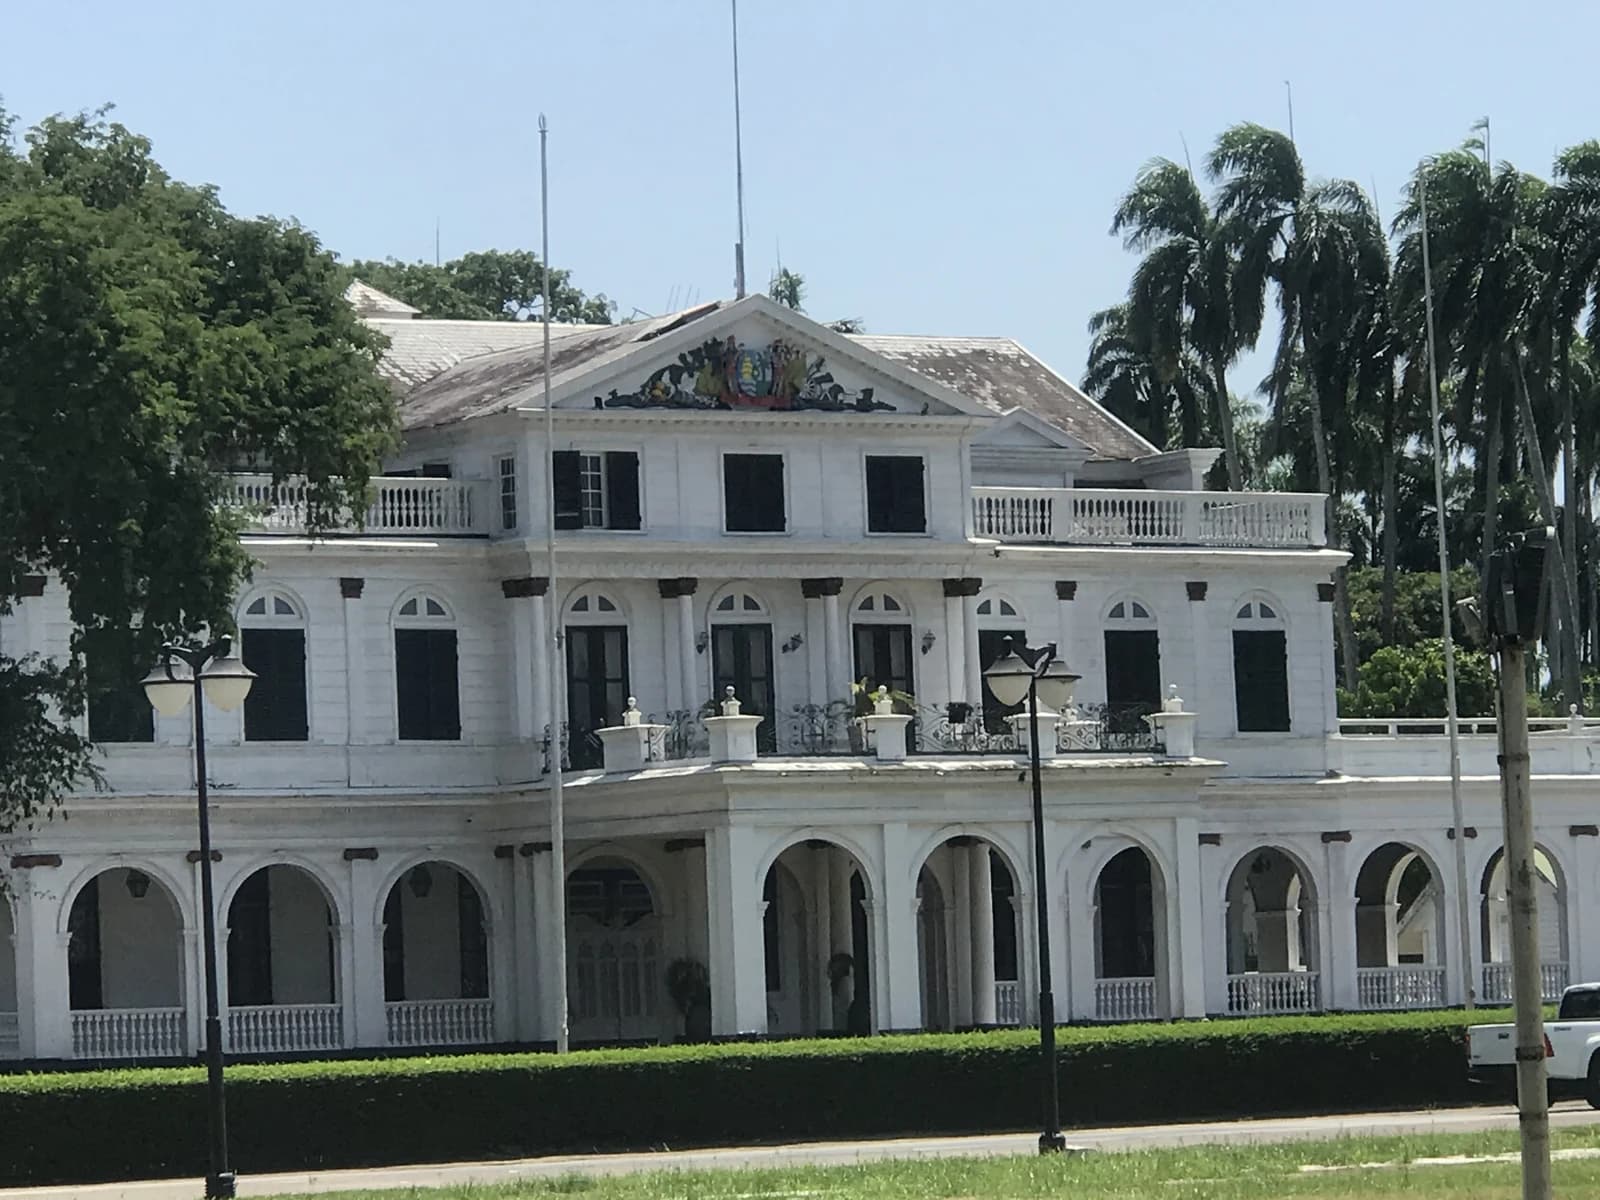
The 2027 debt plan comes as the government faces a heavy refinancing task after years of borrowing and persistent budget pressure. At the end of June 2026, public debt stood at SRD 175.3 billion, or about $4.7 billion, a level that leaves fiscal policy tightly constrained even as the country looks to eventual offshore oil income to improve repayment capacity.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 5, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
That makes the plan economically important well beyond Paramaribo. For Suriname, the issue is not simply how to pay debt back, but whether future revenue can arrive fast enough to prevent interest costs, new borrowing and rigid spending commitments from crowding out public investment. The state is effectively betting that oil receipts will expand the fiscal envelope before debt service becomes unmanageable.
For investors and lenders, the signal is mixed. On one hand, a formal debt plan is a necessary step toward preserving market access and avoiding a disorderly funding gap. On the other, the reliance on prospective oil income underlines how dependent the sovereign remains on a commodity cycle that has yet to fully materialize. Until those revenues are visible in cash flow rather than projections, debt sustainability will remain highly sensitive to execution risk, borrowing costs and spending discipline.
The broader backdrop is an environment of rising sovereign stress in smaller emerging markets, where weak buffers and narrow export bases can turn promising resource stories into refinancing risks. Suriname’s challenge is to turn oil expectations into credible fiscal capacity without adding to the debt stock faster than it can be serviced.
For now, the 2027 plan is less a solution than a bridge: it offers a framework for meeting obligations, but its success will hinge on whether oil income arrives in time and whether the government can resist the temptation to lean too heavily on new debt before that happens.
| Entity | Gains | Losses |
|---|---|---|
| Suriname government | ▲More time to stabilize finances | ▼Less room for spending |
| Creditors/lenders | ▲Clearer repayment framework | ▼Higher exposure to execution risk |
| Oil sector | ▲Stronger fiscal backing | ▼Pressure to deliver revenue quickly |
| Taxpayers/public services | ▲Potential future relief from oil income | ▼Near-term austerity and borrowing costs |