Suriname has cut roughly €500 million from its future debt bill by paying off the remainder of its Paris Club obligations ahead of schedule, a move that strengthens the country’s fiscal flexibility even if it does not reduce headline debt.
Suriname Pays Off Paris Club Debt Early
That distinction matters. For a heavily indebted sovereign, the immediate win is not just closing out an old chapter with official creditors, but lowering the total cash it will have to hand over over time. Suriname’s finance minister, Adelien Wijnerman, said the government compared the cost of paying now with the stream of repayments embedded in the restructuring deals, and found early repayment was cheaper.
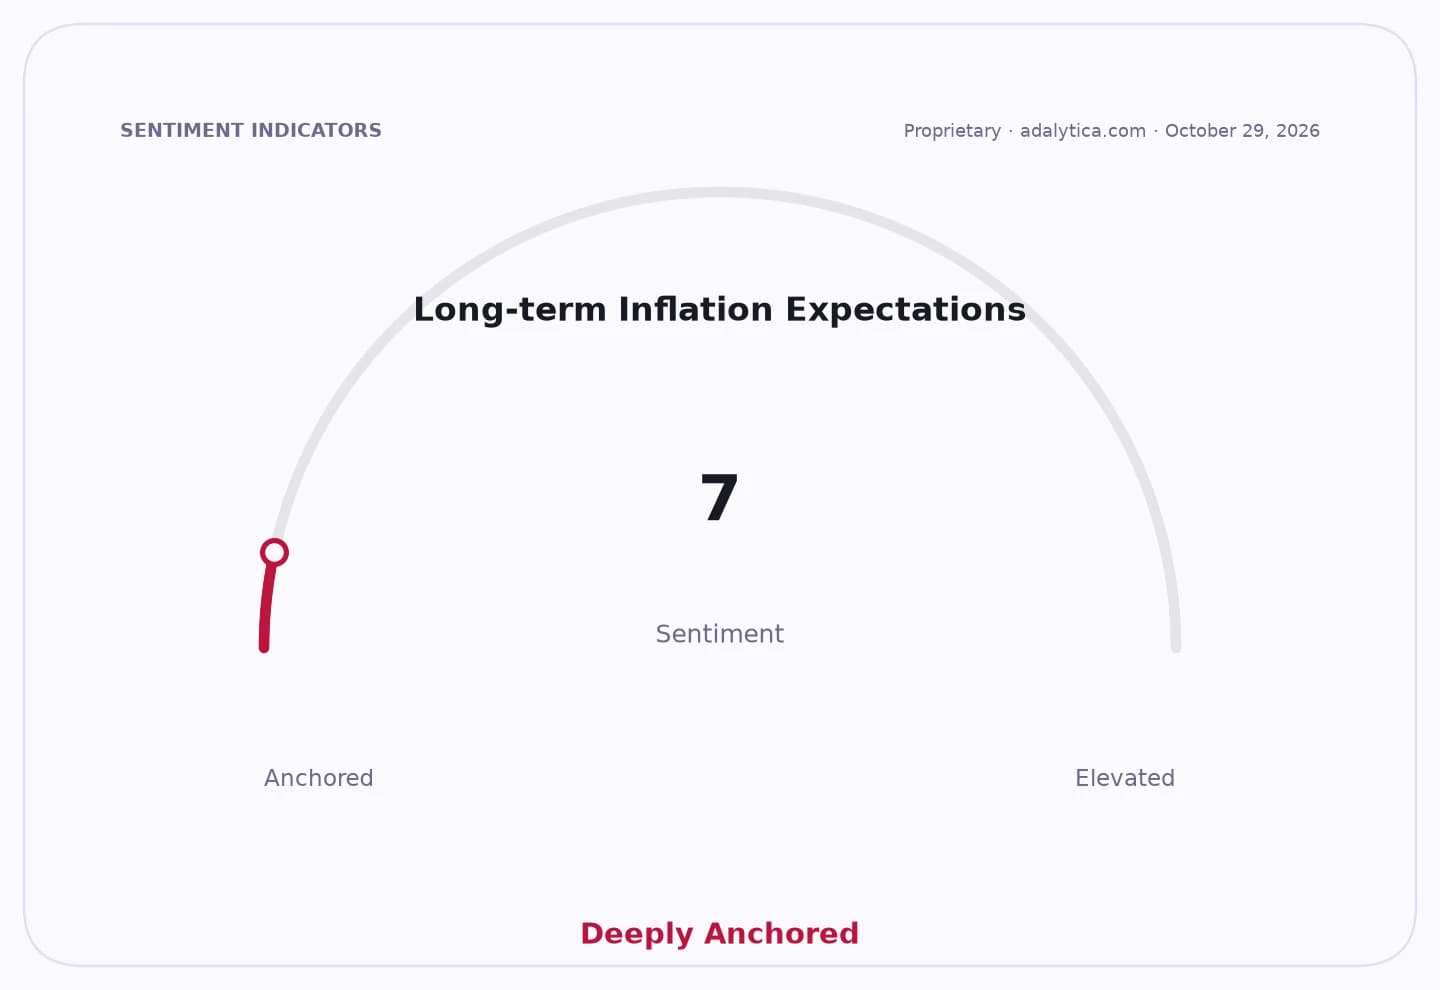
Sentiment Indicators
The government paid about €1.2 billion in May and June to settle the restructured Paris Club loans in full. Only two French loans remain outside the arrangement because new drawdowns are still taking place.
For investors, the message is that Suriname is trying to manage liabilities more actively, not simply postpone them. That is important in a country where debt sustainability has been a central concern since the 2022 restructuring deal with creditors including the Netherlands, France, Italy, Sweden and Israel. Early repayment can improve the maturity profile, reduce rollover risk and signal discipline to lenders and bondholders.
Still, this is not the same as a clean reduction in public debt. Wijnerman said the foreign loans were removed from the portfolio, but total debt did not fall structurally because new bonds issued in November 2025 and February 2026 were added to the mix. In other words, Suriname has improved the shape of its debt rather than shrinking it outright.
That makes the savings more meaningful than the accounting headline. If the government can keep financing costs lower and avoid a heavier repayment burden later, it gains room to support growth, protect reserves and reduce pressure on future budgets. For long-term investors, that is the kind of incremental improvement that can eventually matter more than a single debt stock figure.
The broader takeaway is straightforward: Suriname is using liability management to buy itself breathing room. The country is not debt-free, and it is not suddenly less levered, but it has made a costly legacy burden less expensive to service. That is worth watching closely as the next phase of its debt strategy unfolds.
| Entity | Gains | Losses |
|---|---|---|
| Suriname government | ▲€500 million savings | ▼Upfront cash outlay |
| Official creditors | ▲Early repayment certainty | ▼Future interest income |
| Bondholders/lenders | ▲Cleaner debt profile | ▼Less room for fiscal flexibility |
| Taxpayers/economy | ▲Lower long-term debt service | ▼New debt still weighs on finances |