The world’s indebted countries have finally built a club of their own, and that matters because sovereign debt workouts are getting slower, more fragmented and more expensive for everyone involved.
Borrowers Platform Could Reshape Sovereign Debt Workouts
The new Borrowers Platform, which held its first official meeting alongside the IMF and World Bank annual gatherings, is designed to give debtor nations a stronger collective voice, improve debt transparency and share expertise at a time when the traditional creditor-led system is fraying. For investors, that is not a sideshow. It goes to the heart of how distressed sovereign bonds are priced, how quickly restructurings get done and how much risk lenders demand before they extend fresh money to emerging markets.
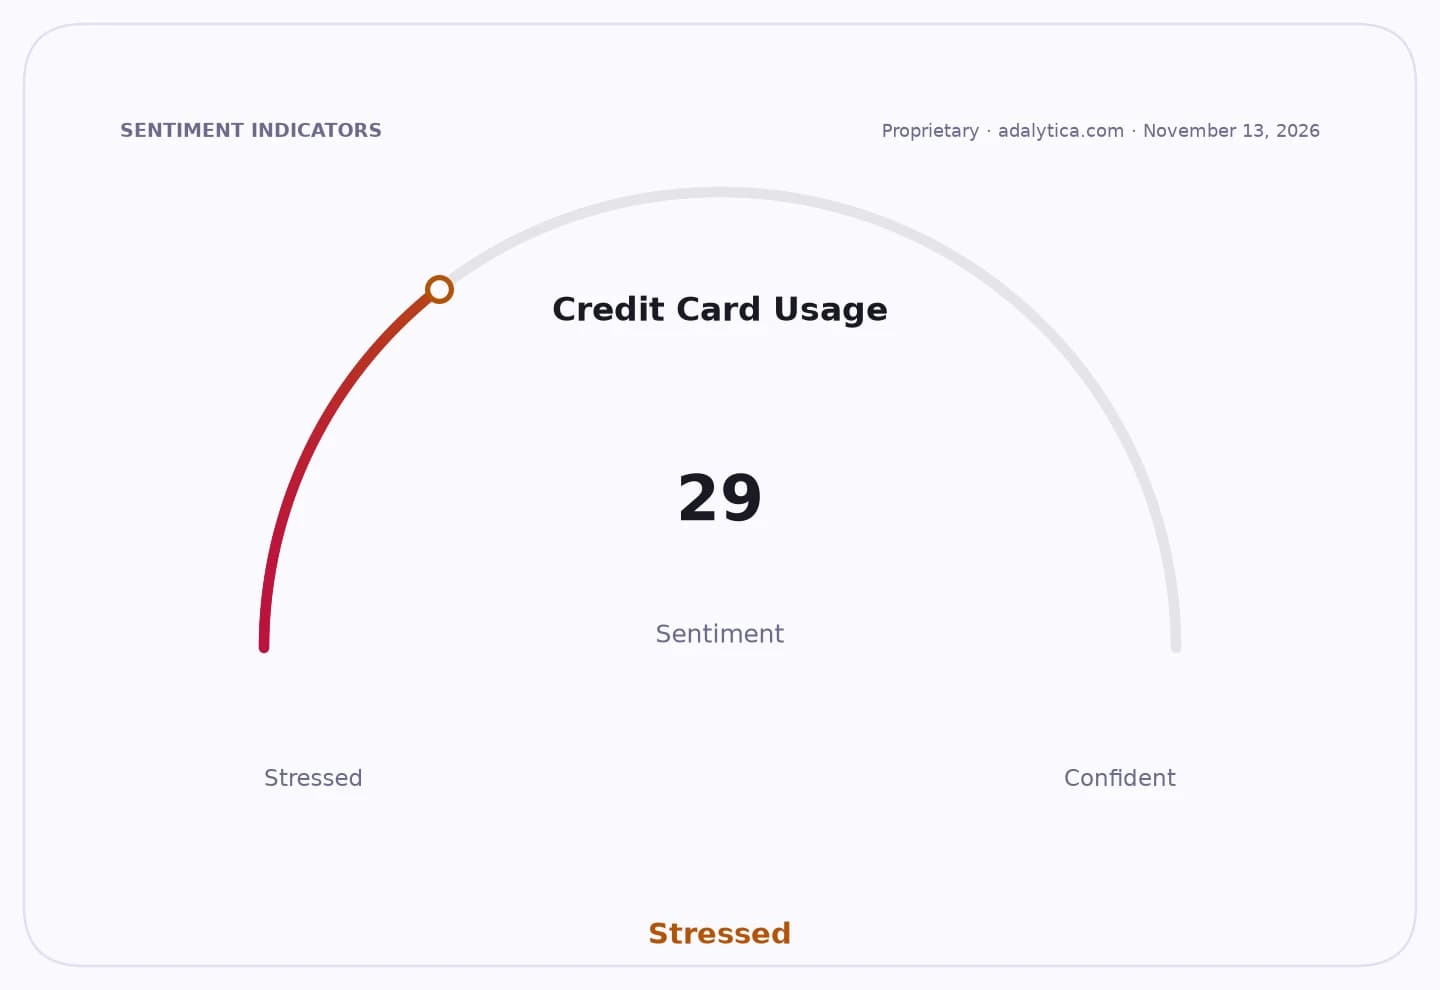
Sentiment Indicators
For decades, the Paris Club helped set the rules of the road. Its 22 permanent members coordinated official creditor responses, pushed comparable treatment across lenders and reinforced the broader architecture of the IMF’s conditional rescue model. But the credit map has changed. China’s public and private institutions now loom large in lending to developing countries, while eurobond holders, commercial banks and domestic creditors each bring different incentives and legal claims. When a country runs into trouble, those groups do not sit at one table anymore. They negotiate in separate committees, and the result has been years of drift.
Ethiopia and Zambia, two of the clearest examples, waited more than three years to reach restructuring deals. That delay is not just a diplomatic nuisance. It raises borrowing costs, delays investment and keeps economies trapped in limbo, which is bad for growth and bad for creditors who would rather see a clean restructuring than a prolonged default. The longer the process drags on, the more likely it is that recovery values erode and the more uncertainty is baked into sovereign markets.
The new platform will not have the power to impose terms the way creditor clubs once did. In fact, trying to dictate write-downs would probably backfire by forcing lenders to price in more risk. Its real value is more subtle — and potentially more durable. If debtor countries can standardize disclosure, agree to transparency on amounts and terms, and signal that they will treat creditors comparably, they may reduce the mistrust that slows restructurings today. They could also experiment with auction-style mechanisms or menus of options that make it easier for diverse creditor groups to find common ground.
That is economically important because sovereign debt markets function best when lenders believe repayment hierarchies are clear and workouts are predictable. Hidden debt, opaque collateral and unclear priority rankings distort that market, especially now that hedge funds and other aggressive investors play a bigger role in distressed sovereign paper. Better disclosure could narrow the gap between what borrowers think is fair and what creditors are willing to accept.
There is also a broader policy question behind the Borrowers Platform. The IMF and World Bank still shape the system, but the old model is under strain from great-power rivalry, climate stress and a financing need that keeps rising faster than official support. Debtor countries want reform that does not simply force austerity and contraction. They want debt sustainability frameworks that recognize investment needs and climate-related growth shocks. They also want China and Western lenders to cooperate more effectively under the G20’s Common Framework.
For investors, that means the sovereign debt trade is becoming more about process than ever. Countries that can credibly improve transparency and coordinate across creditors may regain market access faster. Those that cannot may stay stuck in restructuring purgatory, with bonds trading on legal complexity and political risk rather than fundamentals. The Borrowers Platform will not transform that reality overnight, but it is a sign that debtor nations are no longer content to let creditors write the rules alone. For long-term investors, that is worth watching closely — and keeping on the watchlist.
| Entity | Gains | Losses |
|---|---|---|
| Borrower nations | ▲Stronger voice, better coordination | ▼Less dependence on creditors |
| Paris Club creditors | ▲Clearer counterparties if talks improve | ▼Influence over restructurings |
| Sovereign bond investors | ▲More transparent debt data | ▼Higher short-term restructuring uncertainty |
| Distressed sovereigns | ▲Faster, fairer workouts if platform works | ▼Less leverage to delay talks |