Tencent Music is tapping the offshore bond market for the first time in a fresh sign that even cash-generative Chinese internet groups are choosing leverage as refinancing pressures widen. The company plans to sell about $1 billion of bonds after borrowings jumped to 13 billion yuan from zero, a material shift for a business that has long stood out for a fortress balance sheet.
Tencent Music plans $1 billion offshore bond sale
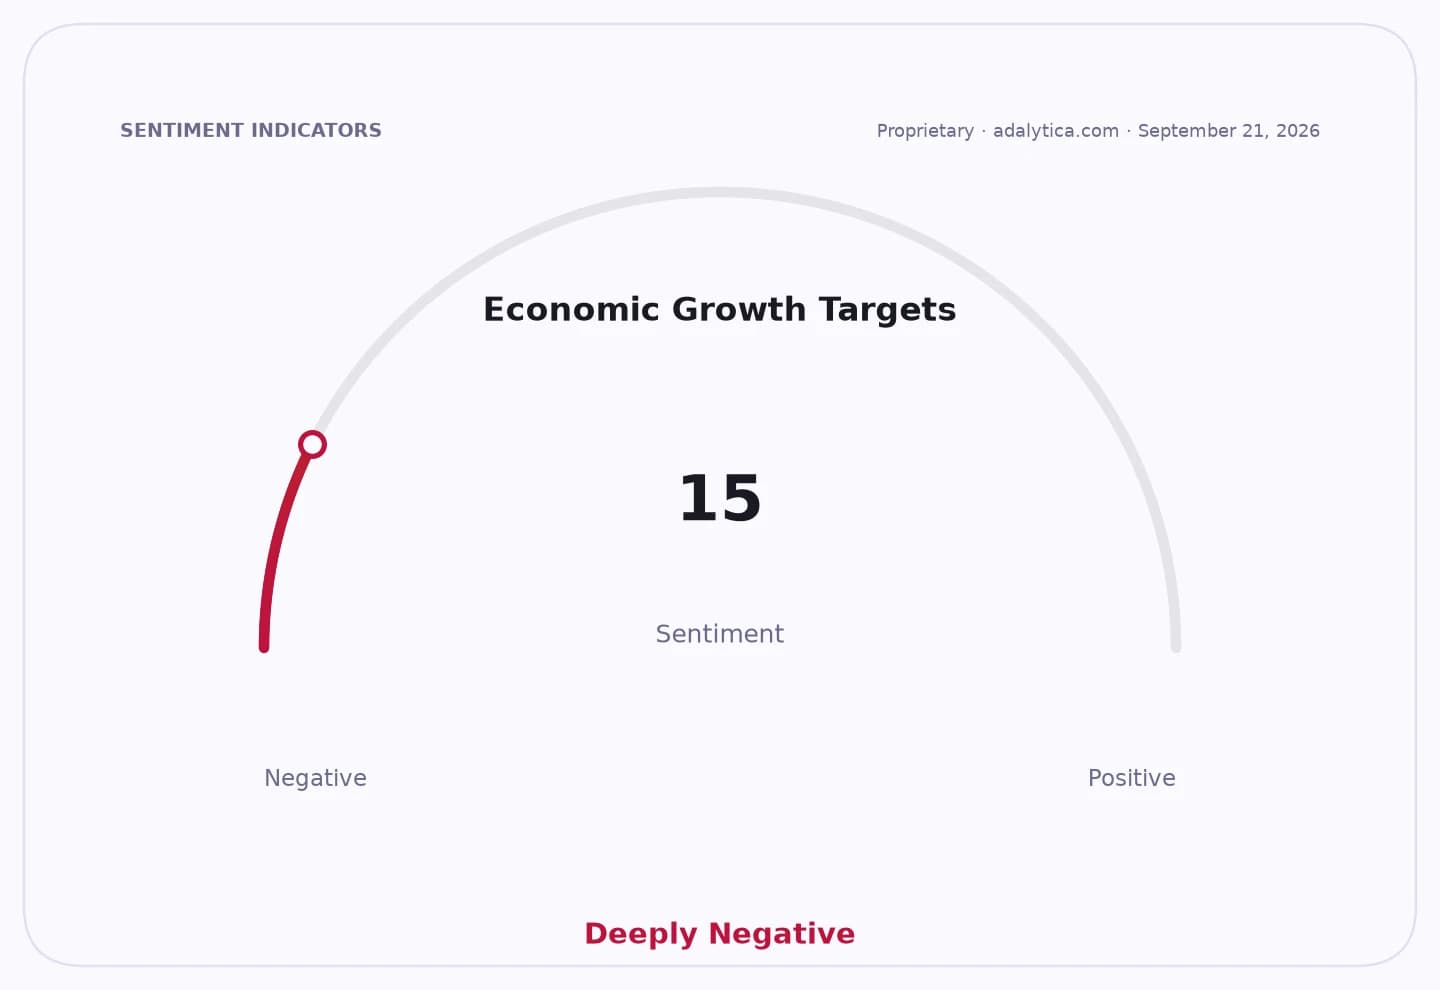
That matters because debt is no longer just a funding tool for Tencent Music — it is becoming part of the company’s capital structure at a time when Chinese borrowers face tighter financing conditions, a weaker yuan and a more selective pool of international buyers. The move comes as Adalytica’s Chinese yuan trade signals show extreme fear, underscoring how currency stress can quickly raise the cost of overseas funding for mainland-linked issuers.
For investors, the issue is less about whether Tencent Music can access capital and more about what it is choosing to do with that access. A company that once carried no borrowings is now willing to raise a large offshore slug of debt, suggesting management sees opportunity to preserve flexibility, fund expansion or refinance ahead of more expensive windows. That can be smart capital allocation, but it also changes the equity story: balance-sheet strength is no longer a clean bullish argument.
The broader market message is that Chinese credit is normalizing in a very uneven way. Stronger names can still borrow, but they are doing so against a backdrop of higher global rates, currency volatility and investor skepticism toward China exposure. In that setting, offshore bonds become both a financing avenue and a confidence test, with pricing likely to reflect not just Tencent Music’s fundamentals but the market’s view of Chinese risk more broadly.
Tencent Music’s share price has already reflected that tension. The stock has been under pressure, trading well below its 200-day moving average and hovering near the lower end of its recent range, while RSI readings have stayed weak, a sign that sentiment remains fragile even before any new debt is priced. For equity holders, the key question is whether the bond sale funds growth that reaccelerates the business or merely adds leverage to a still-soft valuation.
Our thesis is that this is the kind of move investors should watch closely across China’s internet and consumer sectors: companies with real cash flow are increasingly being forced to become capital market tacticians. The winners will be firms that borrow cheaply, deploy well and protect margins; the losers will be those that use new debt simply to stay afloat.
For now, Tencent Music looks more like a liquidity opportunist than a distressed borrower. But once a zero-debt company starts relying on the bond market, the hurdle for sustained equity rerating gets higher, not lower.
| Entity | Gains | Losses |
|---|---|---|
| Tencent Music | ▲Funding flexibility | ▼Clean balance-sheet premium |
| Bond investors | ▲New yield opportunity | ▼China currency risk |
| Existing shareholders | ▲Near-term liquidity support | ▼Higher leverage risk |
| Rival cash-rich peers | ▲Relative balance-sheet advantage | ▼Tencent Music’s capital access |