Government Savings Bank has drawn 80,000 teacher and education-worker loan accounts into its debt-relief program in just 11 days, a sign that household borrowing stress is still acute and that borrowers are aggressively trying to redirect repayments into principal rather than interest.
Thailand GSB debt relief draws 80,000 teacher borrowers
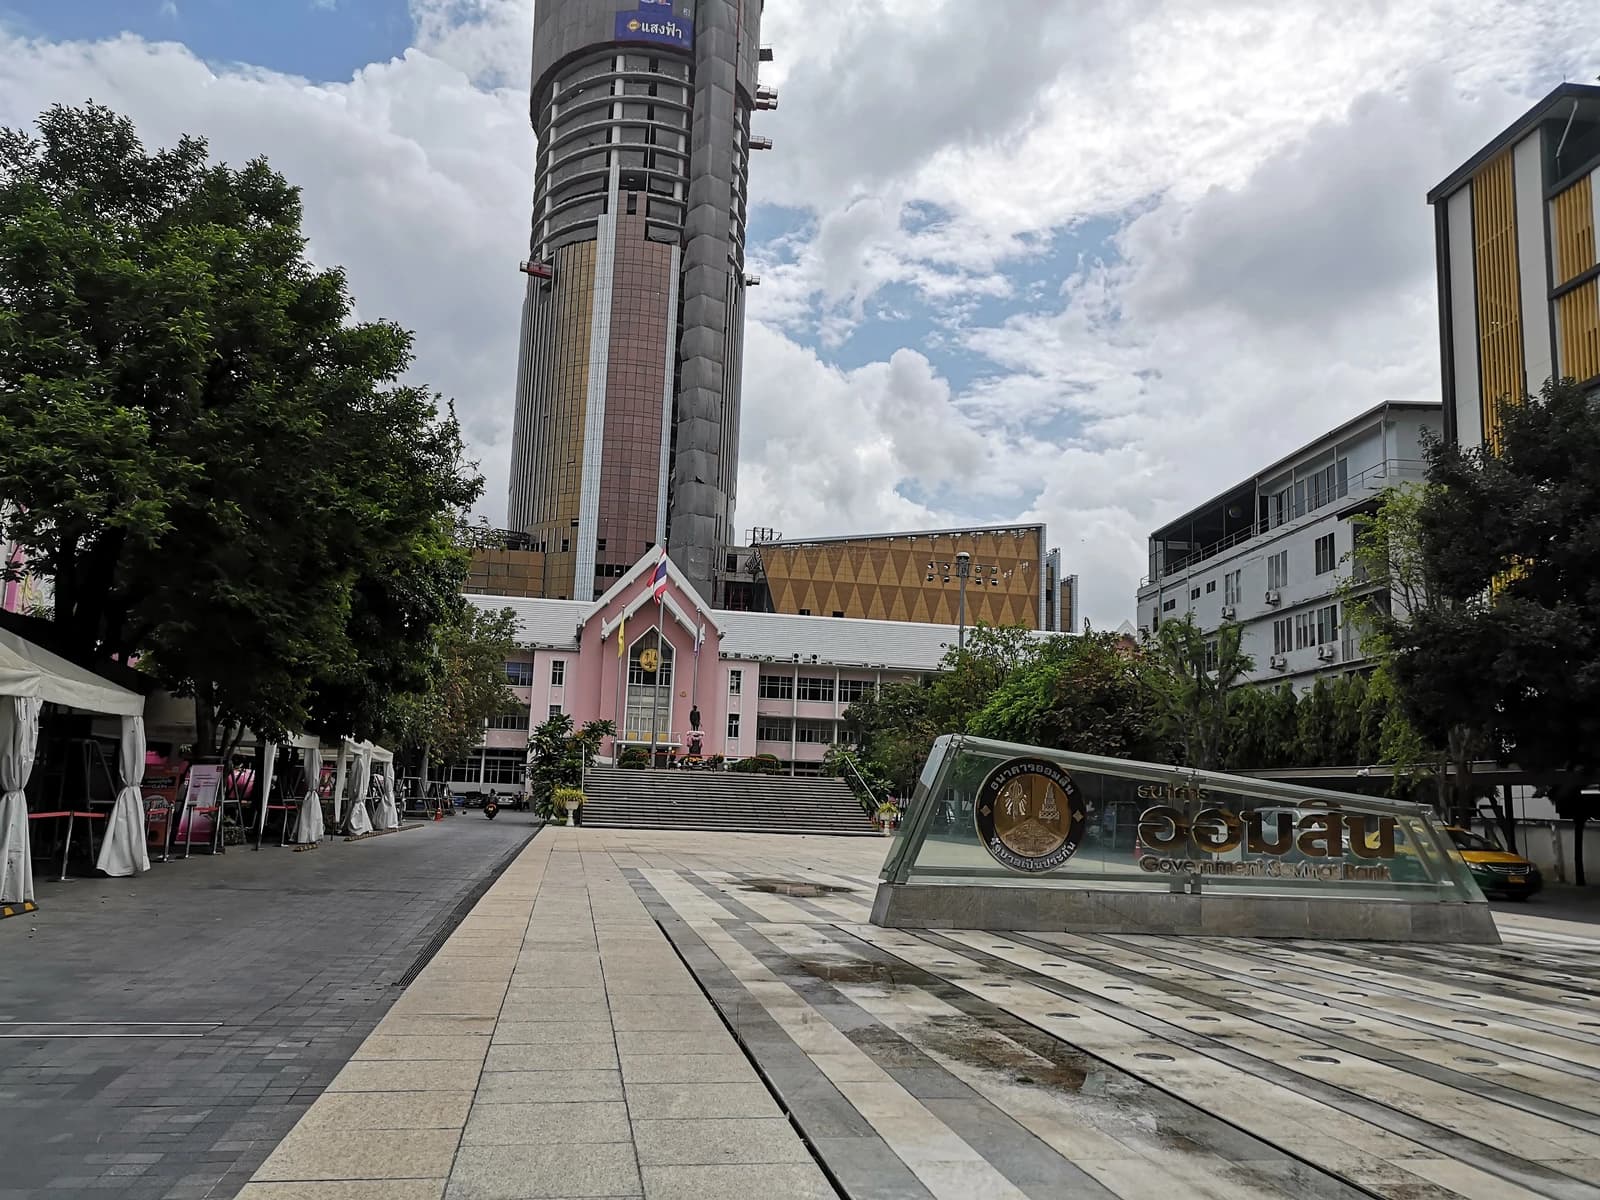
That matters because the Thai lender is effectively giving a broad class of public-sector borrowers a cheaper runway to de-lever without writing off debt. By trimming the rate to 3.50% a year through December 2027, while keeping monthly installments unchanged, the bank is helping members of the teacher pension and welfare loan schemes accelerate principal reduction and shorten repayment periods. For indebted households, that is the difference between rolling debt over and actually escaping it. For the broader economy, it is a quiet but meaningful attempt to stabilize consumer finances before arrears become a bigger drag on spending.
The program covers more than 280,000 accounts across the teacher welfare schemes launched between 2005 and 2015, and the bank is still accepting registrations until Oct. 31, 2026. Borrowers who have lost eligibility can rejoin under the national education office’s rules, while those needing debt restructuring can still qualify if they normalize their accounts by December 2026. From January 2028, the rate resets to MLR/MRR minus 2%, based on the original contract.
For investors, the message is broader than one bank’s lending campaign. Thailand’s household debt overhang remains one of the region’s most persistent structural drags, and any initiative that speeds up principal repayment can ease default risk, support bank asset quality and preserve disposable income over time. That helps lenders with large retail books, but it also underscores how fragile consumer demand remains. If households need subsidized rates simply to get back on track, the economy is still operating with limited balance-sheet room.
The market should read this as another sign that credit quality management, not rapid loan growth, will drive the next phase for Thai financials. Banks with disciplined underwriting and exposure to secured or salary-linked borrowers are better positioned than institutions chasing volume. The real opportunity is in lenders and payment rails that benefit from a more orderly de-leveraging cycle, while policymakers continue to lean on targeted relief to prevent a deeper household debt trap.
| Entity | Gains | Losses |
|---|---|---|
| Government Savings Bank | ▲Lower credit risk | ▼Forgone interest income |
| Teacher borrowers | ▲Faster principal reduction | ▼Less cash flexibility |
| Thai banks with salary-linked lending | ▲Better asset quality | ▼Slower loan growth |
| Indebted households broadly | ▲Debt relief model | ▼Evidence of financial stress |