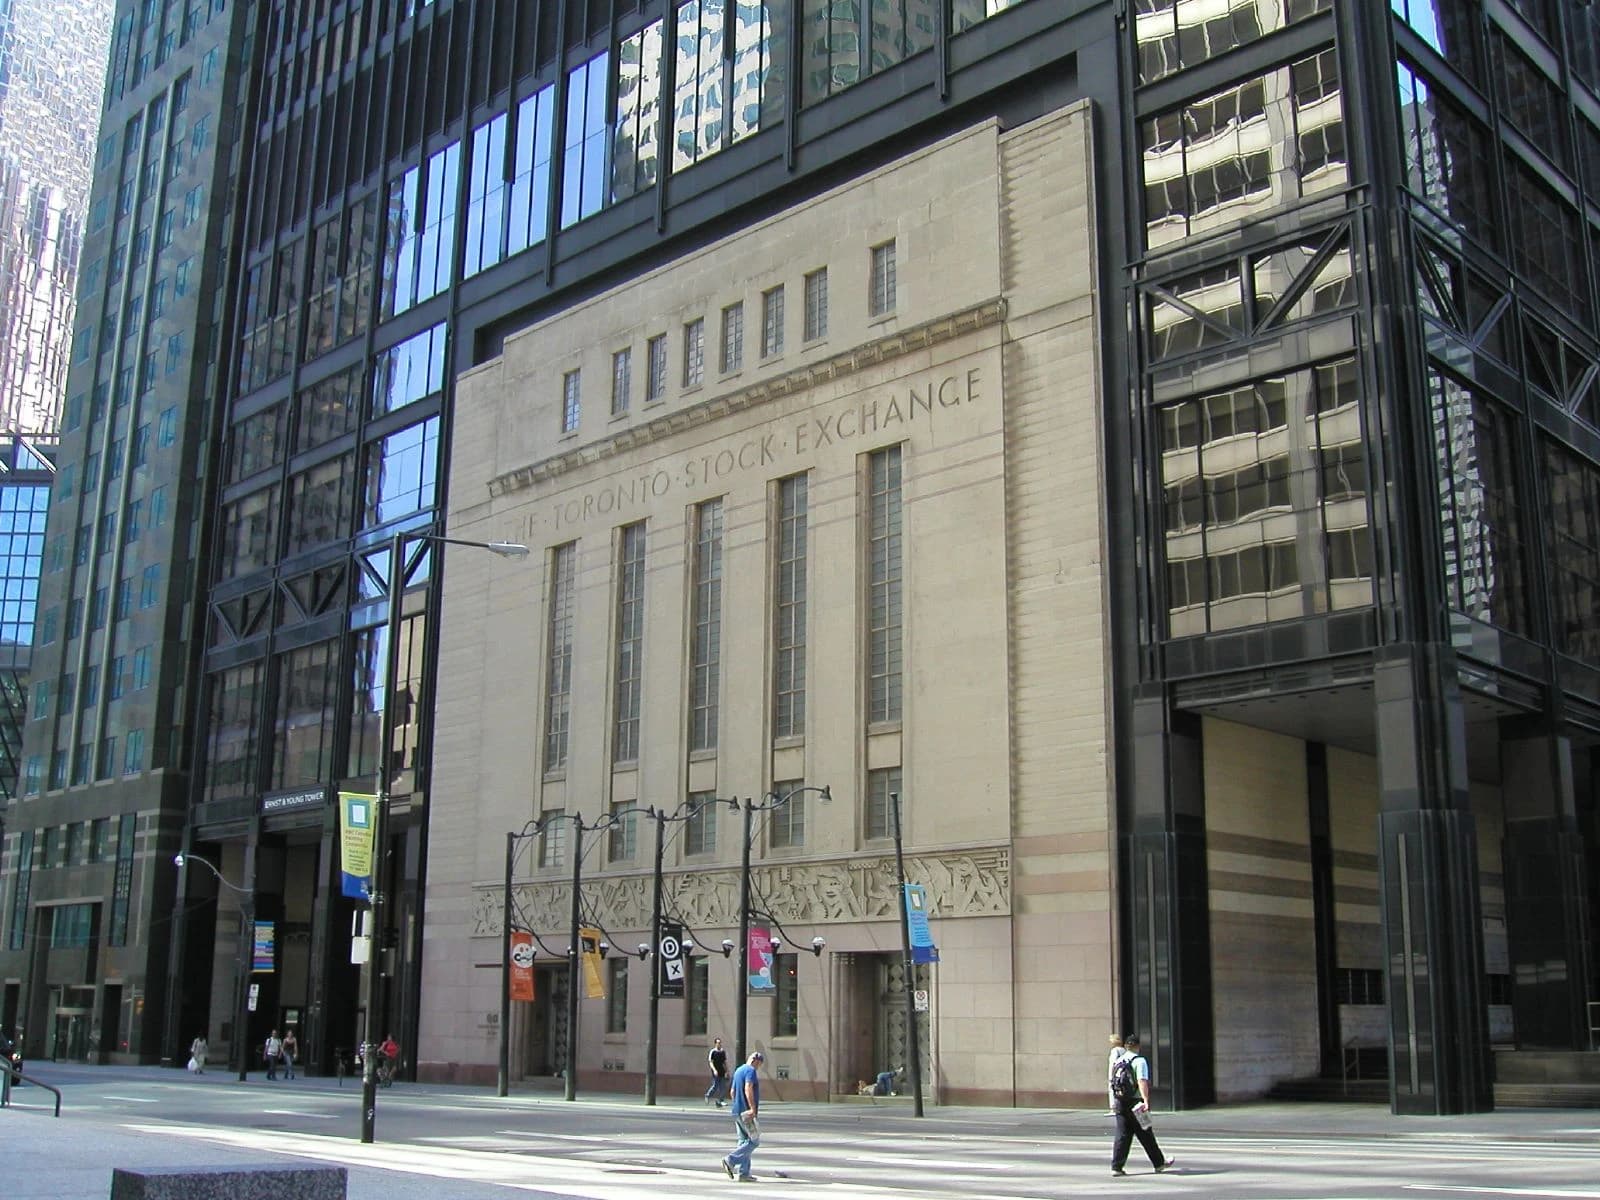
The S&P/TSX Composite slipped to 35,518.55 on Oct. 5, as a broad pullback across most sectors showed Canadian investors are still struggling with the same problem rattling global markets: higher bond yields and a tougher rate backdrop.
TSX pulls back as bond yields stay high
That matters because the TSX is especially sensitive to financing conditions. When borrowing costs rise, it gets harder for rate-sensitive sectors like utilities, real estate and financials to justify rich valuations, while even commodity-heavy parts of the market can be dragged lower if investors decide to de-risk. The result is a market that can look resilient on the surface but still lose altitude when money gets more expensive.
Sentiment IndicatorsⓘProprietary · adalytica.com · October 6, 2026
This is a snapshot — live sentiment, awareness and momentum for 130+ markets update continuously in the dashboard.Open AlphaPulse
The index’s recent price action reflects that tension. After touching 36,335.6 on Sept. 22, the TSX has given back more than 800 points, even though it remains above its 200-day moving average of 34,243.42. The 50-day average near 36,031.84 is now overhead resistance, while the relative strength index at 48.9 suggests momentum has cooled back to neutral after a stronger summer run. In other words, this is not a crash — it is a reset.
The broader macro setup helps explain why. U.S. 10-year Treasury yields were near 5.28%, levels that keep pressure on equities by offering investors a more competitive risk-free return. At the same time, the Federal Reserve’s policy rate is still around 3.75%, with U.S. unemployment at 4.2%, a mix that leaves the market guessing how long restrictive policy will stay in place. For Canadian stocks, that uncertainty is enough to keep multiple expansion in check.
There is also a currency angle. The U.S. dollar has weakened sharply in the recent data, but that has not been enough to offset the valuation squeeze from higher yields. For Canadian companies that borrow, invest and buy back stock in a higher-rate world, the cost of capital still matters more than a softer greenback over the short run.
For long-term investors, the message is simple: volatility is doing what volatility always does — forcing the market to reprice risk. That can create opportunities in quality companies with durable free cash flow and strong balance sheets, especially in Canada’s energy, financial and infrastructure names. It also argues for patience. Markets rarely move in a straight line, and the biggest winners are usually the businesses that can keep compounding through choppy tape.
If you are building wealth over the next three to 10 years, this kind of pullback is worth watching rather than fearing. The TSX is still holding above longer-term trend support, and that keeps the long-term bull case intact — but investors should expect more sensitivity to rates until bond markets settle down.
| Entity | Gains | Losses |
|---|---|---|
| Long-term buyers | ▲Better entry points | ▼Short-term mark-to-market pain |
| Rate-sensitive sectors | ▲Lower valuations may reset risk | ▼Higher discount rates |
| Financial strength leaders | ▲Relative outperformance potential | ▼Weak balance-sheet peers |
| Bond-market bulls | ▲Higher yields and income | ▼Equity valuations |